

The short answer
- Almost: at $3,700 a month after tax, Linda's savings last until 92, three years short of 95.
- Delaying CPP and OAS to 70 would carry her to 95.
- So would cutting her rent by $250 a month.
Estimates from Scenario Lab+, in today's dollars.
See the demo plan$500,000 is a solid foundation for retirement, and at 65 you don't have to make it stretch on its own. CPP and OAS start right away, and on a plan this size they cover a big share of your income for life. What matters most is how you put the pieces together, from when you start your benefits to what you pay for housing. If you're retiring at 65 with $500,000, a few well-chosen decisions can make a real difference to how long your money lasts.
Here at Loonie Nest, our mission is to provide free and affordable personal finance education to Canadians so they can gain confidence in their retirement.
Linda's plan at a glance
$500,000
saved at 65
RRSP
$320,000
Taxed as income when withdrawn
TFSA
$110,000
Withdrawals are tax-free
Non-registered
$50,000
Only the capital gain is taxed
Cash
$20,000
Withdrawals are tax-free
Spending after tax, in today's dollars
$44,400
$39,960
$35,520
CPP $850 a month from 65
OAS $742 a month from 65
Our $500K Retirement Scenario
Let's meet Linda. She's 65, single, and living in London, ON. Linda spent most of her career as the office manager at a small law firm, a job without a workplace pension. She rents a one-bedroom apartment, and she put money away every year, building up $500,000 across her RRSP, TFSA, a small non-registered account and some cash. She's ready to retire, and she wants to know how to make her savings last.
We'll run Linda's numbers through Scenario Lab+.
Scenario Lab+ is our proprietary retirement planning software. We'll use it to generate and review a tailored retirement plan for her.
To start, here's how Linda's numbers look as she retires at 65:
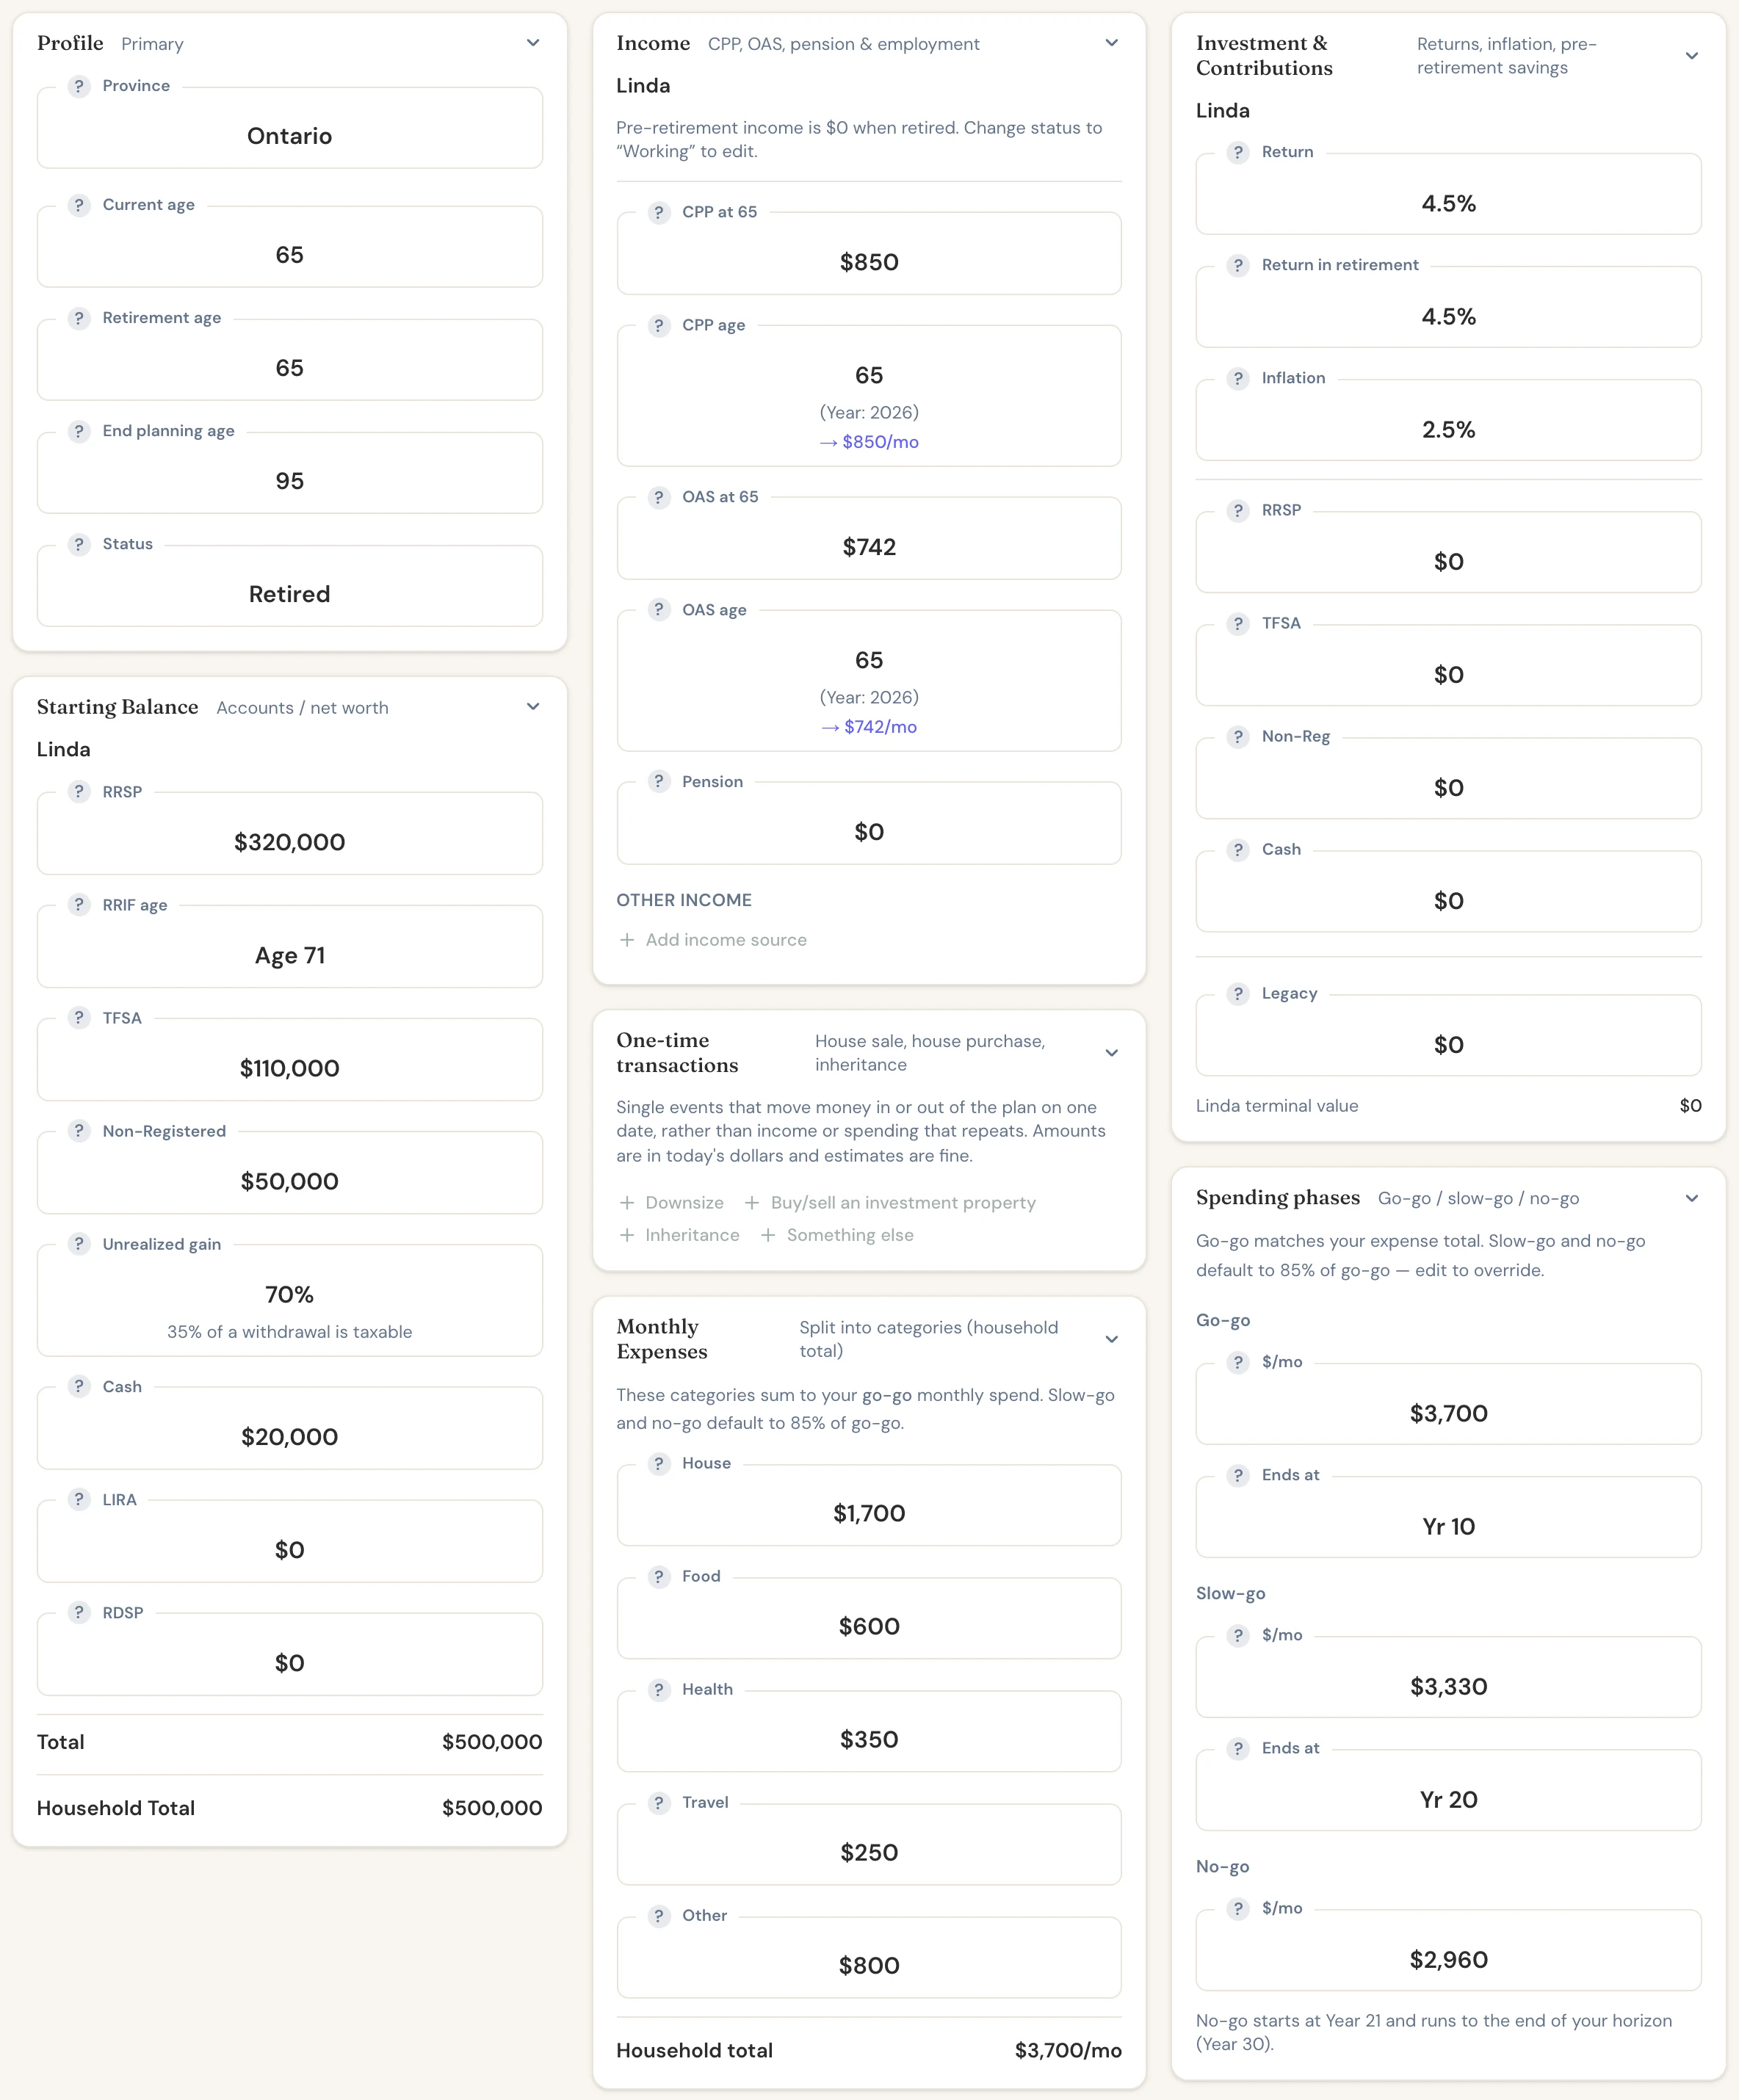 Linda's plan inputs: her profile, account balances, CPP and OAS, and monthly spending.
Linda's CPP is $850 a month at 65. That's what her CPP Statement of Contributions shows after a long career at a moderate salary. She also gets the full OAS pension, about $742 a month. If you want a refresher on how both programs work, see our guide to CPP and OAS.
She rents. Rent is the biggest line in her budget, and she doesn't have home equity to fall back on later. That makes her plan a little more sensitive to her housing costs than a homeowner's.
She invests conservatively. Linda prefers steady over exciting, so her portfolio leans on bonds and GICs. Her plan assumes it grows 4.5% a year.
Her spending falls as she ages. Most retirees spend more in their go-go years, and less later on. Linda's plan starts at $3,700 a month and assumes that her spending steps down as she reaches 75 and again at 85. In Scenario Lab+, these steps are the plan's Spending Phases.
A few other important assumptions: all figures are in today's dollars, Linda is single, and inflation runs at 2.5% a year.
Linda's retirement budget
Here is how her $3,700 a month breaks down in her first ten years:
| Category | Monthly | Annual |
|---|---|---|
| Housing (rent, utilities, tenant insurance) | $1,700 | $20,400 |
| Food and dining | $600 | $7,200 |
| Health and dental | $350 | $4,200 |
| Travel | $250 | $3,000 |
| Everything else (transit, gifts, entertainment) | $800 | $9,600 |
| Total | $3,700 | $44,400 |
Rent is close to half her budget. Costs also vary a lot across the province. Our guide to the best places to retire in Canada compares cities and regions.
Is $500K Enough to Retire at 65?
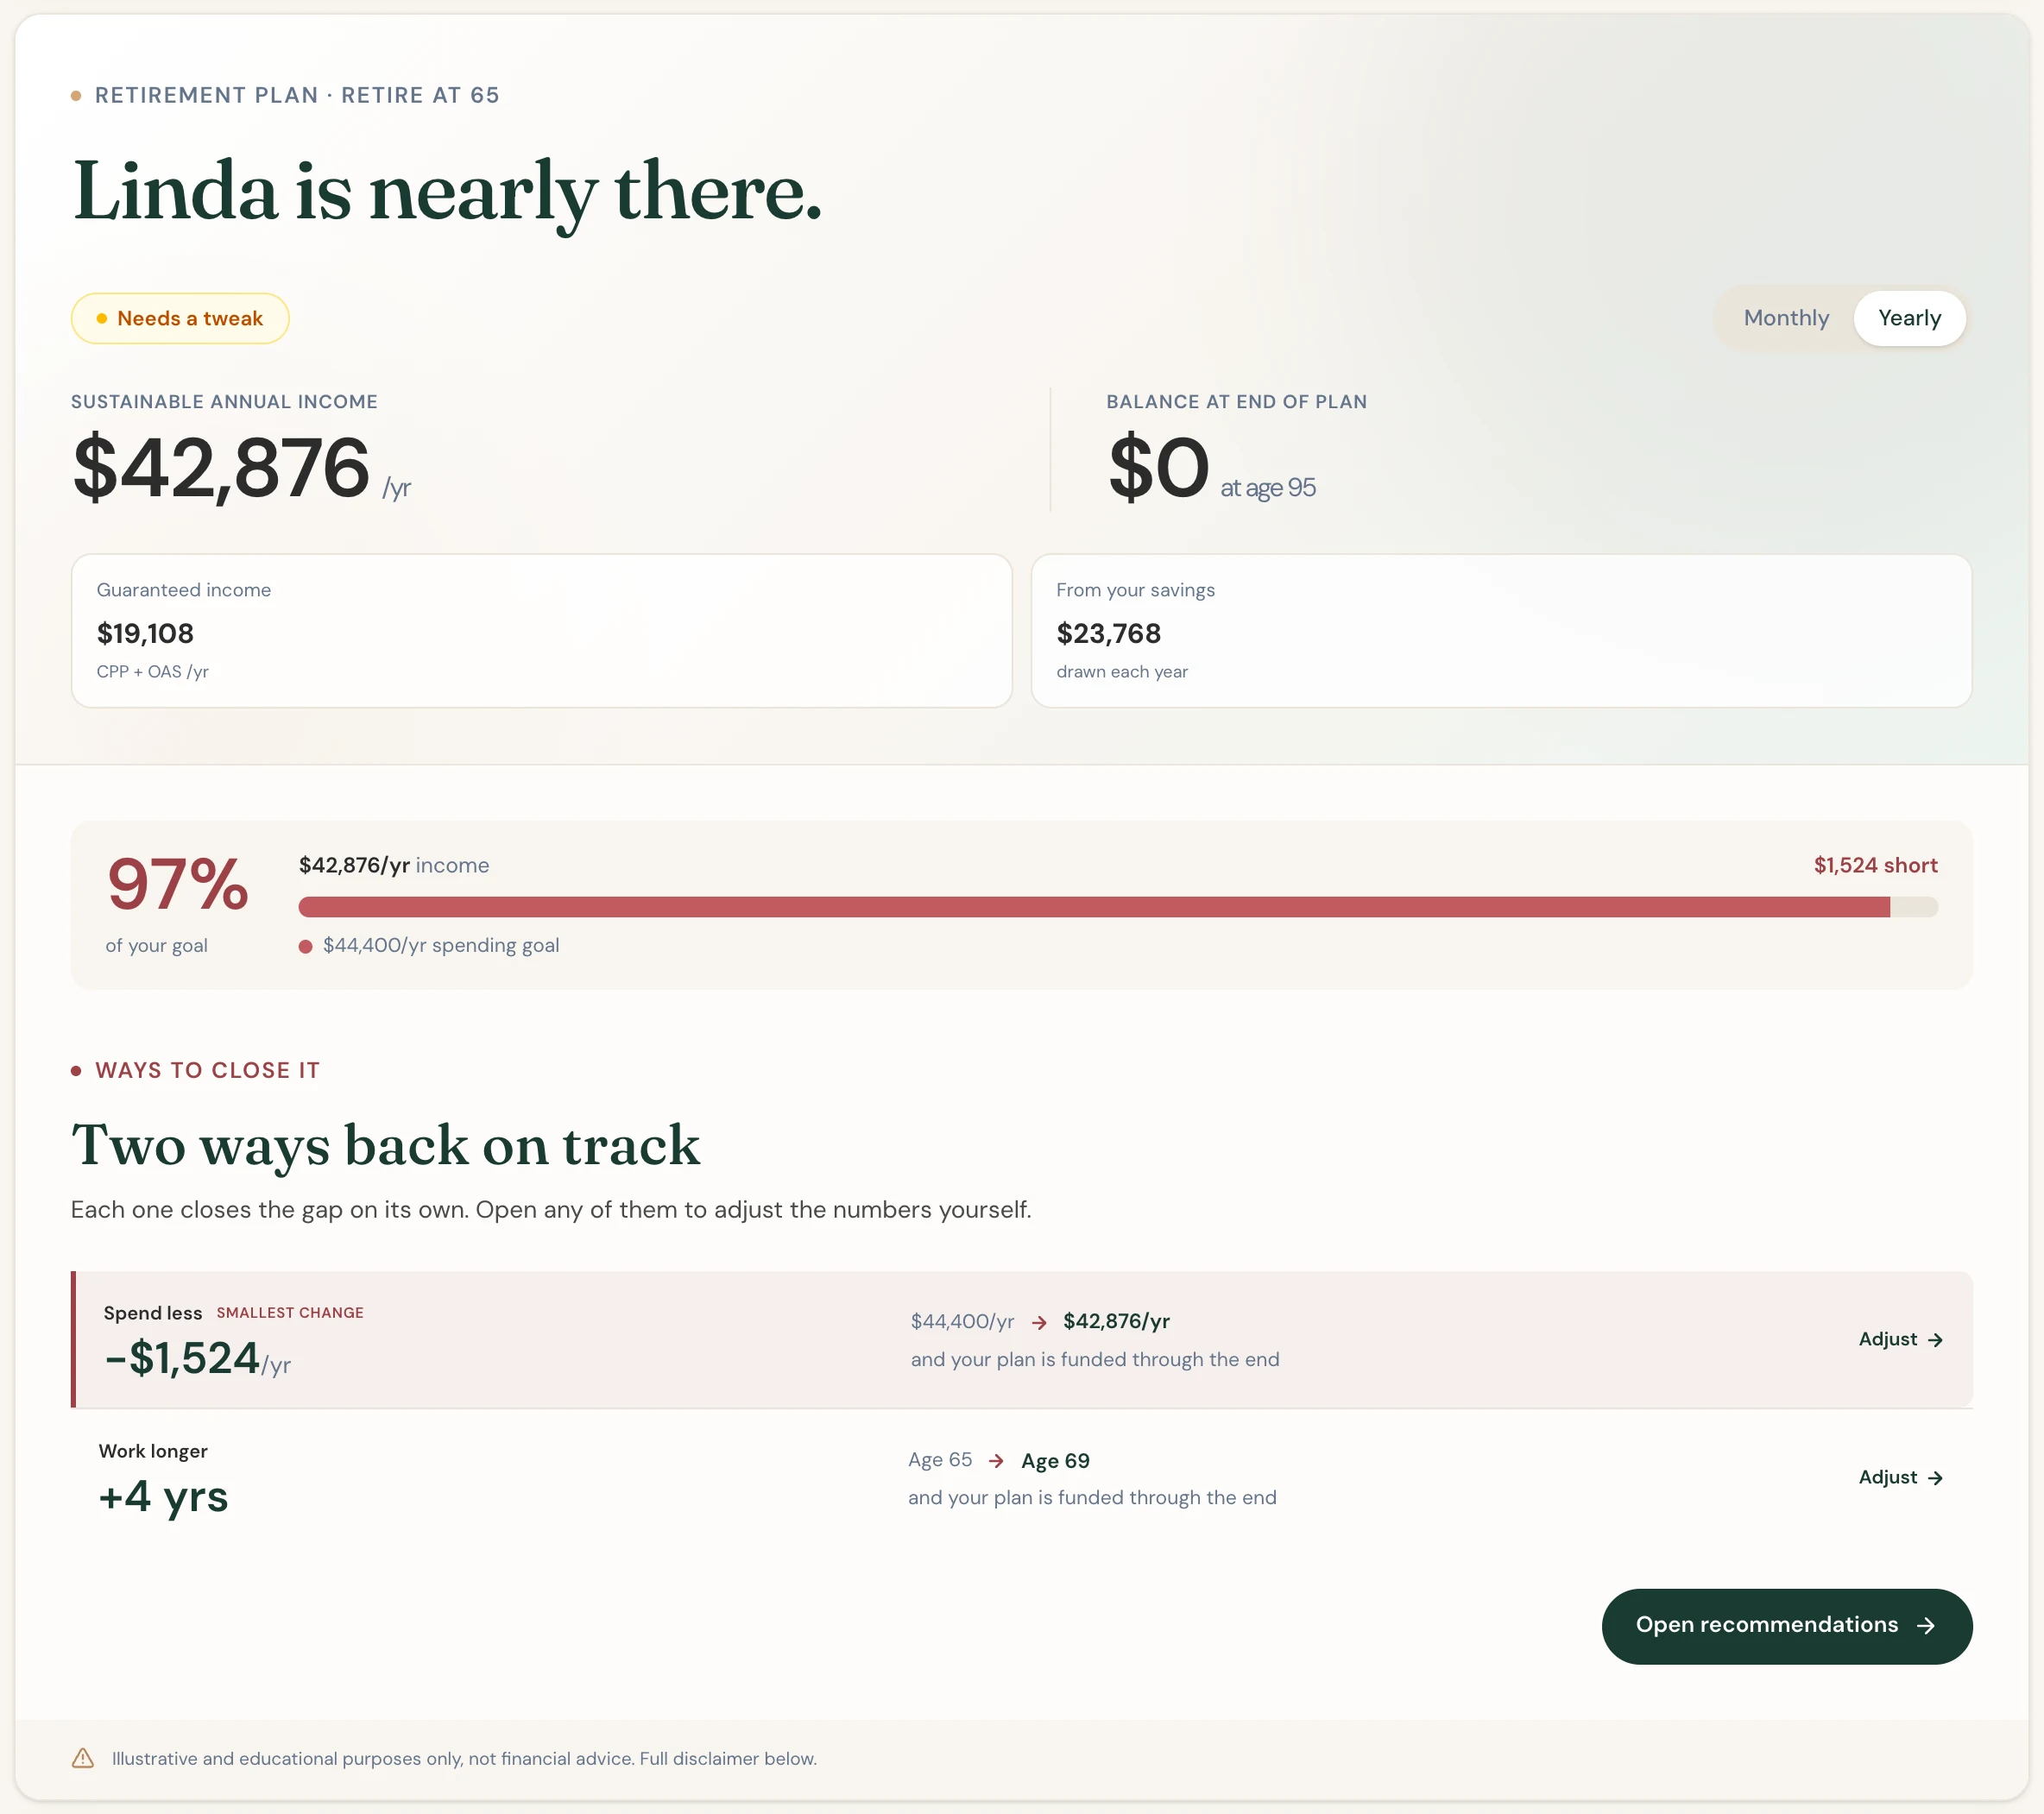 Scenario Lab+'s results: Linda is nearly there.
For Linda, the results say almost. Her savings last until 92, three years short of the end of her plan at 95. After that, CPP and OAS would still pay her about $20,000 a year, but her plan calls for about $35,500.
The gap is small. Scenario Lab+ estimates she'd need to spend about $127 a month less to reach 95, and the scenarios below show a few other ways to close it.
That's still a better result than a generic 4% rule would suggest. Under the 4% rule, $500,000 supports about $20,000 a year. Linda draws about $28,600 in her first year, closer to 5.7%, and her money lasts almost thirty years. CPP and OAS starting the day she retires, and her spending easing off in her 70s and 80s, make up most of the difference.
How Much Income Does $500K Provide?
So how much retirement income does a $500K nest egg generate? For Linda, $500,000 plus CPP and OAS provides $47,680 of gross income in her first year, which works out to $3,700 a month after tax.
In her first year of retirement, Linda draws on six sources:
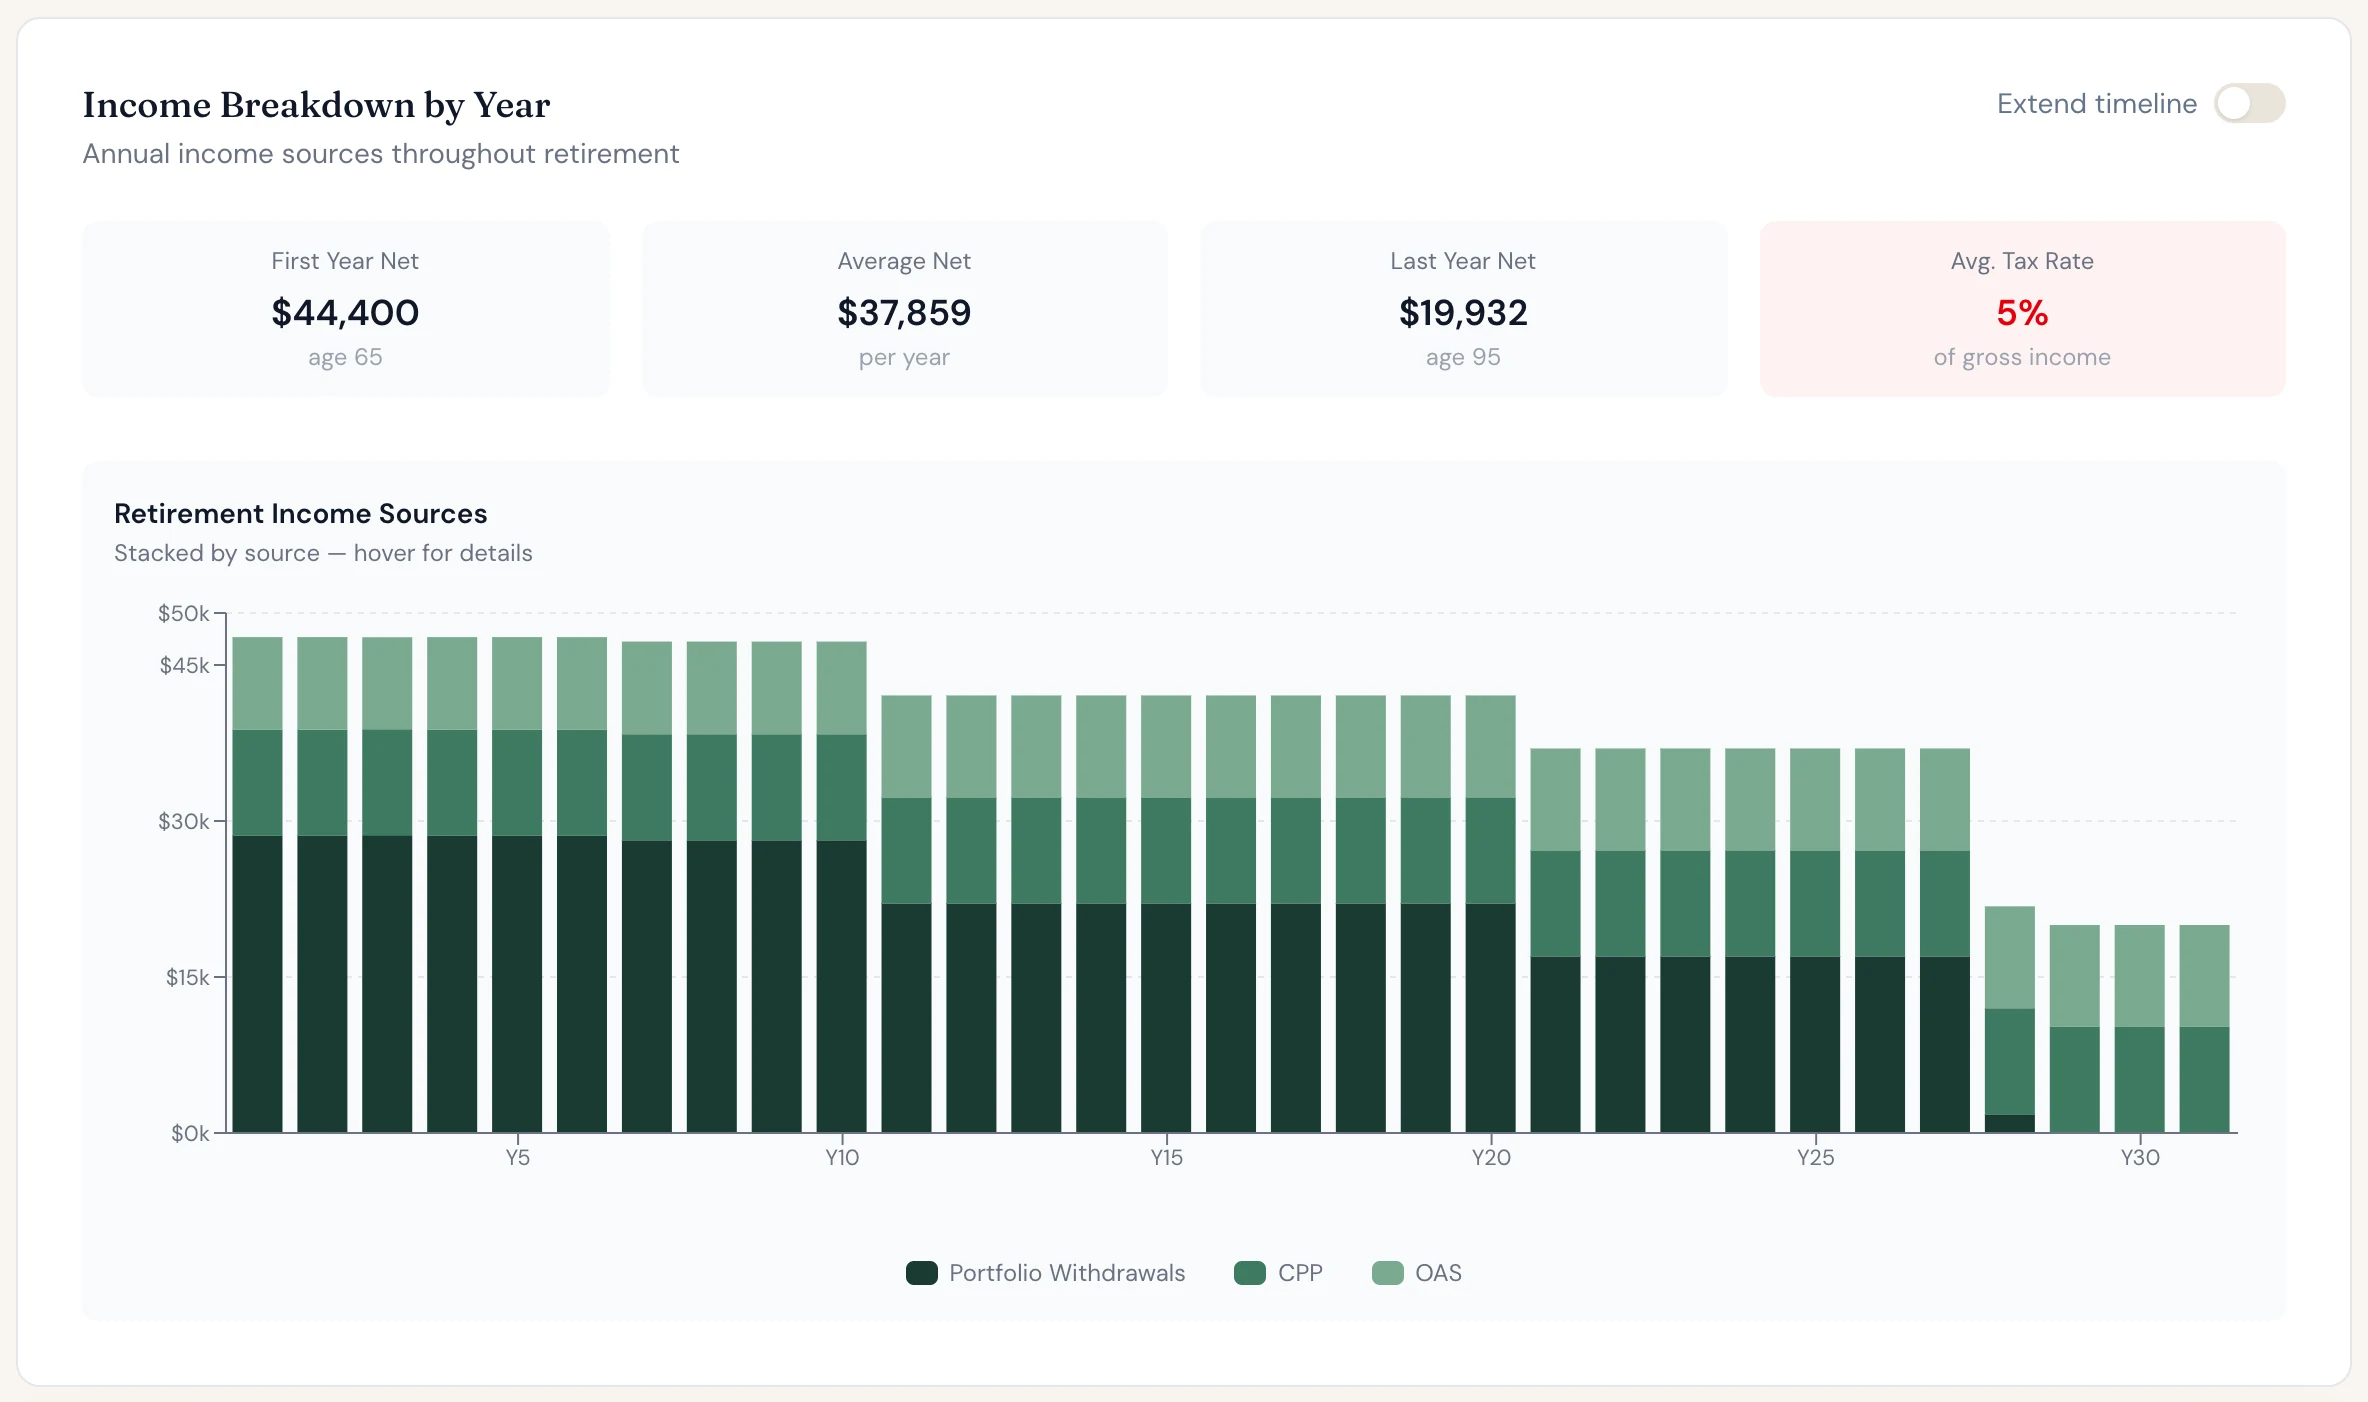 Where Linda's income comes from each year, by source.
| Source | Amount | Taxable? |
|---|---|---|
| CPP | $10,200 | Yes |
| OAS | $8,908 | Yes |
| RRSP withdrawals | $18,286 | Yes |
| TFSA withdrawals | $6,286 | No |
| Non-registered withdrawals | $2,857 | Only the capital gain |
| Cash savings | $1,143 | No |
| Gross income | $47,680 | |
| Income tax | $3,280 | |
| Spending money | $44,400 |
CPP and OAS bring in $19,108 a year. That's 40% of her income, paid for life and indexed to inflation. On a $1 million plan like Susan's, the same benefits cover about a third. The smaller your savings, the more your government benefits matter, and the more it pays to get their timing right.
Scenario Lab+ uses its Proportional drawdown strategy by default, drawing from every account each year roughly in proportion to its balance. That keeps her taxable income steady from year to year. The Drawdown tab runs the same plan through other withdrawal strategies, such as Sequential and RRSP Meltdown, and compares the lifetime tax of each.
What would your income look like at 65?
Scenario Lab+ builds this same year-by-year breakdown from your own accounts, benefits and spending, so you can see where every dollar of your retirement income comes from.
Try Scenario Lab+How Much Tax Linda Pays
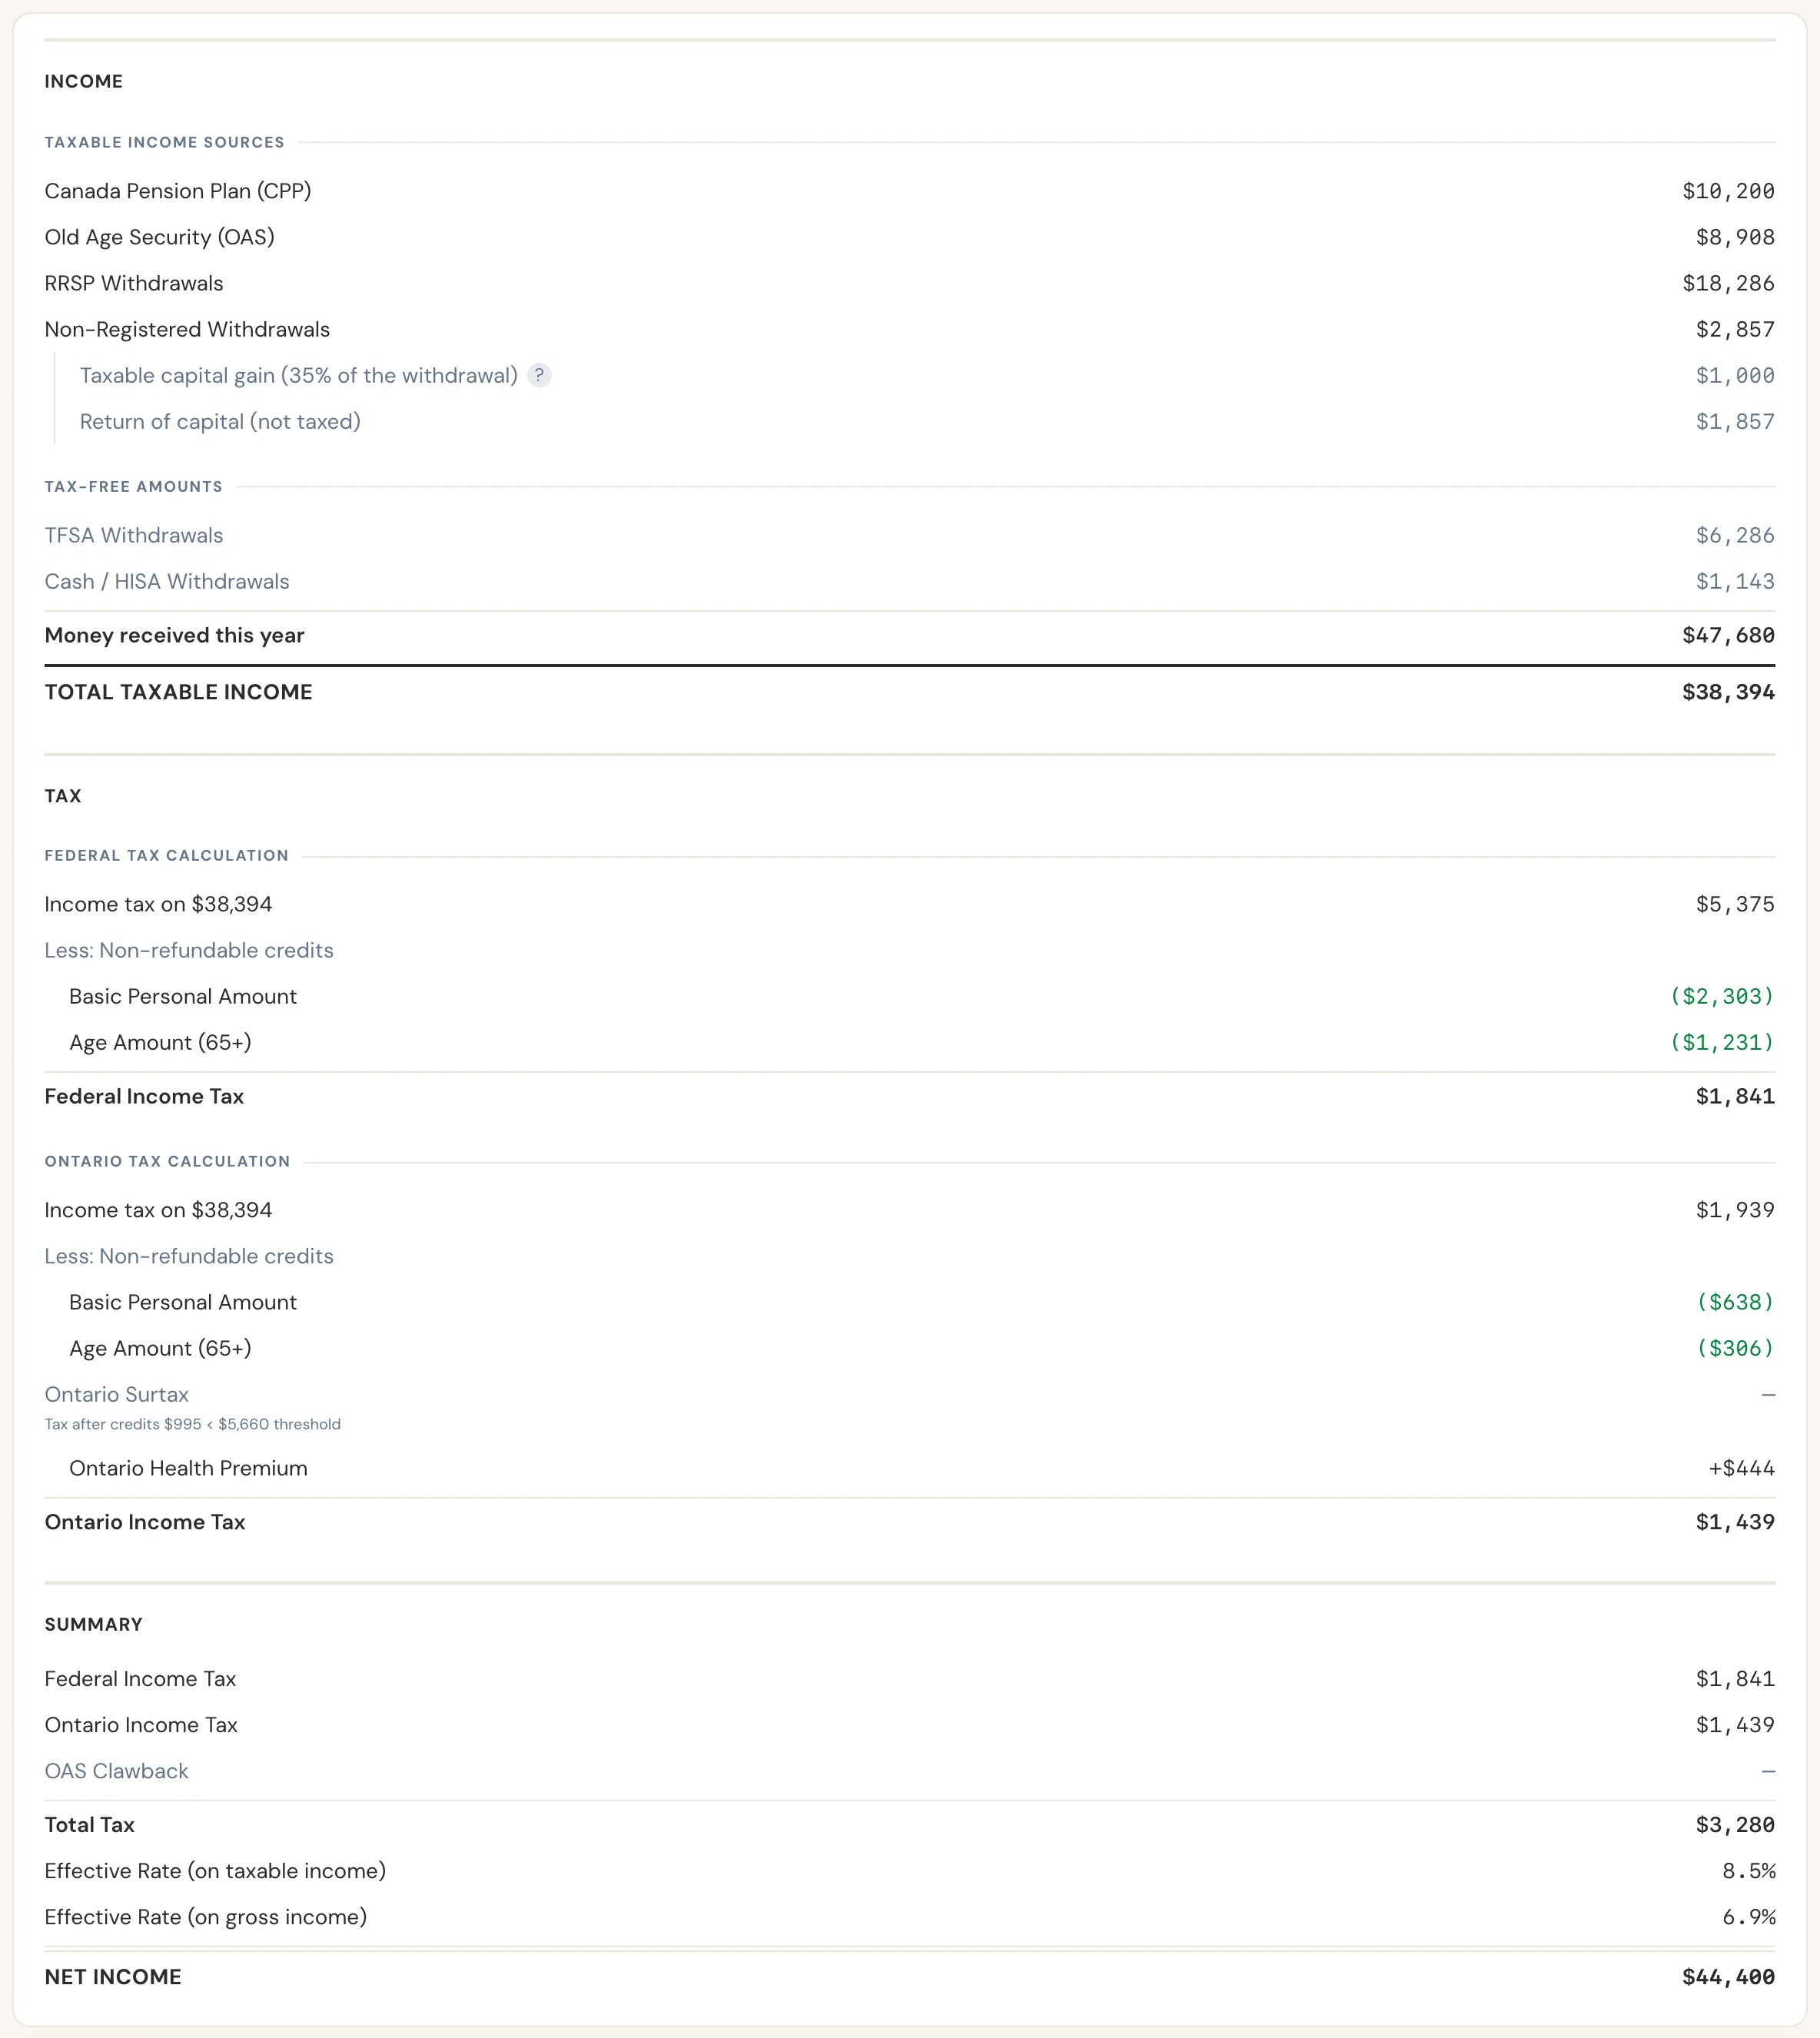 Linda's tax bill in her first year of retirement, at age 65.
Linda pays $3,280 in income tax in her first year of retirement. That works out to about 6.9% of her gross income.
Her taxable income comes to about $38,400. Her TFSA and cash withdrawals are tax-free, and only part of her non-registered withdrawals is taxable. At 65 she also gets the age amount tax credit, which lowers her bill further.
She is nowhere near the OAS recovery tax (or clawback). Our explainer on the OAS clawback covers how it works and who is affected. To estimate your own bill, try our free Canadian income tax calculator.
How Her Plan Changes Over Time
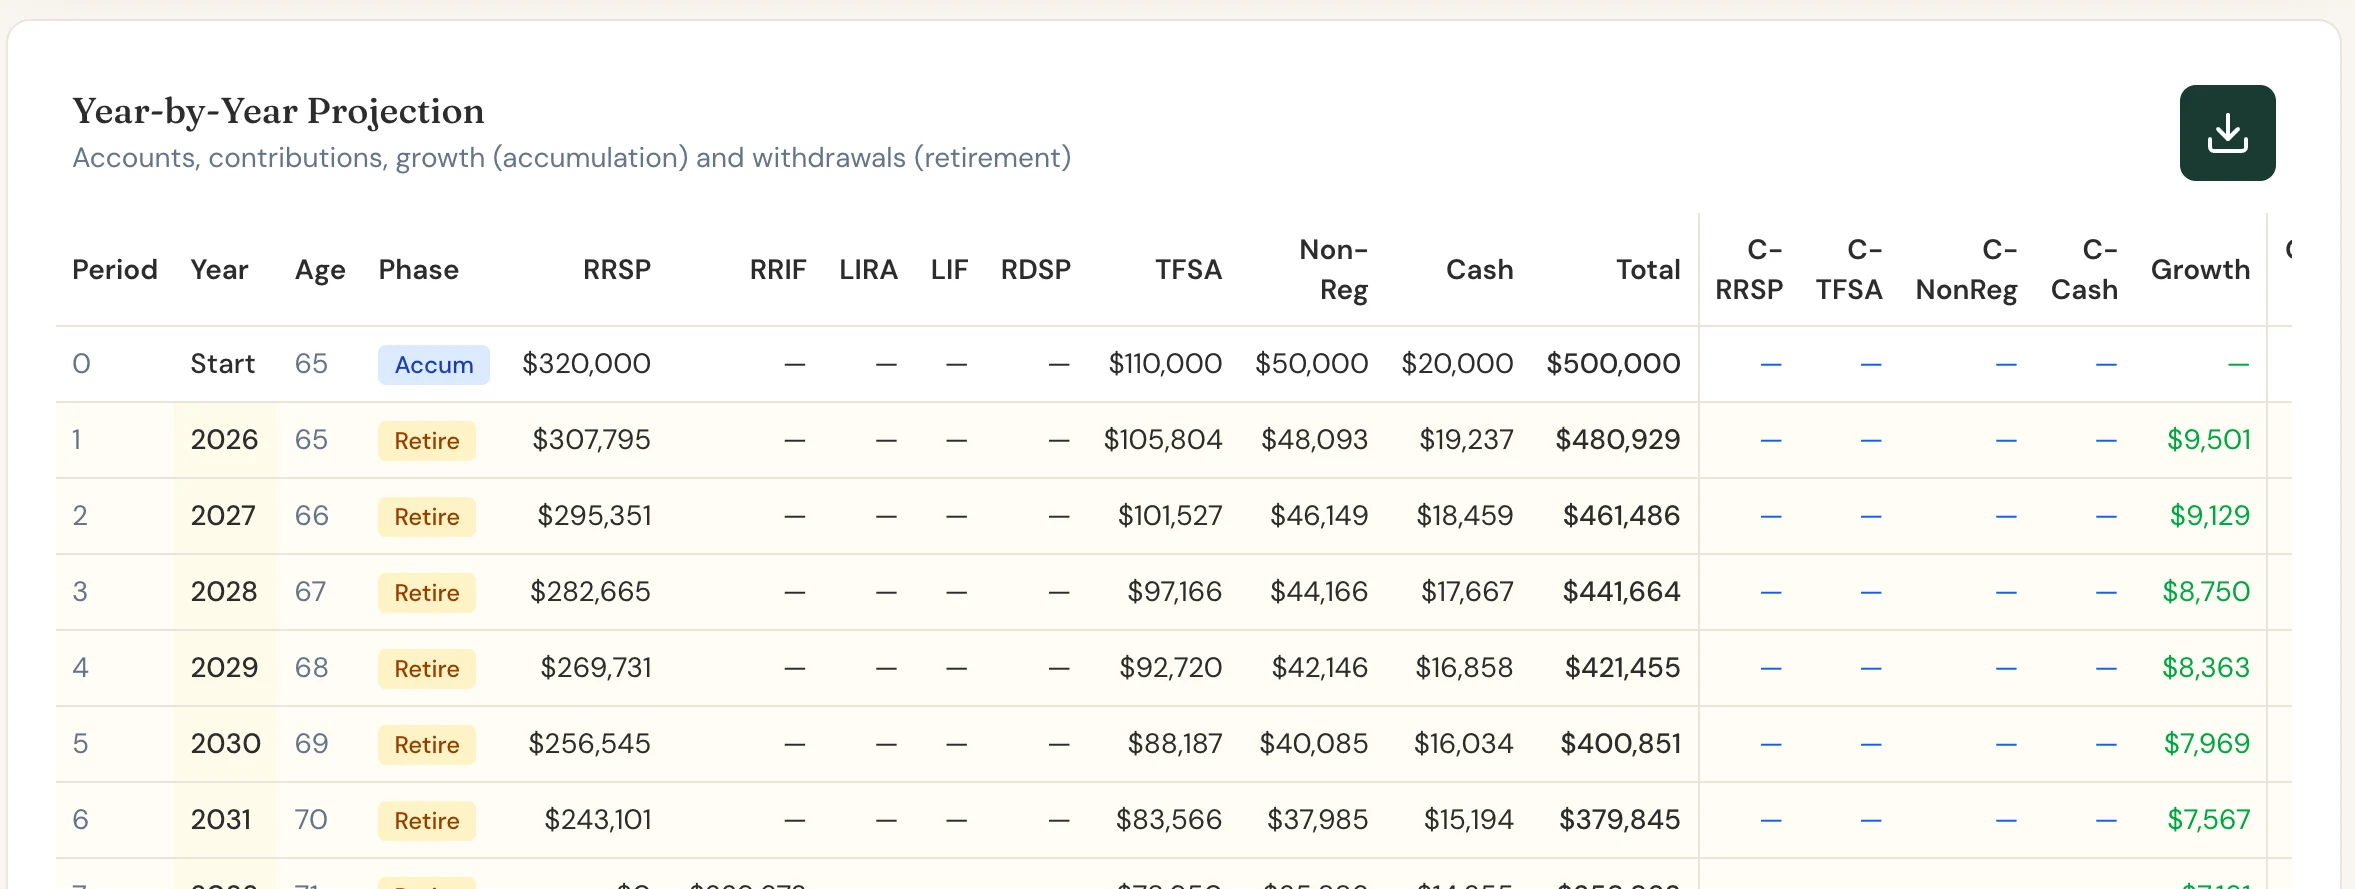 Year-by-year account balances from 65.
In Scenario Lab+, the Table tab shows every account for every year, and the whole table downloads as an Excel file.
Like many retirees, Linda's retirement will not look the same every year.
At 71, her RRSP becomes a RRIF. Every Canadian has to convert their RRSP by the end of the year they turn 71, and a RRIF has a minimum withdrawal each year. Linda already withdraws more than the minimum, so her withdrawals barely change. Our RRIF guide covers the rules.
At 75, her OAS goes up 10% and her spending steps down. OAS pays more from age 75, so hers rises from $8,908 to $9,798 a year, while her spending drops to $3,330 a month.
At 92, her savings run out. From there, CPP and OAS are what she has: about $20,000 a year, a bit over half of what her plan calls for at that age.
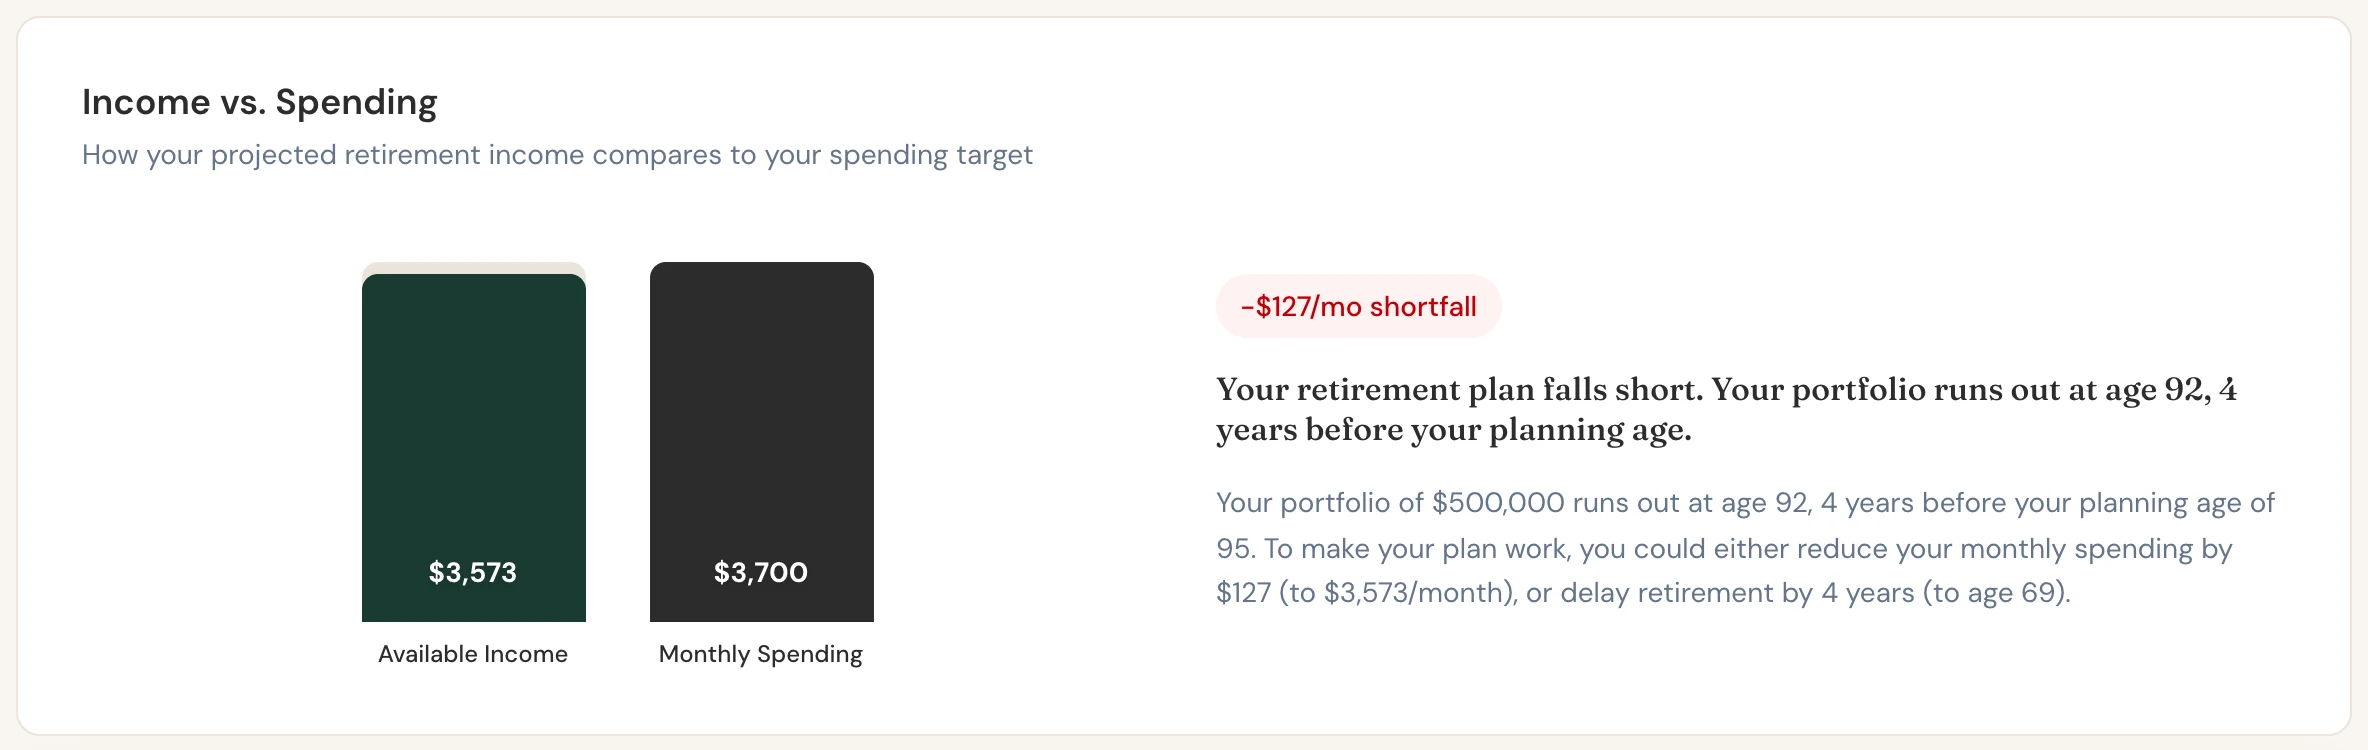 Income available to Linda compared with what she plans to spend.
Scenario Lab+'s Recommendations tab sizes each fix, such as spending less or retiring later, and you can apply one with a click to see the plan rebuild around it.
Based on her numbers, Scenario Lab+ estimates Linda needs to spend about $127 less every month to make her money last to 95.
But What If We Change the Assumptions?
Linda's plan is close. So we looked for changes she could realistically make that would carry her the rest of the way, and tested one at a time.
4 versions of Linda's plan
One assumption changed in each. Charts show the portfolio from 65 to 95 in Scenario Lab+.
Linda's base plan
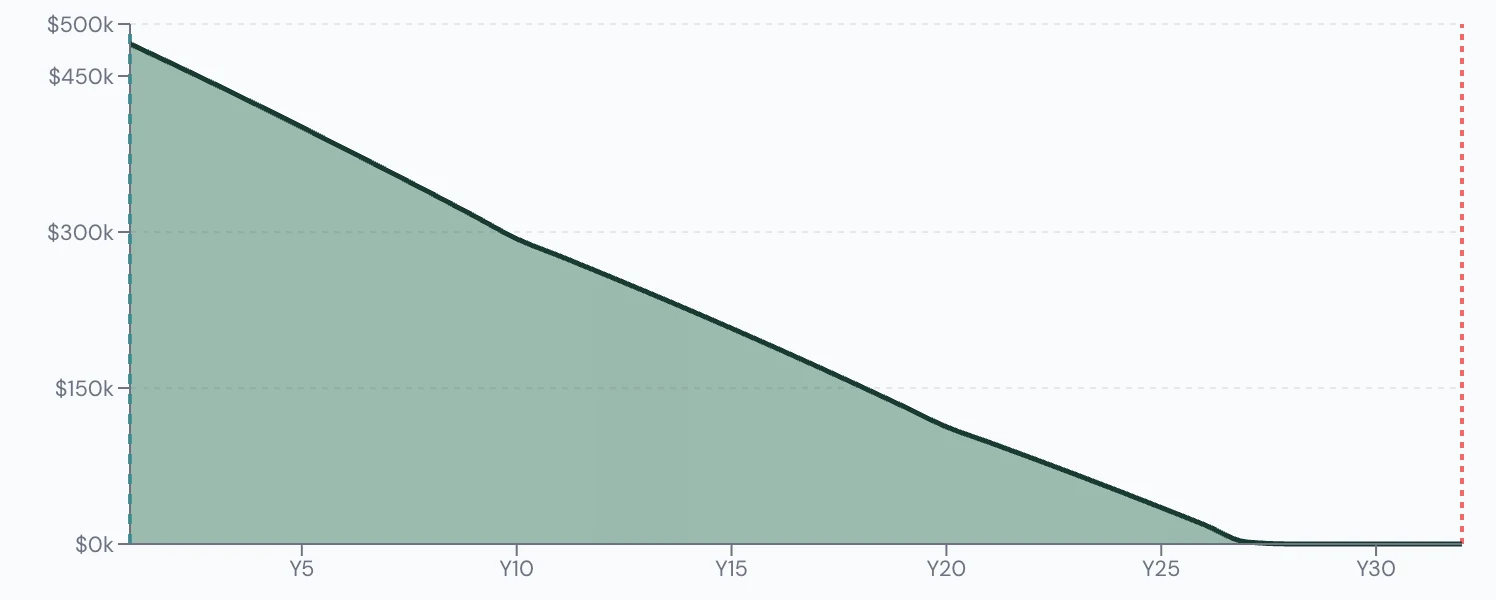
- Spends at 65
- $44,400/yr
- Money lasts
- To age 92
- Left at 95
- $0
Delays CPP and OAS to 70
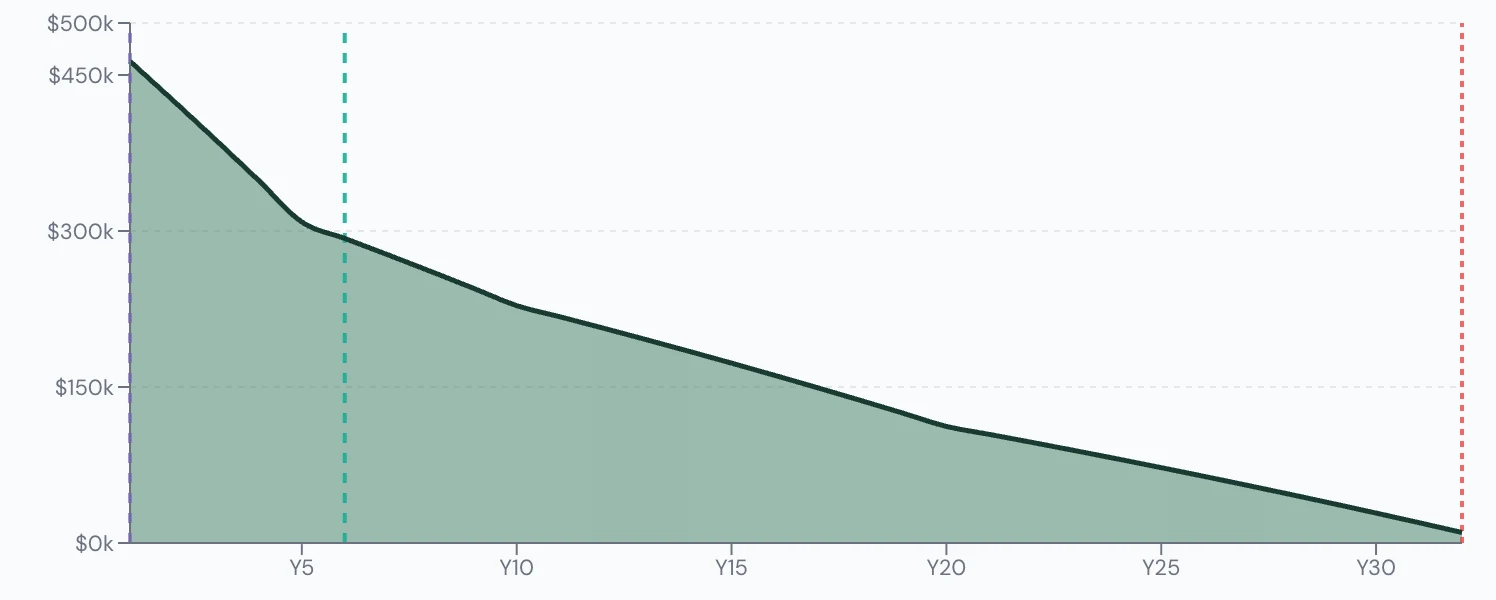
- Spends at 65
- $44,400/yr
- Money lasts
- Past 95
- Left at 95
- $19,532
Moves to a smaller apartment
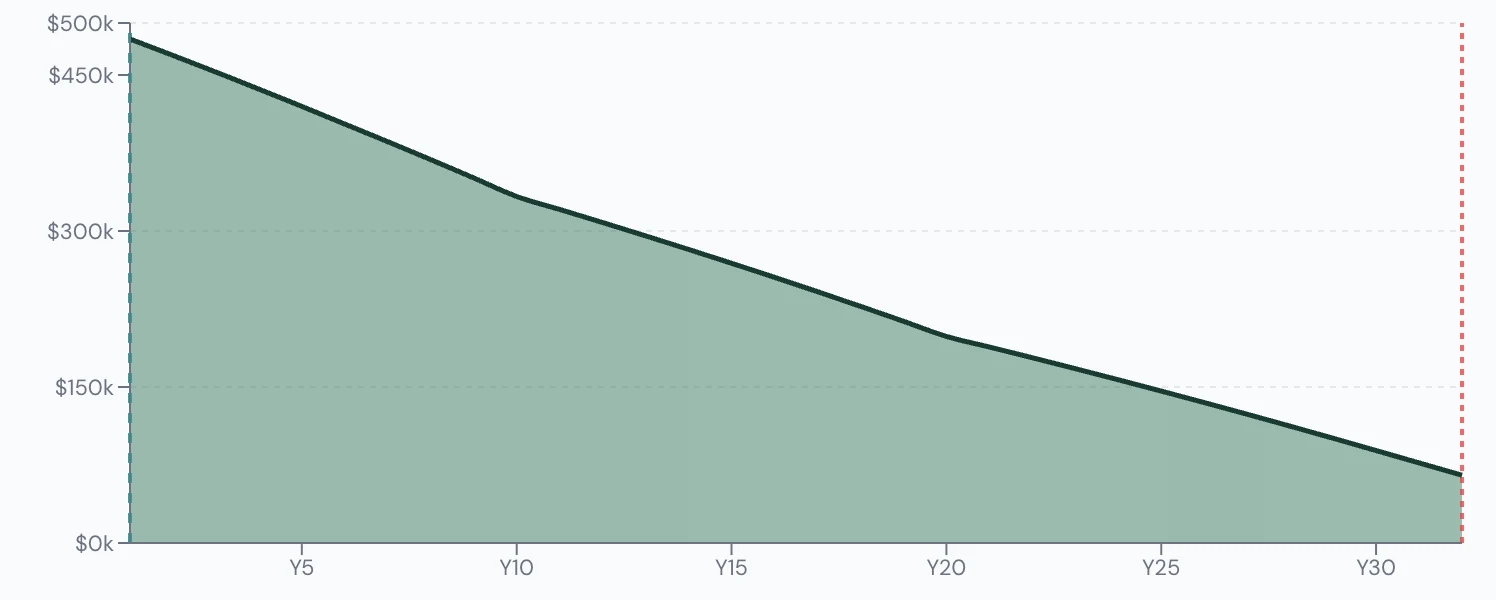
- Spends at 65
- $41,400/yr
- Money lasts
- Past 95
- Left at 95
- $77,019
Draws her TFSA last
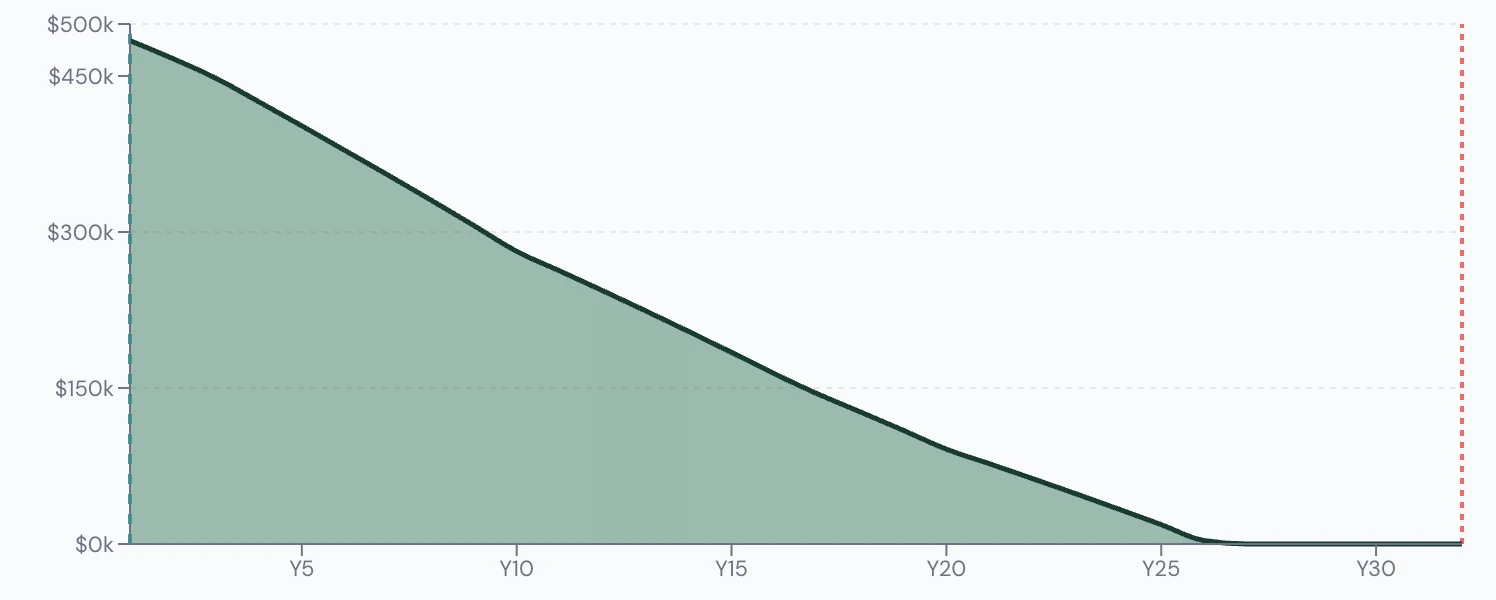
- Spends at 65
- $44,400/yr
- Money lasts
- To age 91
- Left at 95
- $0
Scenario 1
Delays CPP and OAS to 70
- Spends at 65
- $44,400/yr
- Money lasts
- Past 95
- Left at 95
- $19,532
Both programs pay more if you delay them. CPP rises 42% if you start at 70 instead of 65, and OAS rises 36%. For Linda that means $14,484 a year of CPP instead of $10,200, and $12,114 of OAS instead of $8,908.
The catch is that she has to live entirely on her savings from 65 to 69. By 69 her portfolio is down to $308,611, compared with $400,851 in her original plan. After that, the larger government cheques do far more of the work, and her plan lasts all the way to 95 with $19,532 left. Her tax bill in her first year also drops to $1,758, because she has no CPP or OAS income yet.
For someone with modest savings and good health, delaying can be one of the stronger levers, because it turns savings into bigger income that's guaranteed for life. Our CPP and OAS break-even calculator shows where that line falls for you.
Scenario 2
Moves to a smaller apartment
- Spends at 65
- $41,400/yr
- Money lasts
- Past 95
- Left at 95
- $77,019
Rent is Linda's biggest expense, so it's also her biggest lever. What if she moves to a slightly smaller or cheaper apartment and cuts her housing costs by $250 a month?
That alone fixes her plan. Her budget drops to $3,450 a month, and she reaches 95 with $77,019 left, with a little room to spare. Because she's spending less, she also withdraws less, and her first-year tax falls to $2,672.
For renters, housing is often the most flexible cost in retirement, and a small change adds up over thirty years.
Scenario 3
Draws her TFSA last
- Spends at 65
- $44,400/yr
- Money lasts
- To age 91
- Left at 95
- $0
A common piece of advice is to draw from taxable accounts first and save your TFSA for last. What if Linda does exactly that, drawing her cash, then her non-registered account, then her RRSP, and only then her TFSA? That's the Sequential strategy in Scenario Lab+'s Drawdown tab.
Her tax bill in her first year falls to just $255, down from $3,280. But her savings run out at 91, a year earlier than in her original plan. Leaving her RRSP until later bunches her taxable income into fewer years, and over her whole retirement she pays about $7,400 more in tax than with the balanced approach.
It's a good reminder that a lower tax bill this year isn't the same as a plan that lasts longer. For Linda, drawing from every account at once keeps her taxable income steady, and that works better.
Your $500K Is Not Linda's $500K
So is $500,000 enough to retire at 65? For Linda it's very close, and delaying her benefits or trimming her rent would get her there. Her plan is a starting point, not an answer for anyone else.
Two people with exactly $500,000 can end up with very different retirements. What they spend, whether they rent or own, how much CPP and OAS they receive, and when they start those benefits can make all the difference. Retiring at 60 on similar savings takes different moves, as Gary's plan at 60 shows.
The bigger risk is guessing whether $500,000 is enough without running your own scenario.
That's why we built Scenario Lab+.
It is the software behind every number in this article. Give it your own accounts and spending, and it builds the same year-by-year plan for you, including every what-if above. If you'd like to see it first, Linda's full plan is open to explore.
Build Your Own Canadian Retirement Plan
Enter your own savings, benefits and spending in Scenario Lab+ to see whether your number is enough and what happens when your assumptions change.
Start now