

The short answer
- Yes: $1 million at 50 supports $3,800 a month after tax for Dave, with $906K left at 90.
- He lives entirely on his savings for 15 years before CPP and OAS, and pays $3,110 of tax in his first year.
- Keeping his travel budget until 75 instead of 60 costs him about $250,000 by 90.
Estimates from Scenario Lab+, in today's dollars.
See the demo planRetiring at 50 means paying for 15 years before OAS starts, and at least 10 before CPP can. That's a long time to live on savings, and it's the part of an early retirement most people worry about. It's also the part with the most room to plan, because for those 15 years you have almost no other taxable income.
Here at Loonie Nest, our mission is to provide free and affordable personal finance education to Canadians so they can gain confidence in their retirement.
Dave's plan at a glance
$1,000,000
saved at 50
RRSP
$550,000
Taxed as income when withdrawn
TFSA
$180,000
Withdrawals are tax-free
Non-registered
$270,000
Only the capital gain is taxed
Spending after tax, in today's dollars
$45,600
$38,400
$36,000
CPP $800 a month from 65
OAS $742 a month from 65
Our $1 Million Retirement Scenario
Let's meet Dave. He's 50, single, and living in Kamloops, BC. He ran IT for a regional trucking company for most of his career, saving through the company's group RRSP and putting extra into his TFSA and a non-registered account. He has $1 million, a paid-off house, and a list of places he wants to see while he's young enough to enjoy them.
We'll run Dave's numbers through Scenario Lab+.
Scenario Lab+ is our proprietary retirement planning software. We'll use it to generate and review a tailored retirement plan for him.
To start, here's how Dave's numbers look as he retires at 50:
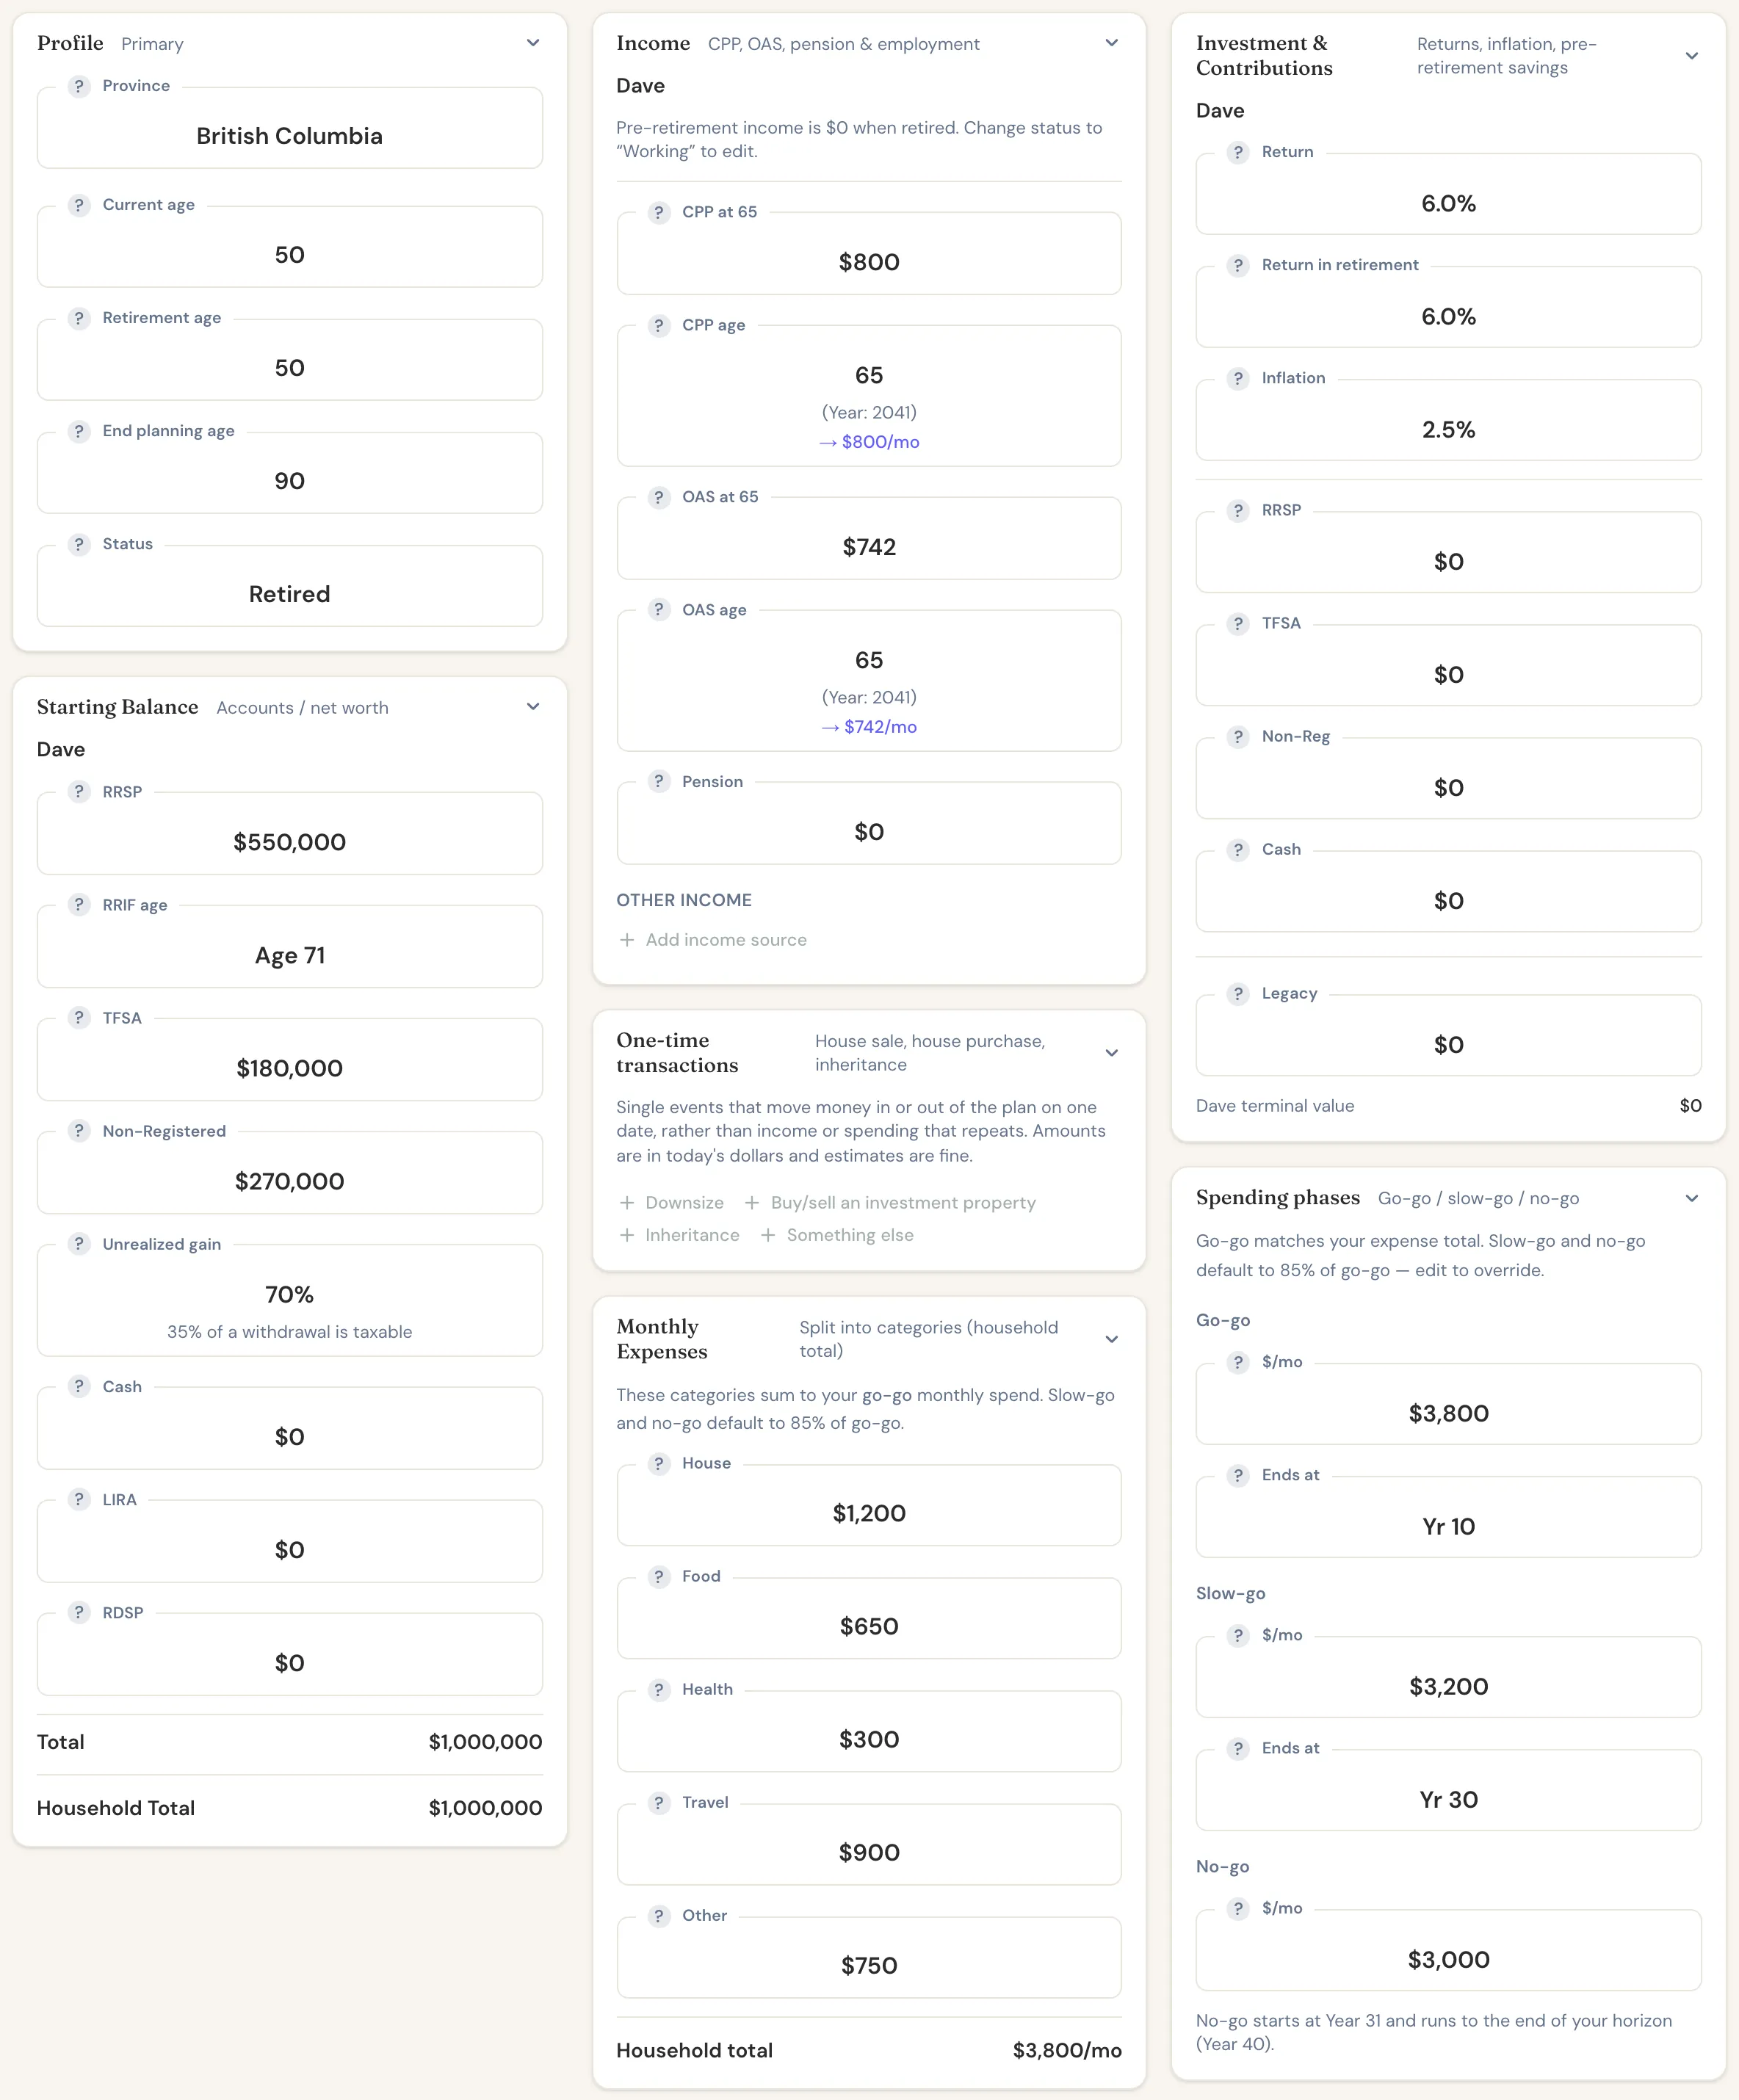 Dave's plan inputs: his profile, account balances, CPP and OAS, and monthly spending.
His $1 million is spread across three accounts. He has $550,000 in his RRSP, $180,000 in his TFSA, and $270,000 in a non-registered account.
Dave's CPP is $800 a month at 65. His Statement of Contributions assumes he stops contributing at 50, and 15 empty years pull the amount well below what a full career would pay. He gets the full OAS at 65. If you want a refresher on how both programs work, see our guide to CPP and OAS.
He spends more in his first ten years. Dave's plan starts at $3,800 a month while he travels, drops to $3,200 at 60, and to $3,000 at 80. Scenario Lab+ lets you set your own Spending Phases, with your own ages and amounts, rather than assuming everyone slows down at 75.
A growth portfolio over a long horizon. He expects his investments to grow 6% a year, and we plan his retirement to age 90.
A few other important assumptions: all figures are in today's dollars, Dave is single and owns his home with no mortgage, and inflation runs at 2.5% a year.
Dave's retirement budget
Here is how his $3,800 a month breaks down in his first ten years:
| Category | Monthly | Annual |
|---|---|---|
| Housing (property tax, utilities, insurance, upkeep) | $1,200 | $14,400 |
| Food and dining | $650 | $7,800 |
| Health and dental | $300 | $3,600 |
| Travel | $900 | $10,800 |
| Everything else (car, gifts, entertainment) | $750 | $9,000 |
| Total | $3,800 | $45,600 |
A budget like this is lean for a single person, which is a common trade-off for retiring this early. Our guide to the best places to retire in Canada compares what it costs to live in different cities and regions.
Is $1 Million Enough to Retire at 50?
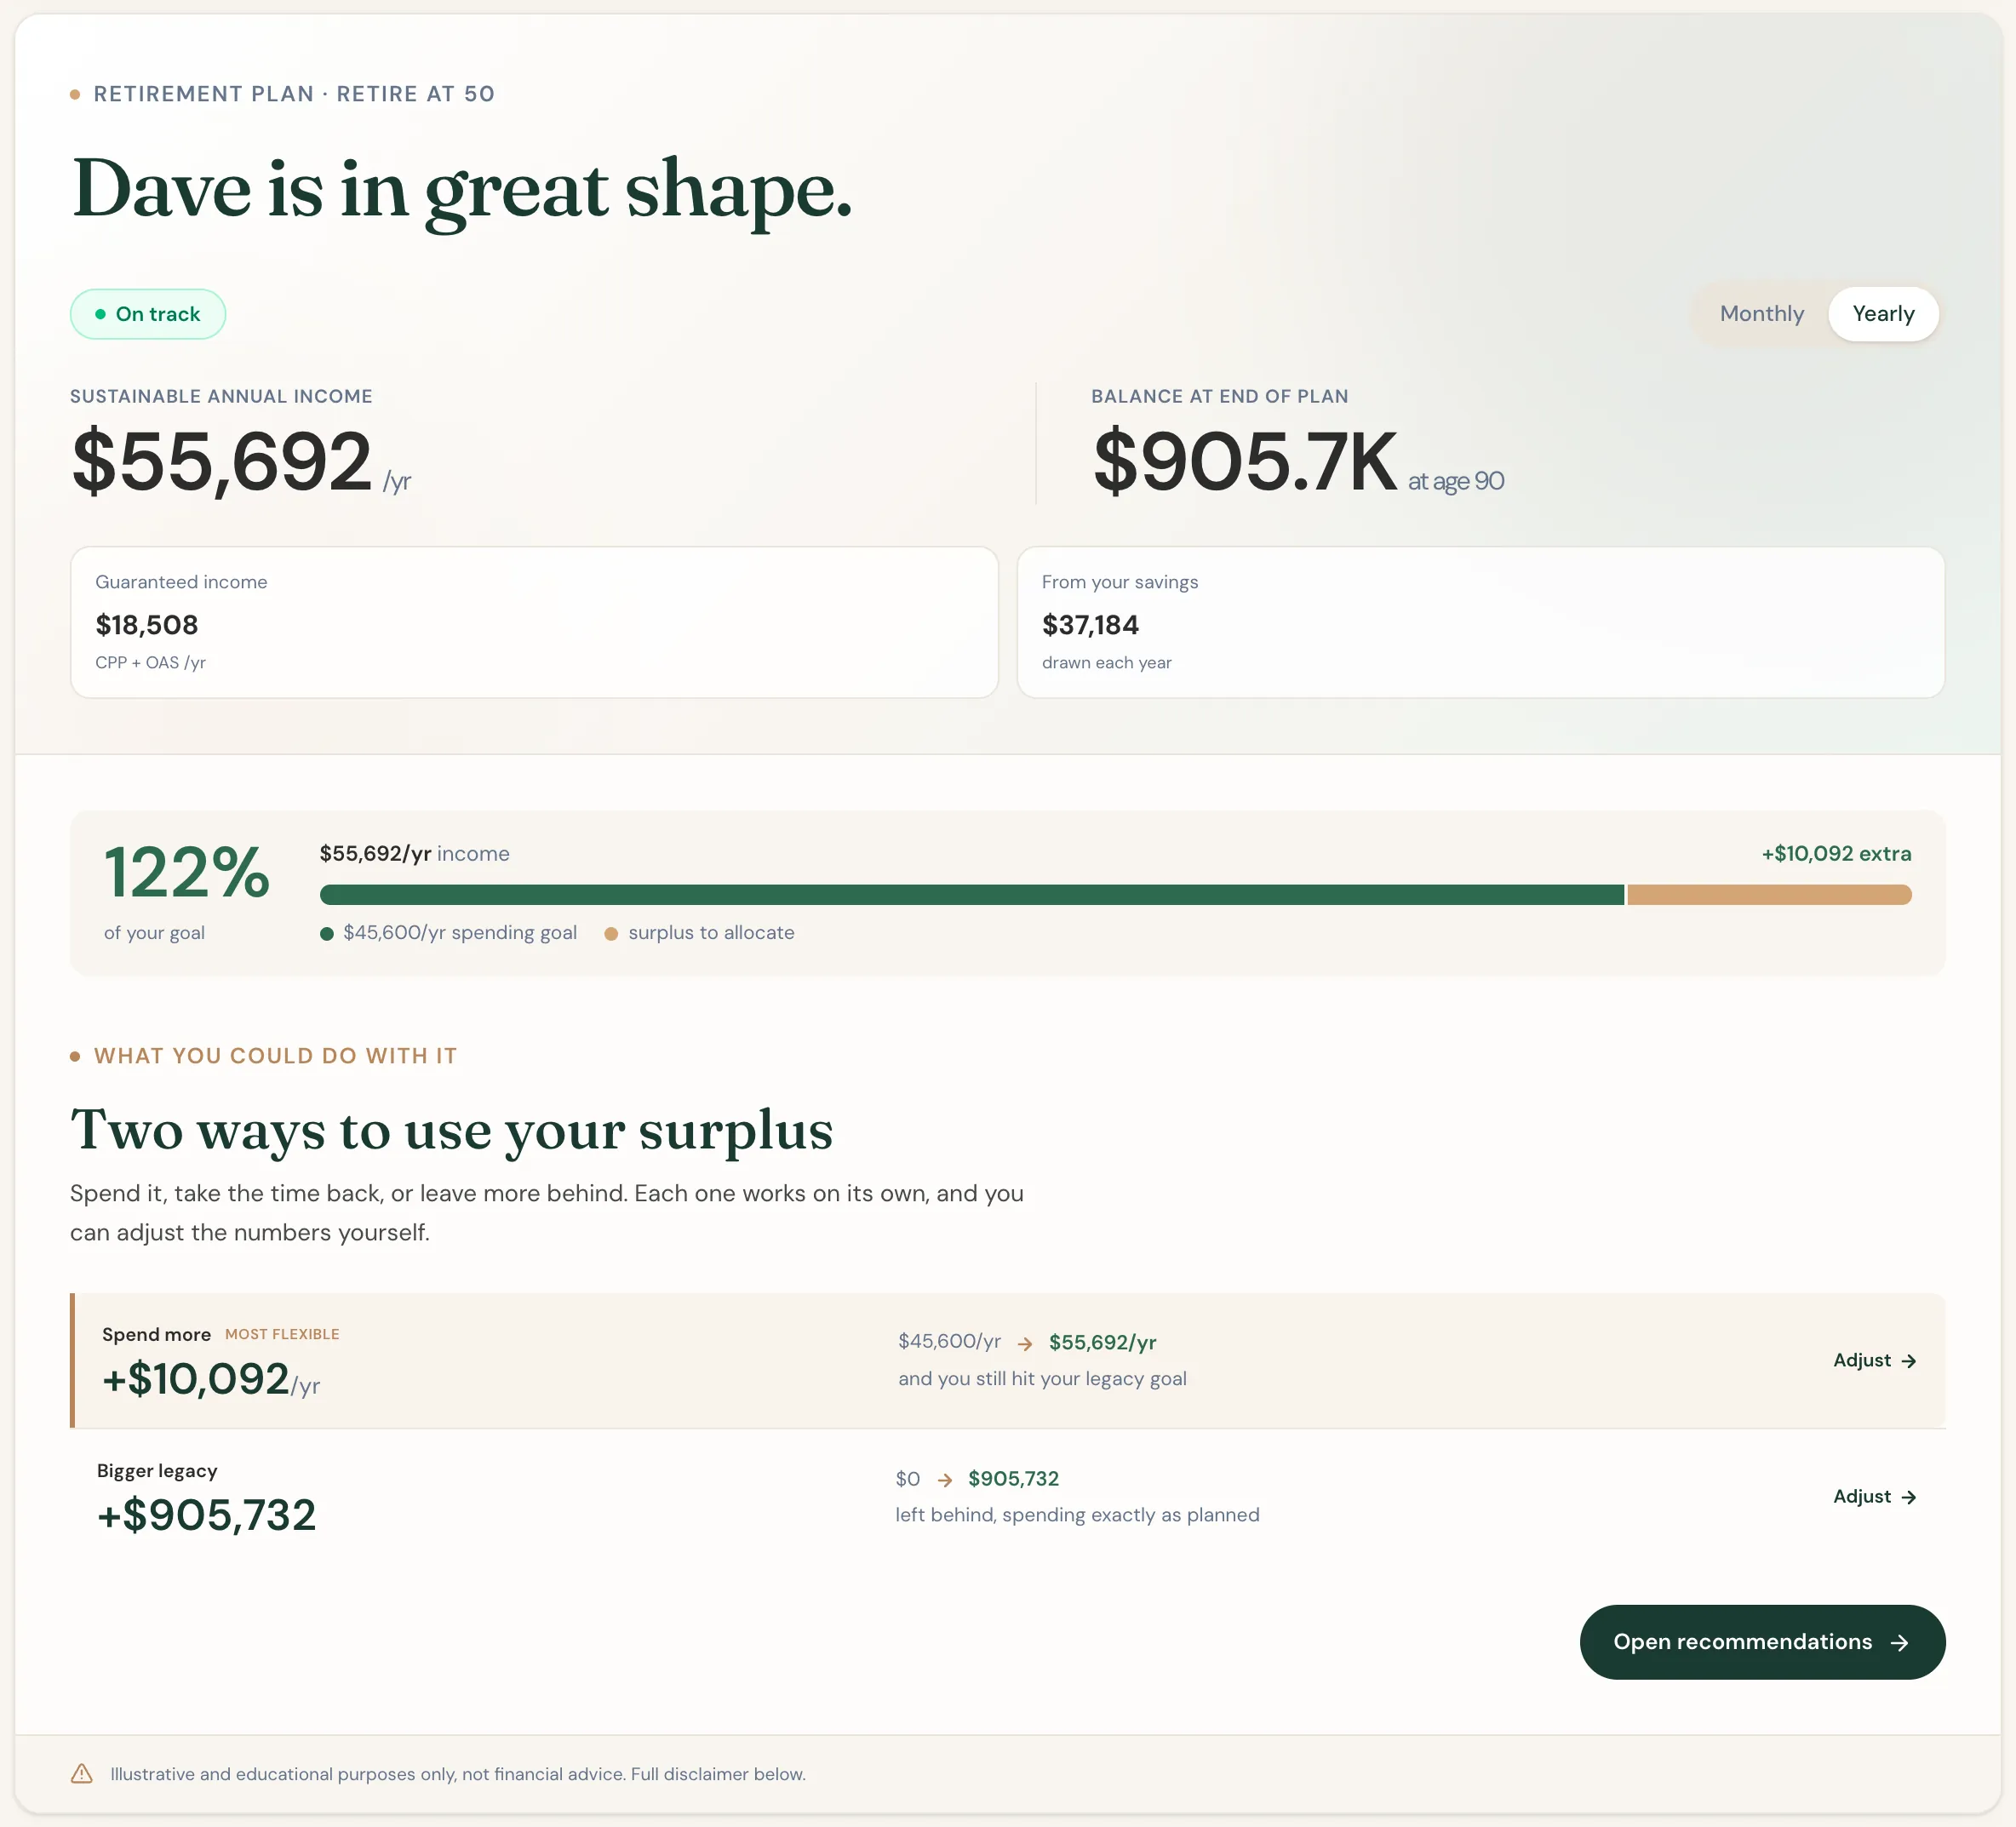 Scenario Lab+'s results for Dave's plan.
For Dave, the results say yes, with a wide margin. His plan covers his spending every year and still has $905,732 left at 90. Scenario Lab+ estimates he could spend about $841 more a month and still make it.
He draws $48,710 from his savings in his first year, about 4.9% of his portfolio, which is above the 4% rule. It works because his spending drops at 60, CPP and OAS take over part of the load at 65, and a 6% growth rate keeps his savings growing once his withdrawals fall.
Bridging the 15 Years to 65
From 50 to 64, everything Dave spends comes from his savings. His portfolio falls from $1 million to about $751,000 at 64, the low point of his whole plan.
At 65 his CPP and OAS start, and together they pay $18,508 a year. From then on he only needs to draw about $22,000 a year from his savings, and his investments earn more than that. His portfolio grows for the rest of his life.
How Much Income Does $1 Million Provide?
In his first year of retirement, Dave draws on three accounts:
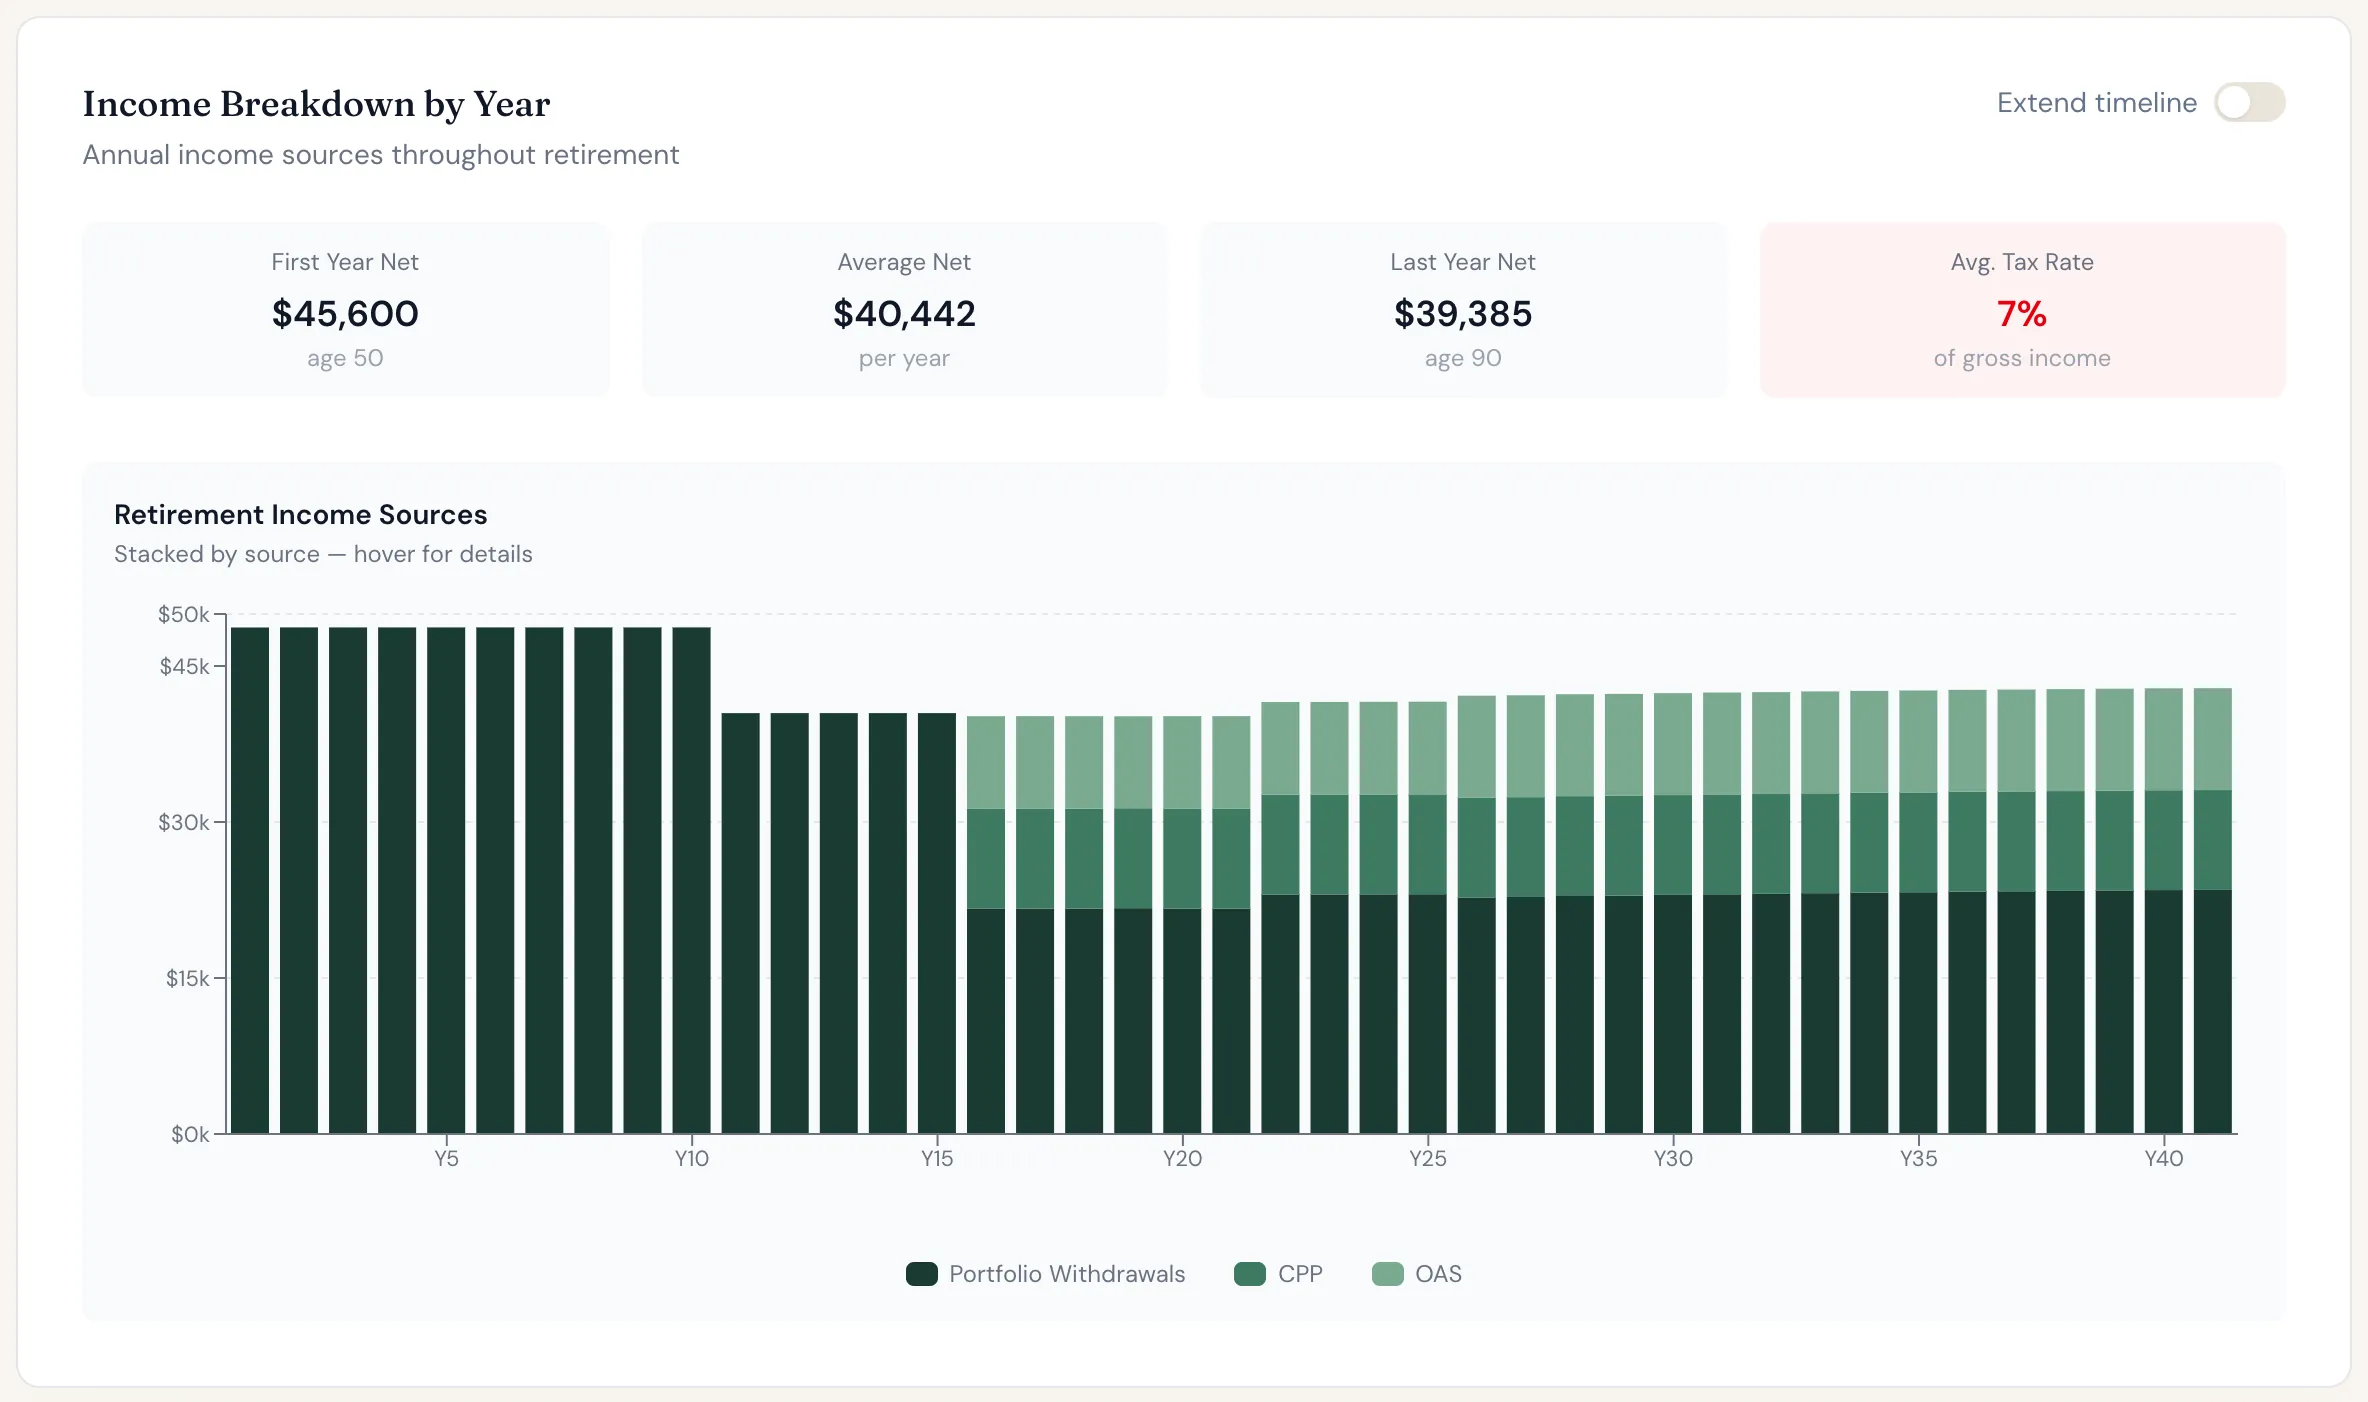 Where Dave's income comes from each year, by source.
| Source | Age 50 | Age 65 | Taxable? |
|---|---|---|---|
| CPP | $0 | $9,600 | Yes |
| OAS | $0 | $8,908 | Yes |
| RRSP withdrawals | $26,790 | $11,917 | Yes |
| TFSA withdrawals | $8,768 | $3,900 | No |
| Non-registered withdrawals | $13,152 | $5,850 | Only the capital gain |
| Gross income | $48,710 | $40,175 | |
| Income tax | $3,110 | $1,775 | |
| Spending money | $45,600 | $38,400 |
Thinking about retiring early?
Scenario Lab+ builds this same year-by-year plan from your own accounts and spending, including the years before CPP and OAS start.
Try Scenario Lab+How Much Tax Dave Pays
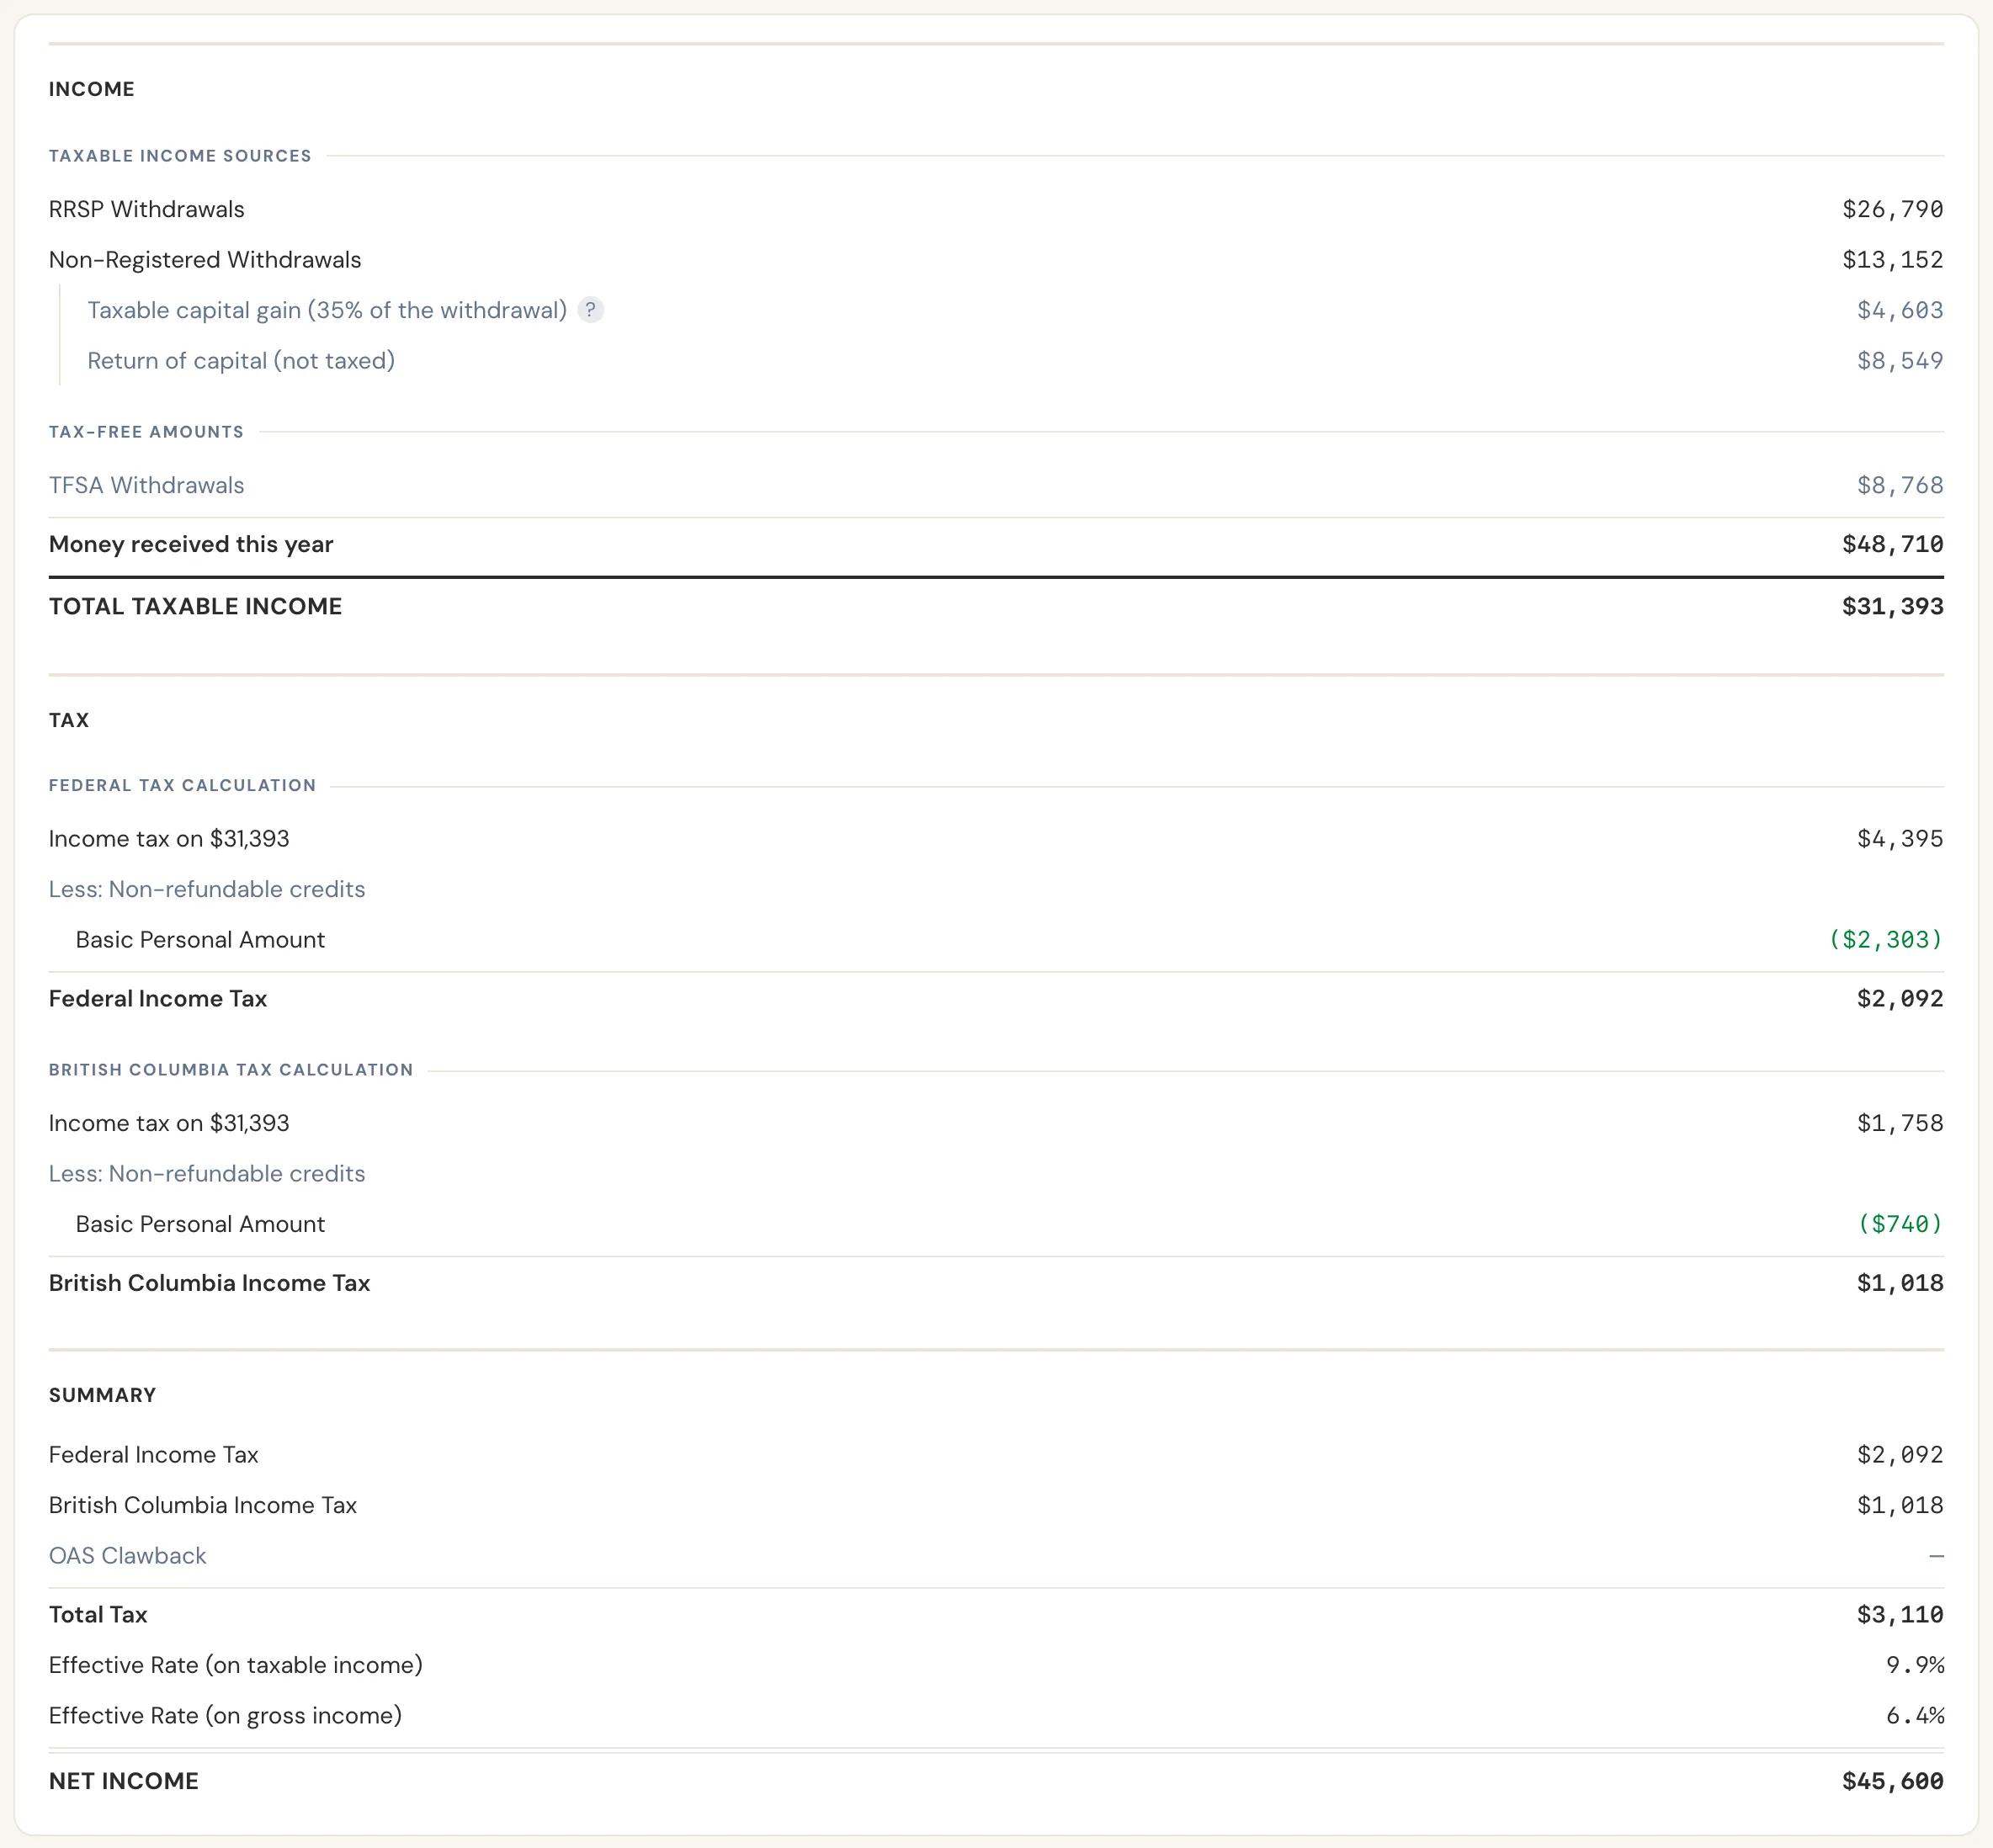 Dave's tax bill in his first year of retirement, at age 50.
Dave pays $3,110 in income tax in his first year, about 6.4% of his income. Over his whole retirement he pays $119,393.
His bill is low because so little of his income is taxable. His TFSA withdrawals are tax-free, only part of each non-registered withdrawal is a capital gain, and the basic personal amount covers the first part of the rest. At 71 his RRSP becomes a RRIF, the minimum withdrawal roughly doubles what he takes from it, and his tax rises to about $3,100 a year again.
How His Plan Changes Over Time
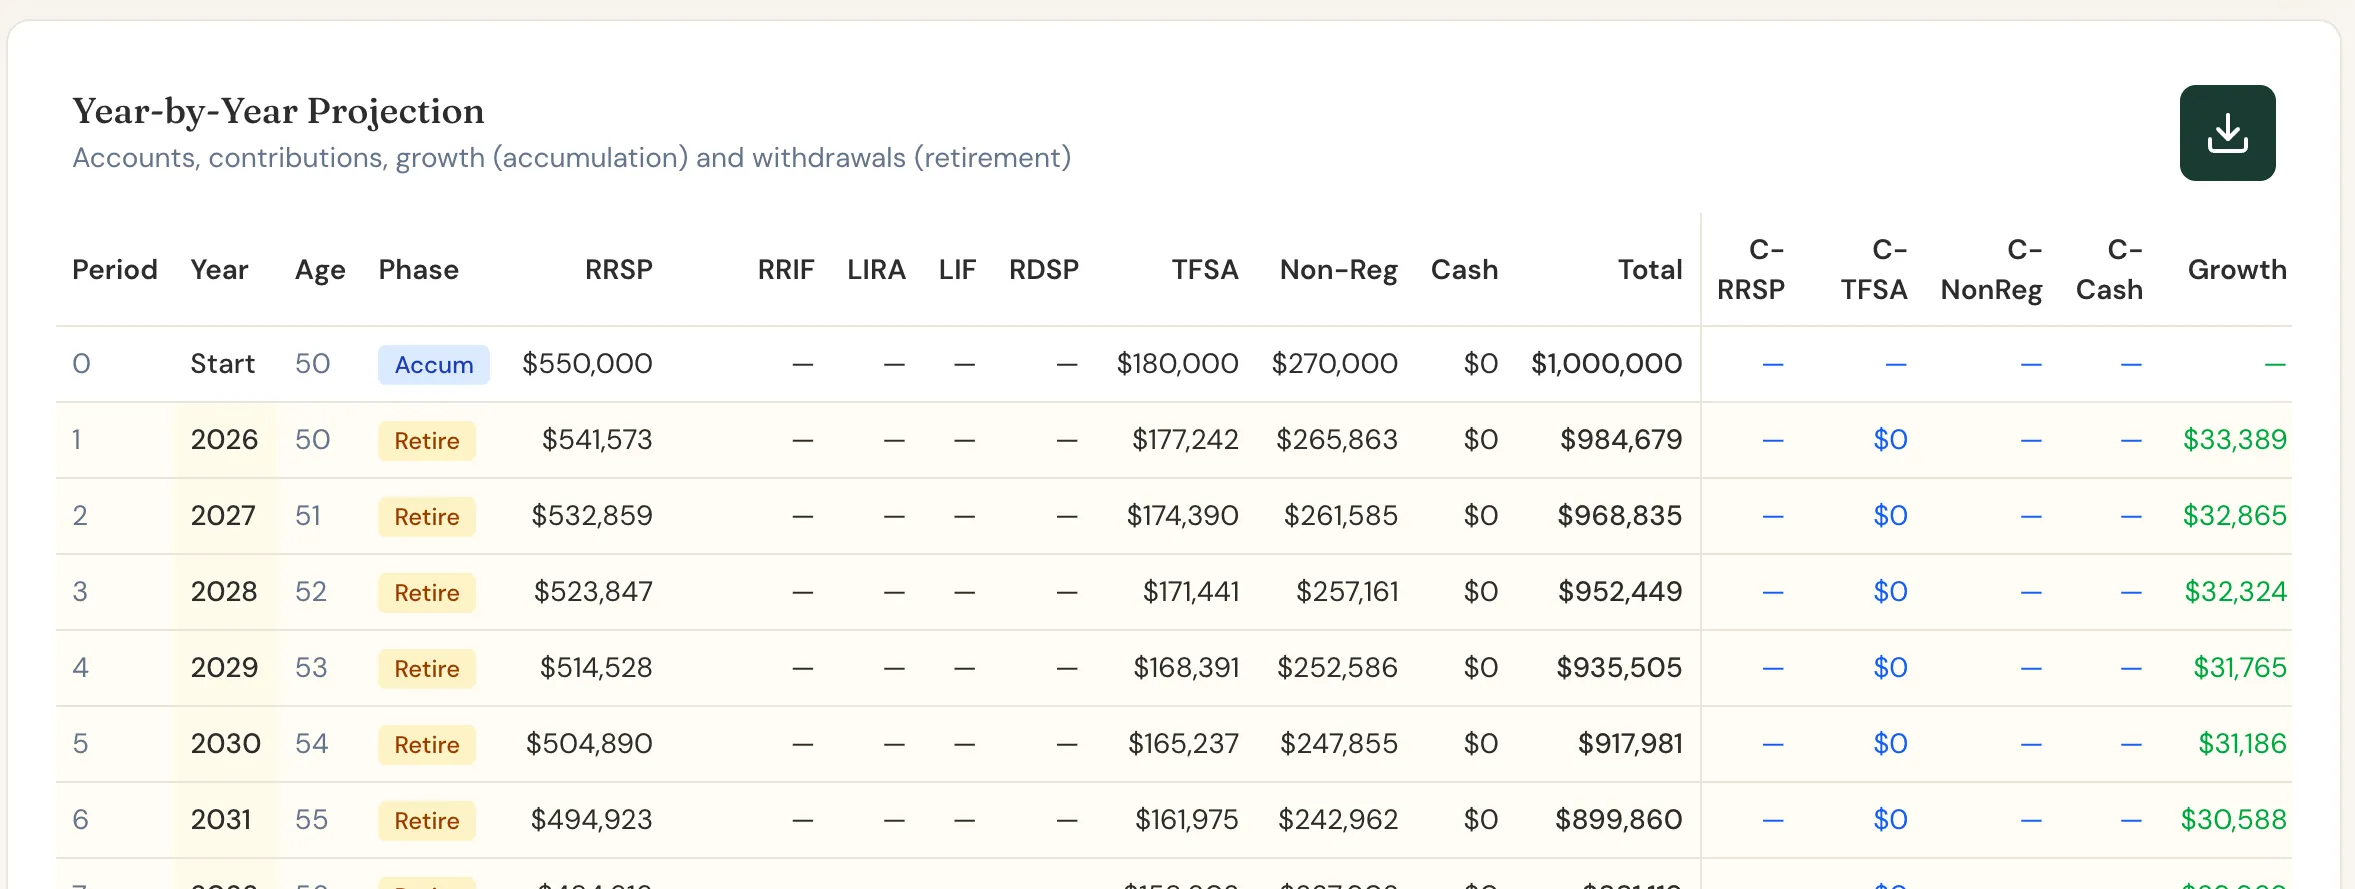 Year-by-year account balances from 50.
At 60, his spending steps down. His travel years end and his budget falls to $3,200 a month.
At 65, CPP and OAS start. His withdrawals from savings fall by almost half.
At 71, his RRSP becomes a RRIF. The minimum withdrawal is more than he needs, so the extra goes back into his TFSA and non-registered account. Our RRIF guide covers the rules.
At 90, he still has $905,732. That's $179,783 in his RRIF, $318,453 in his TFSA, and $407,496 in his non-registered account.
Based on his numbers, Scenario Lab+ estimates Dave could spend about $841 more every month and still make it to 90.
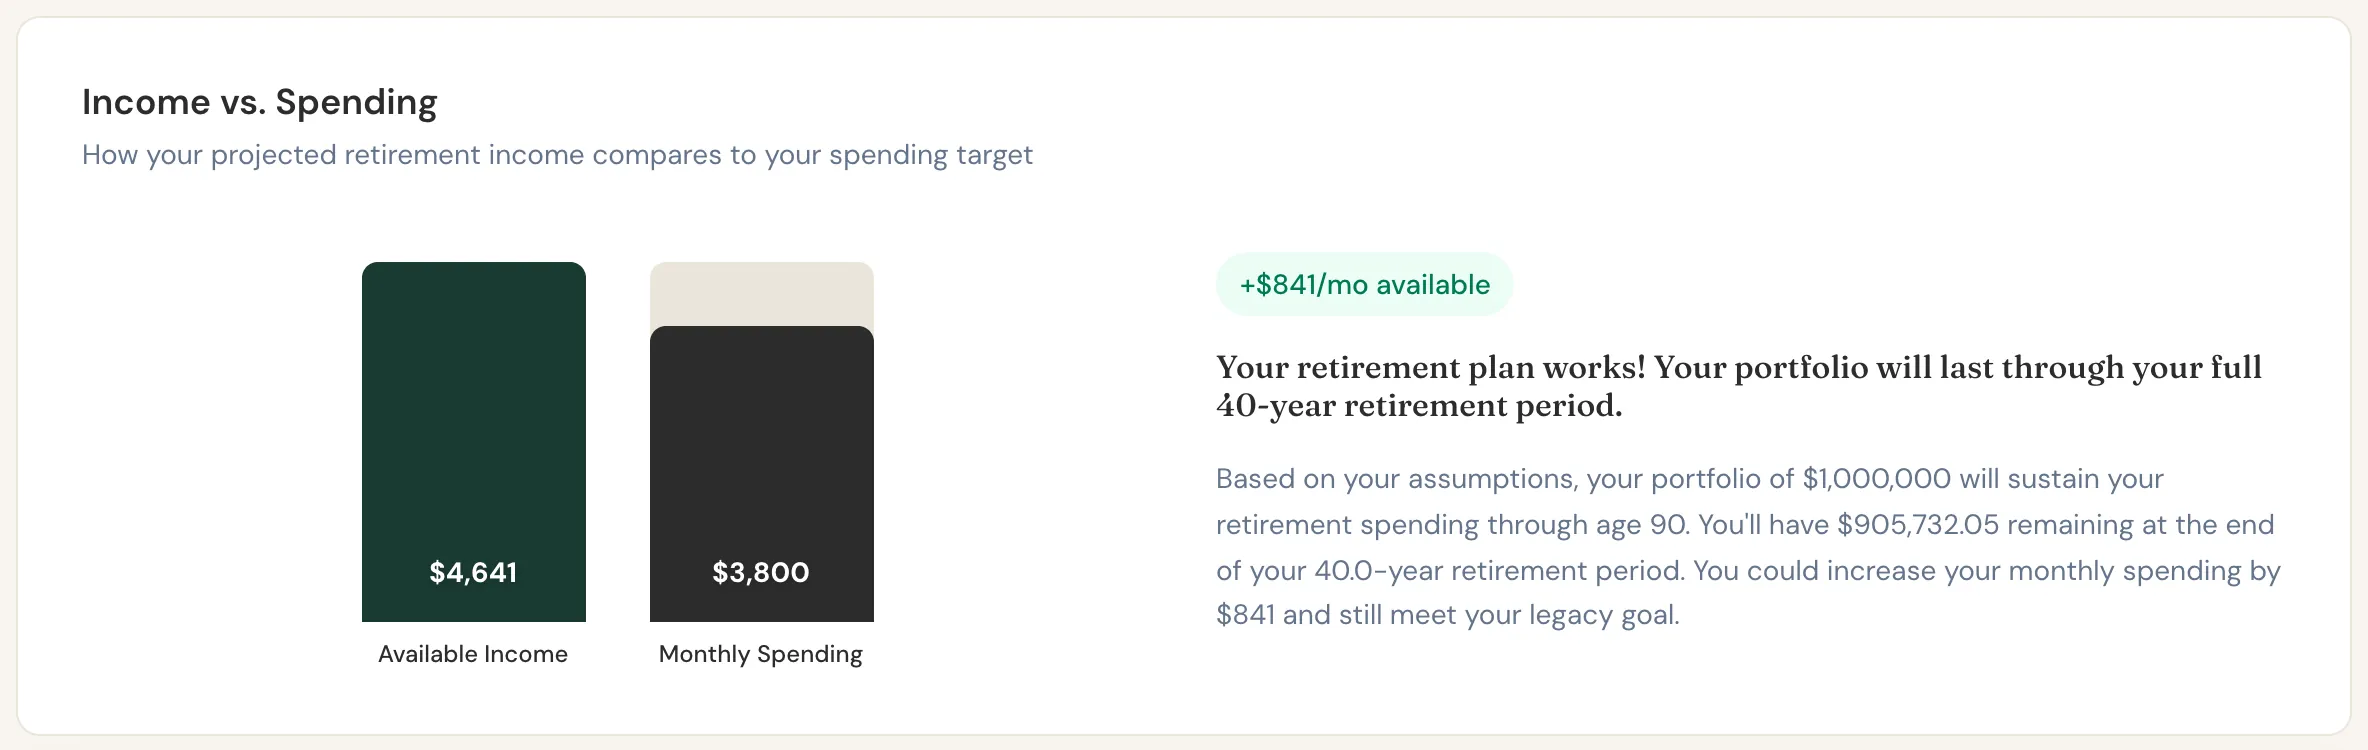 Income available to Dave compared with what he plans to spend.
But What If We Change the Assumptions?
Dave's plan has room to spare, so we looked at the choices an early retiree actually faces, changing one assumption at a time.
4 versions of Dave's plan
One assumption changed in each. Charts show the portfolio from 50 to 90 in Scenario Lab+.
Dave's base plan
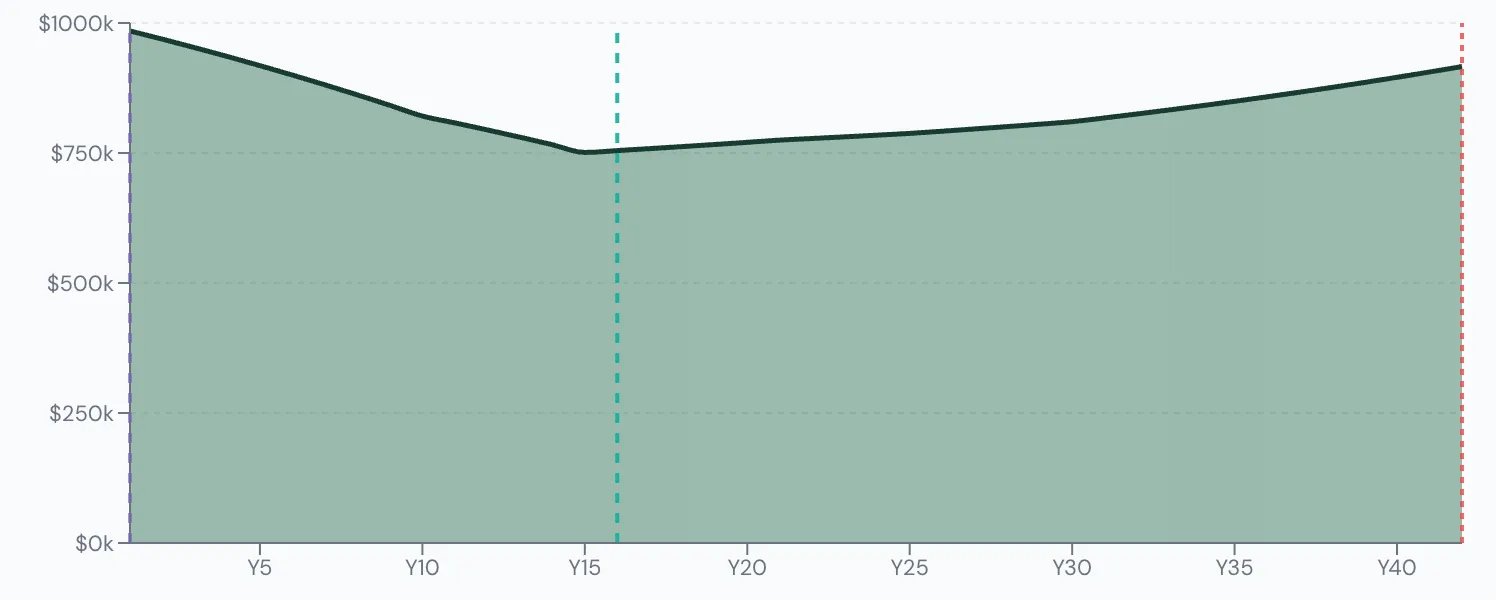
- Spends at 50
- $45,600/yr
- Money lasts
- Past 90
- Left at 90
- $905,732
Draws a steady taxable income
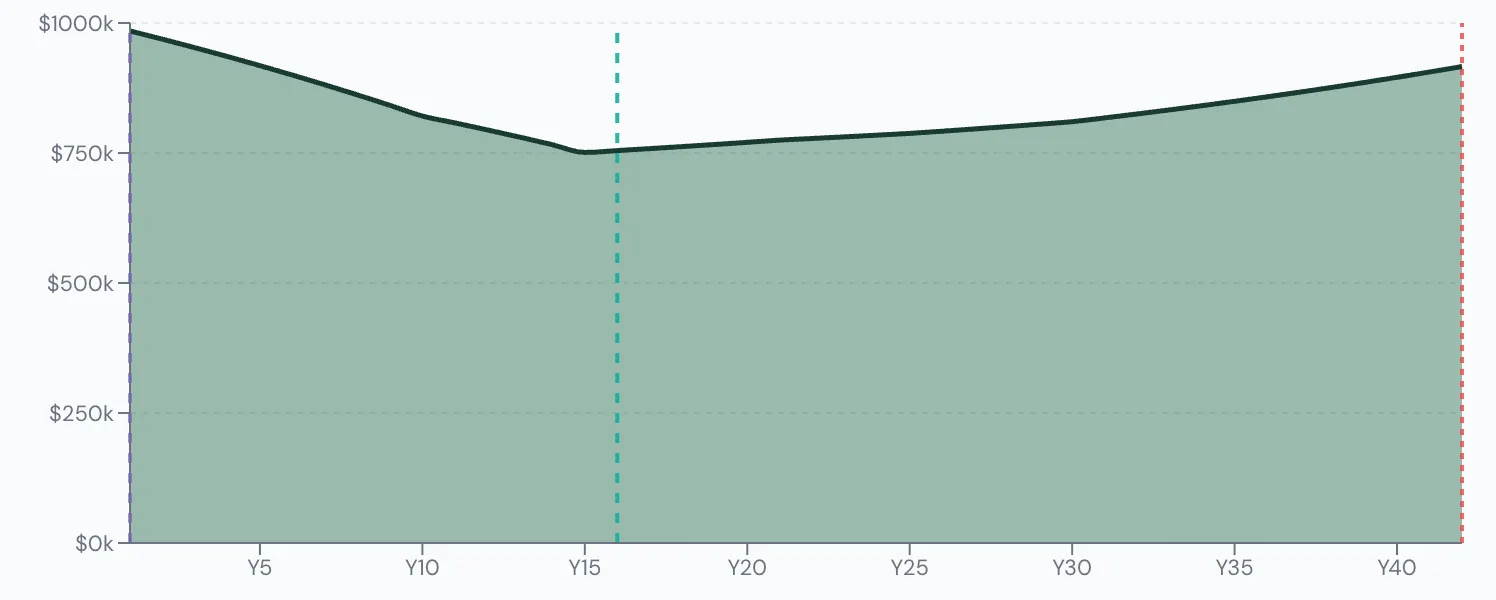
- Spends at 50
- $45,600/yr
- Money lasts
- Past 90
- Left at 90
- $838,147
Delays CPP to 70
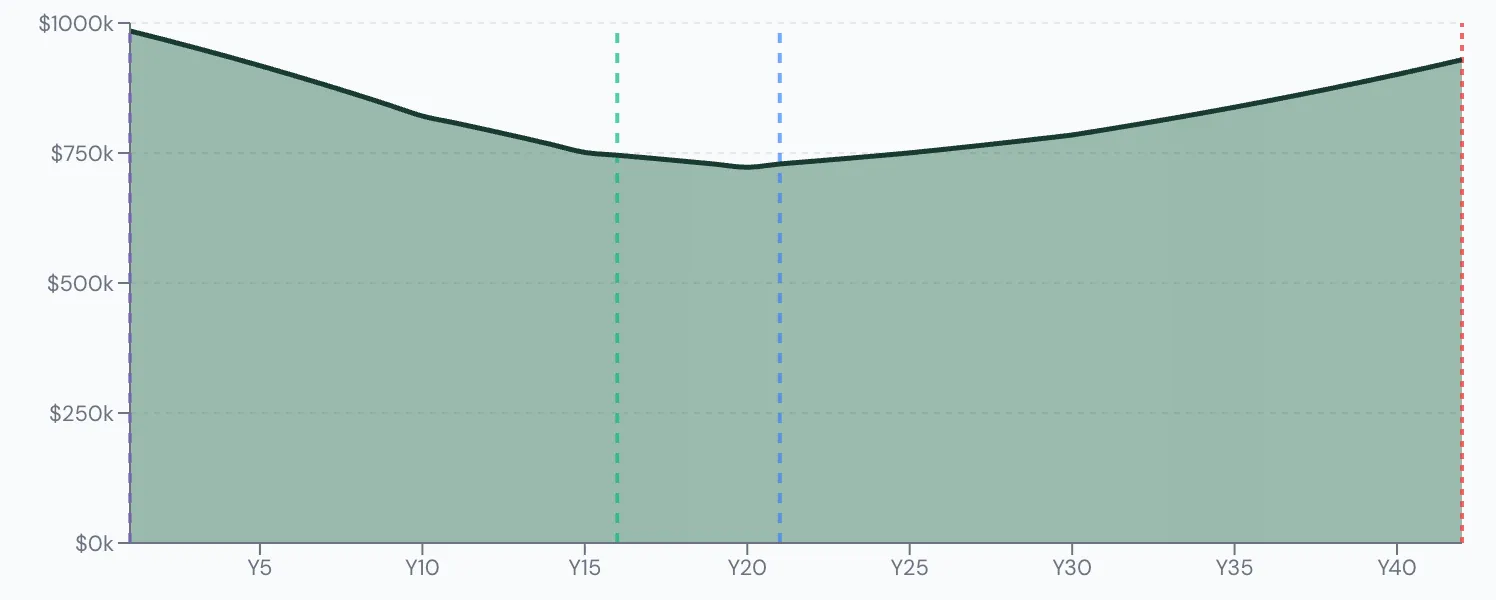
- Spends at 50
- $45,600/yr
- Money lasts
- Past 90
- Left at 90
- $914,950
Keeps travelling until 75
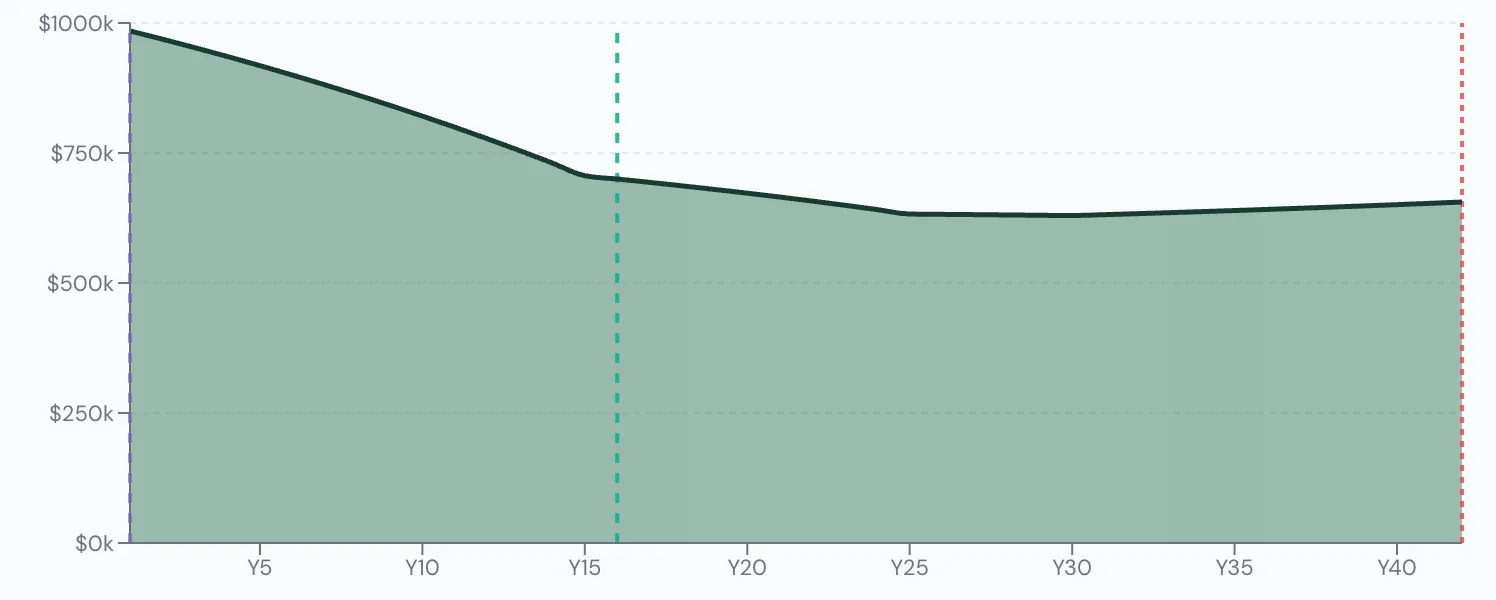
- Spends at 50
- $45,600/yr
- Money lasts
- Past 90
- Left at 90
- $653,177
Scenario 1
Draws a steady taxable income
- Spends at 50
- $45,600/yr
- Money lasts
- Past 90
- Left at 90
- $838,147
From 50 to 64 Dave's taxable income is low, because he has no salary, CPP, or OAS. What if he uses those years to draw down his RRSP on purpose, at a steady taxable income, instead of drawing from every account in proportion? Scenario Lab+ runs this as its Tax Bracket Smoothing strategy, with a target he sets.
At a target of about $55,000 of taxable income, he takes $53,000 a year from his RRSP and nothing from his other accounts. His tax in those years rises to $7,400. His RRSP is empty by 63, and from then on his income is CPP, OAS, and non-registered withdrawals, and he pays almost no tax at all: $432 at 65.
Over his whole retirement he pays $104,117 in tax, about $15,000 less than his original plan. He finishes at 90 with $838,147, about $68,000 less, but none of it is in an RRSP or RRIF. His original plan still has $179,783 in his RRIF at 90, which is taxable when it comes out or when he dies, so the real gap is smaller than it looks.
The Drawdown tab compares four strategies for the same plan:
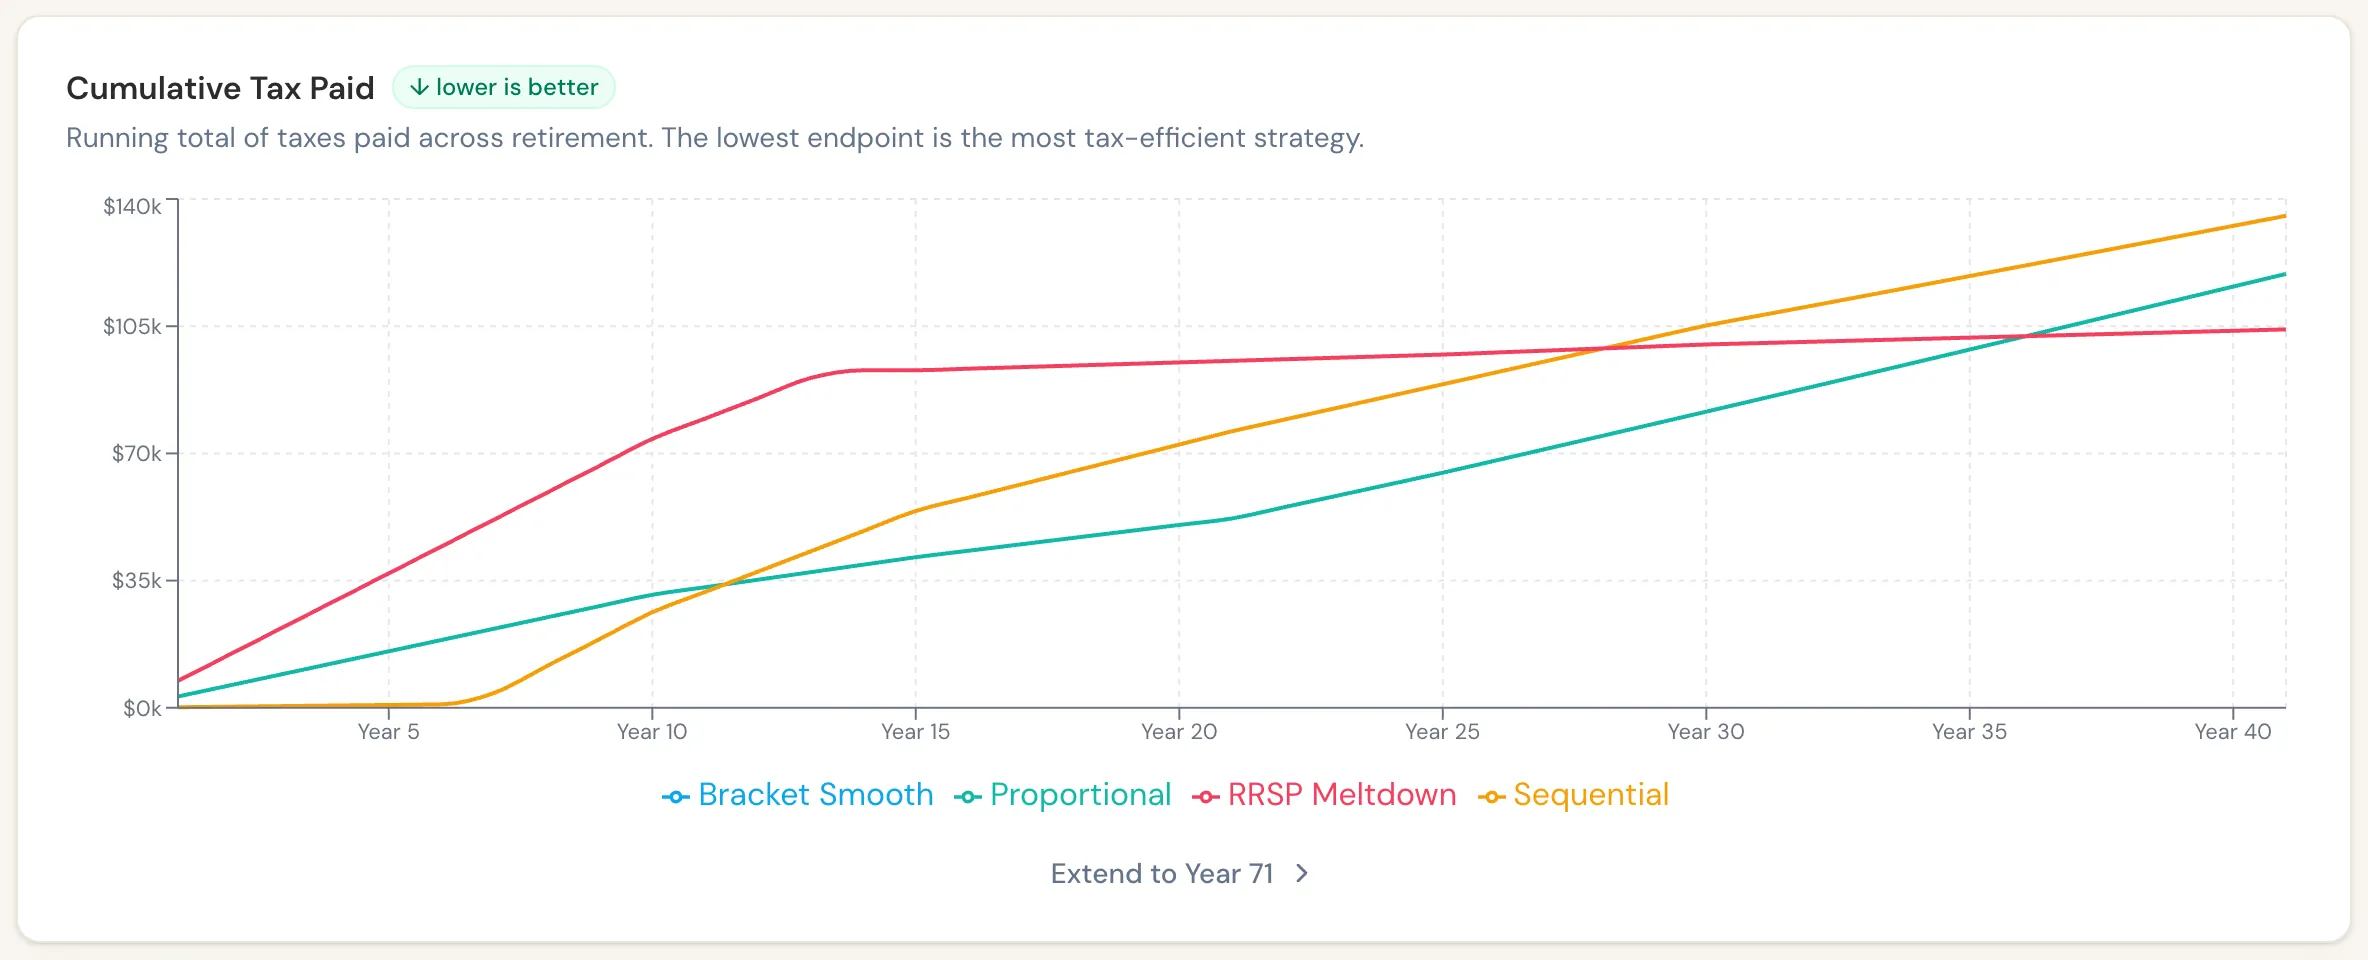 Cumulative tax under each drawdown strategy in the Drawdown tab.
Scenario 2
Delays CPP to 70
- Spends at 50
- $45,600/yr
- Money lasts
- Past 90
- Left at 90
- $914,950
CPP rises 42% if you start at 70 instead of 65. With 15 years of savings behind him, what if Dave waits?
He'd receive $13,632 a year instead of $9,600. He draws a little more from his savings from 65 to 69 to cover the gap, and finishes at 90 with $914,950, about $9,000 more. He pays about $7,600 more tax over his retirement, because more of his income is now CPP.
For Dave, at a planning age of 90, the two choices come out close. Delaying CPP is a bet on living a long time. Our CPP and OAS break-even calculator shows where that line falls for you.
Scenario 3
Keeps travelling until 75
- Spends at 50
- $45,600/yr
- Money lasts
- Past 90
- Left at 90
- $653,177
Dave planned to slow his travel at 60. What if he keeps his $3,800 budget until 75, as many retirees do?
His plan still works. He finishes at 90 with $653,177, about $250,000 less than his original plan, and Scenario Lab+ estimates he would still have about $547 a month of room. For someone who retired at 50 to travel, fifteen more years of it is a reasonable use of the margin.
Your $1 Million Is Not Dave's $1 Million
So can you retire at 50 with $1 million? Dave can, on a lean budget with room to spare. But his plan is a starting point, not an answer for anyone else.
Retiring at 50 depends heavily on what you spend, because every dollar of it comes from your savings for 15 years. A budget $1,000 a month higher, or a smaller CPP, can change the answer. For the same savings at 55, see Nicole's plan. For $1 million at 60, see Michael's plan.
The bigger risk for an early retiree is not knowing how long the bridge to 65 can safely run.
That's why we built Scenario Lab+.
It is the software behind every number in this article. Give it your own accounts and spending, and it builds the same year-by-year plan for you, including every what-if above. If you'd like to see it first, Dave's full plan is open to explore.
Build Your Own Canadian Retirement Plan
Enter your own savings, benefits, and spending in Scenario Lab+ to see whether your number is enough and what happens when your assumptions change.
Start now