

The short answer
- Yes: $3 million at 60 supports $9,000 a month after tax for Arjun, with $2.5M left at 90.
- Scenario Lab+ estimates he could spend about $3,525 more a month, though spending that much costs him about $10,000 of OAS to the clawback.
- He could spend $11,158 a month and still leave his kids about $1.17 million.
Estimates from Scenario Lab+, in today's dollars.
See the demo planAt $3 million, running out of money is rarely the real risk. The questions become how much you can actually enjoy, and how much to give your family while you're around to see it. Most people with this much saved spend less than they could.
Here at Loonie Nest, our mission is to provide free and affordable personal finance education to Canadians so they can gain confidence in their retirement.
Arjun's plan at a glance
$3,000,000
saved at 60
RRSP
$1,100,000
Taxed as income when withdrawn
TFSA
$200,000
Withdrawals are tax-free
Non-registered
$1,700,000
Only the capital gain is taxed
Spending after tax, in today's dollars
$108,000
$97,200
$86,400
CPP $1,350 a month from 65
OAS $742 a month from 65
Our $3 Million Retirement Scenario
Let's meet Arjun. He's 60, single, and living in Toronto, ON. He built and ran a small engineering consulting firm, and sold it two years ago. The proceeds are invested in a non-registered account, beside the RRSP he contributed to for most of his career. He has two adult children, and he wants to know how much he can spend, and how much he can help them now.
We'll run Arjun's numbers through Scenario Lab+.
Scenario Lab+ is our proprietary retirement planning software. We'll use it to generate and review a tailored retirement plan for him.
To start, here's how Arjun's numbers look as he retires at 60:
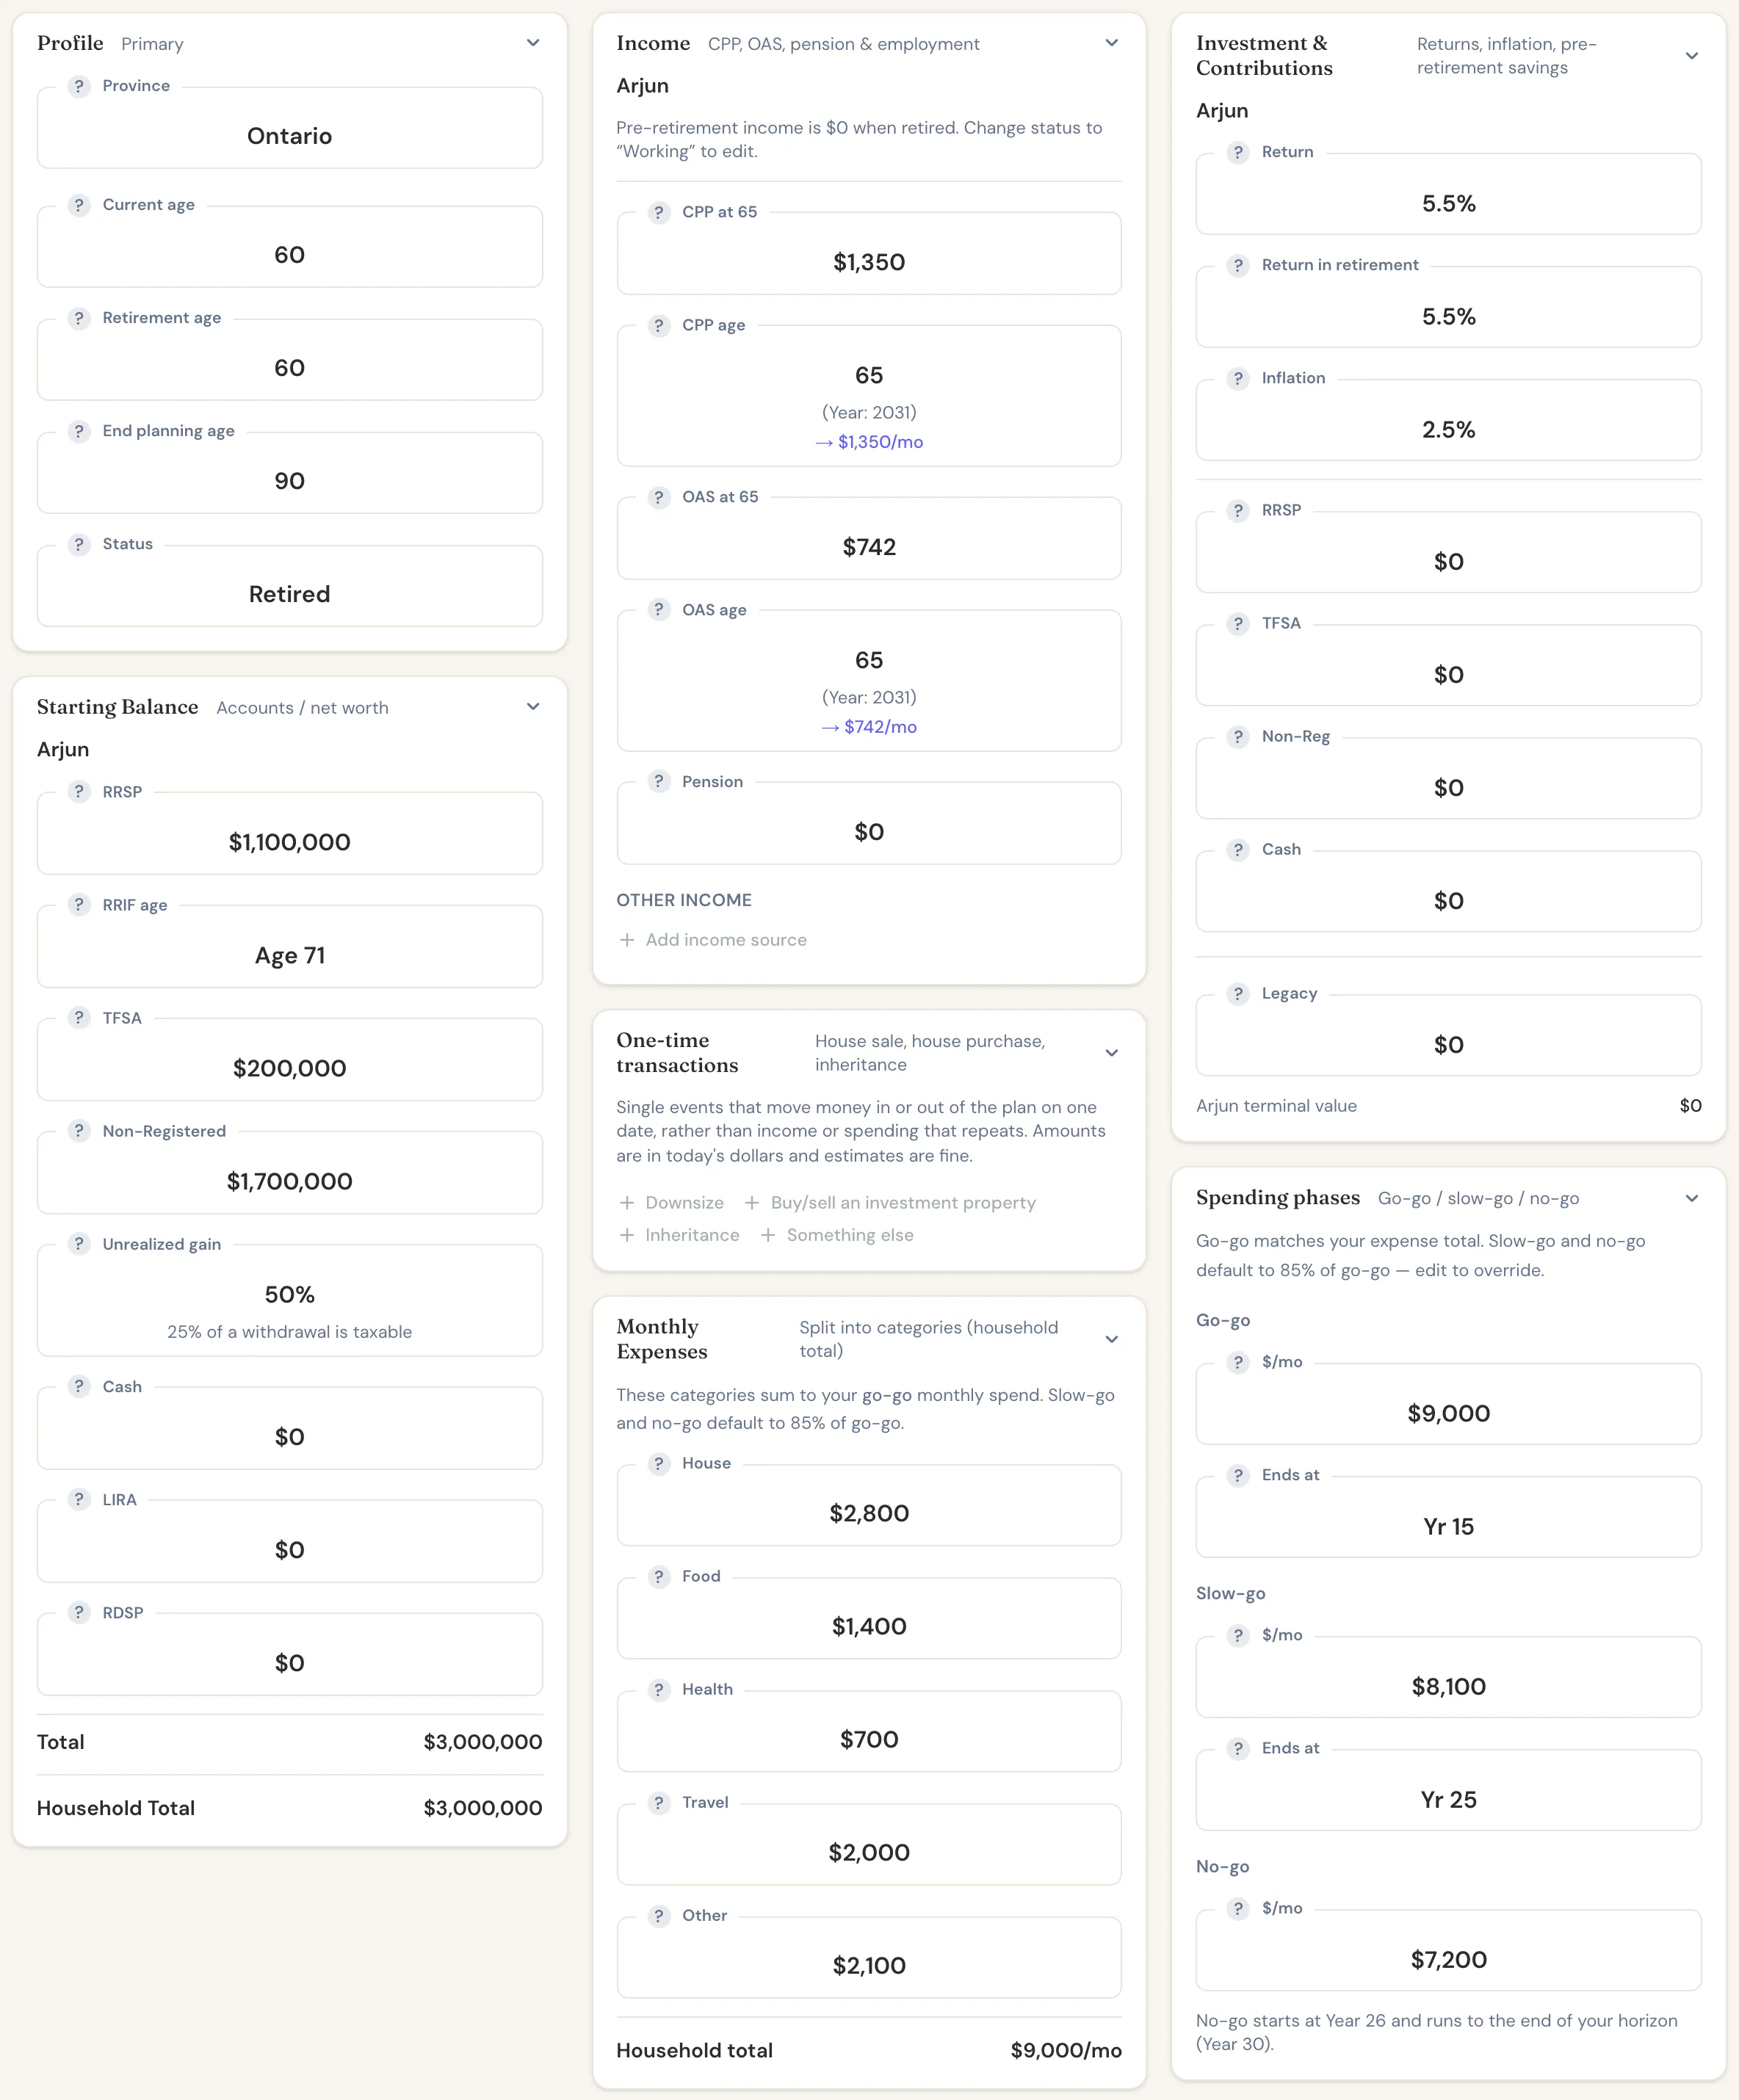 Arjun's plan inputs: his profile, account balances, CPP and OAS, and monthly spending.
Most of his money is in a non-registered account. He has $1.7 million there, $1.1 million in his RRSP, and $200,000 in his TFSA. About half of the non-registered balance is investment growth since the sale, which Scenario Lab+ takes as an input, so it can tax his withdrawals correctly.
Arjun's CPP is $1,350 a month at 65. He paid both halves of CPP as a business owner, at a high income, for most of his career. He gets the full OAS at 65. If you want a refresher on how both programs work, see our guide to CPP and OAS.
His spending falls as he ages. His plan starts at $9,000 a month and steps down at 75 and again at 85. In Scenario Lab+, these steps are the plan's Spending Phases.
A few other important assumptions: all figures are in today's dollars, Arjun owns his home with no mortgage, he expects his investments to grow 5.5% a year, inflation runs at 2.5% a year, and we plan his retirement to age 90.
Arjun's retirement budget
Here is how his $9,000 a month breaks down until he turns 75:
| Category | Monthly | Annual |
|---|---|---|
| Housing (property tax, utilities, insurance, upkeep) | $2,800 | $33,600 |
| Food and dining | $1,400 | $16,800 |
| Health and dental | $700 | $8,400 |
| Travel | $2,000 | $24,000 |
| Everything else (car, gifts, entertainment) | $2,100 | $25,200 |
| Total | $9,000 | $108,000 |
Is $3 Million Enough to Retire at 60?
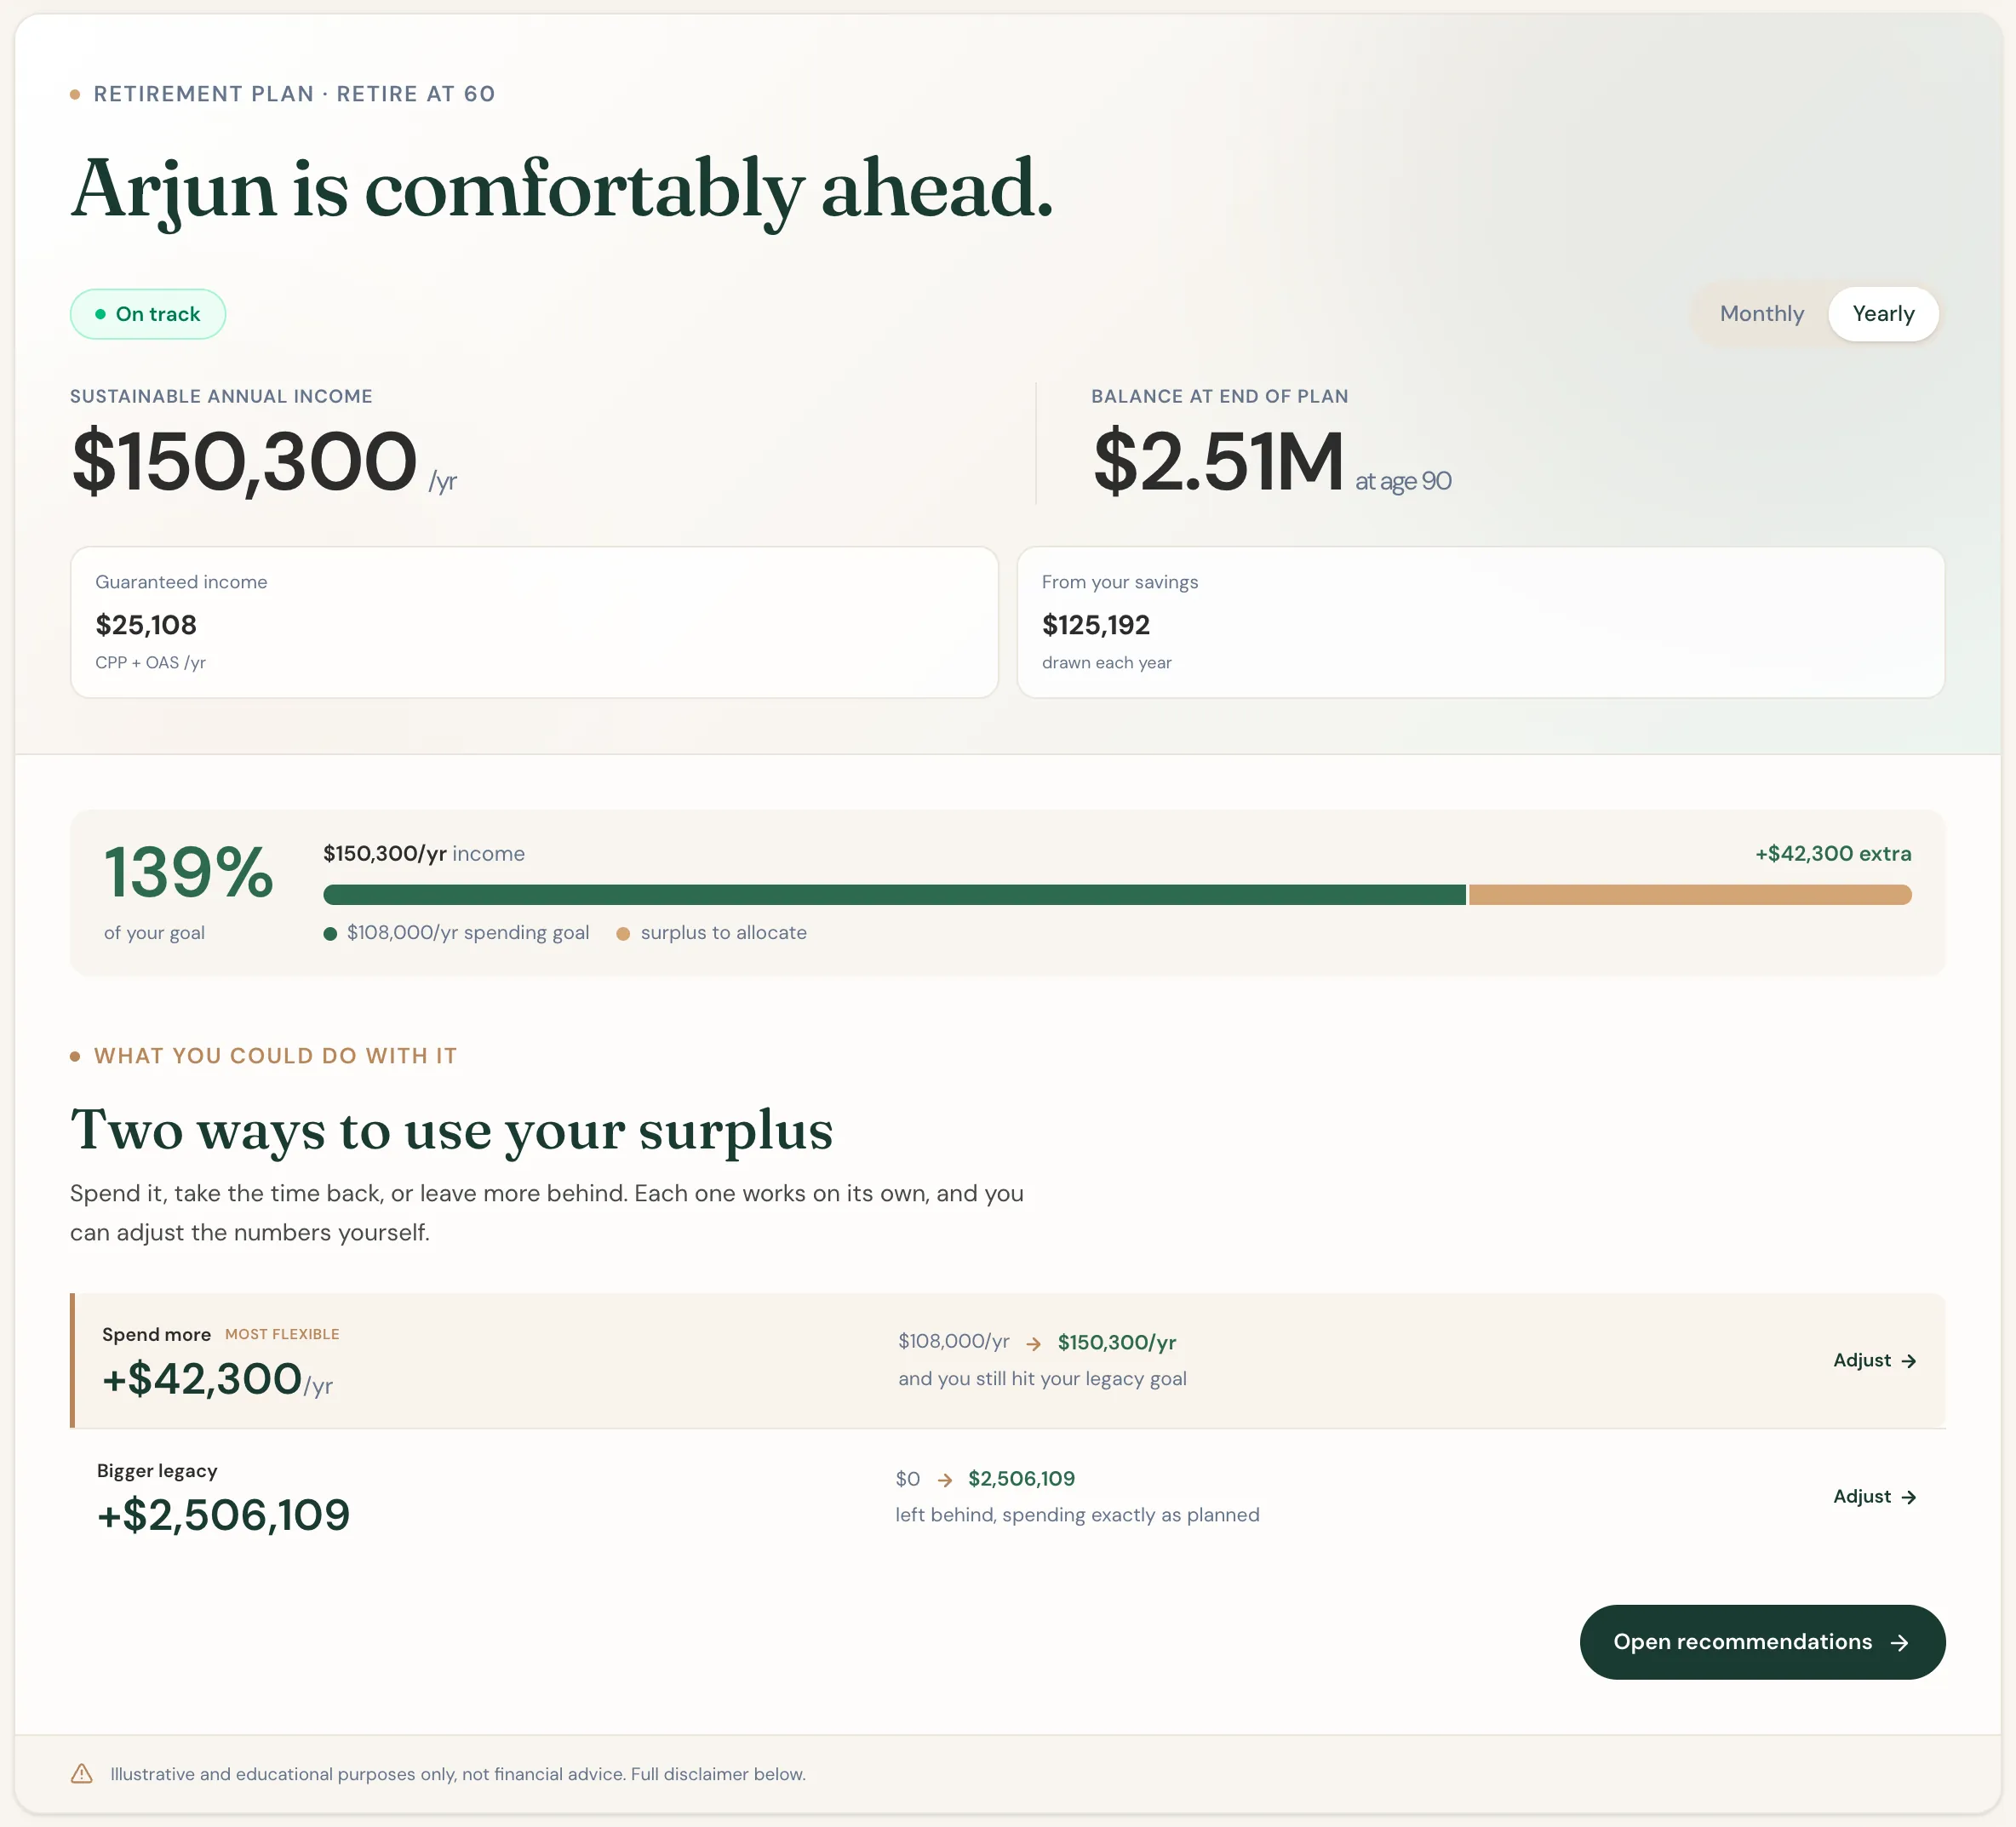 Scenario Lab+'s results for Arjun's plan.
For Arjun, the results say yes, by a very wide margin. His plan covers his spending every year and he still has $2,506,109 at 90, close to what he started with. Scenario Lab+ estimates he could spend about $3,525 more a month and still make it.
He draws $117,329 from his savings in his first year, about 3.9% of his portfolio, and from 65 his CPP and OAS reduce what he needs to draw.
How Much Income Does $3 Million Provide?
In his first year of retirement, Arjun draws $117,329 of gross income to spend $108,000:
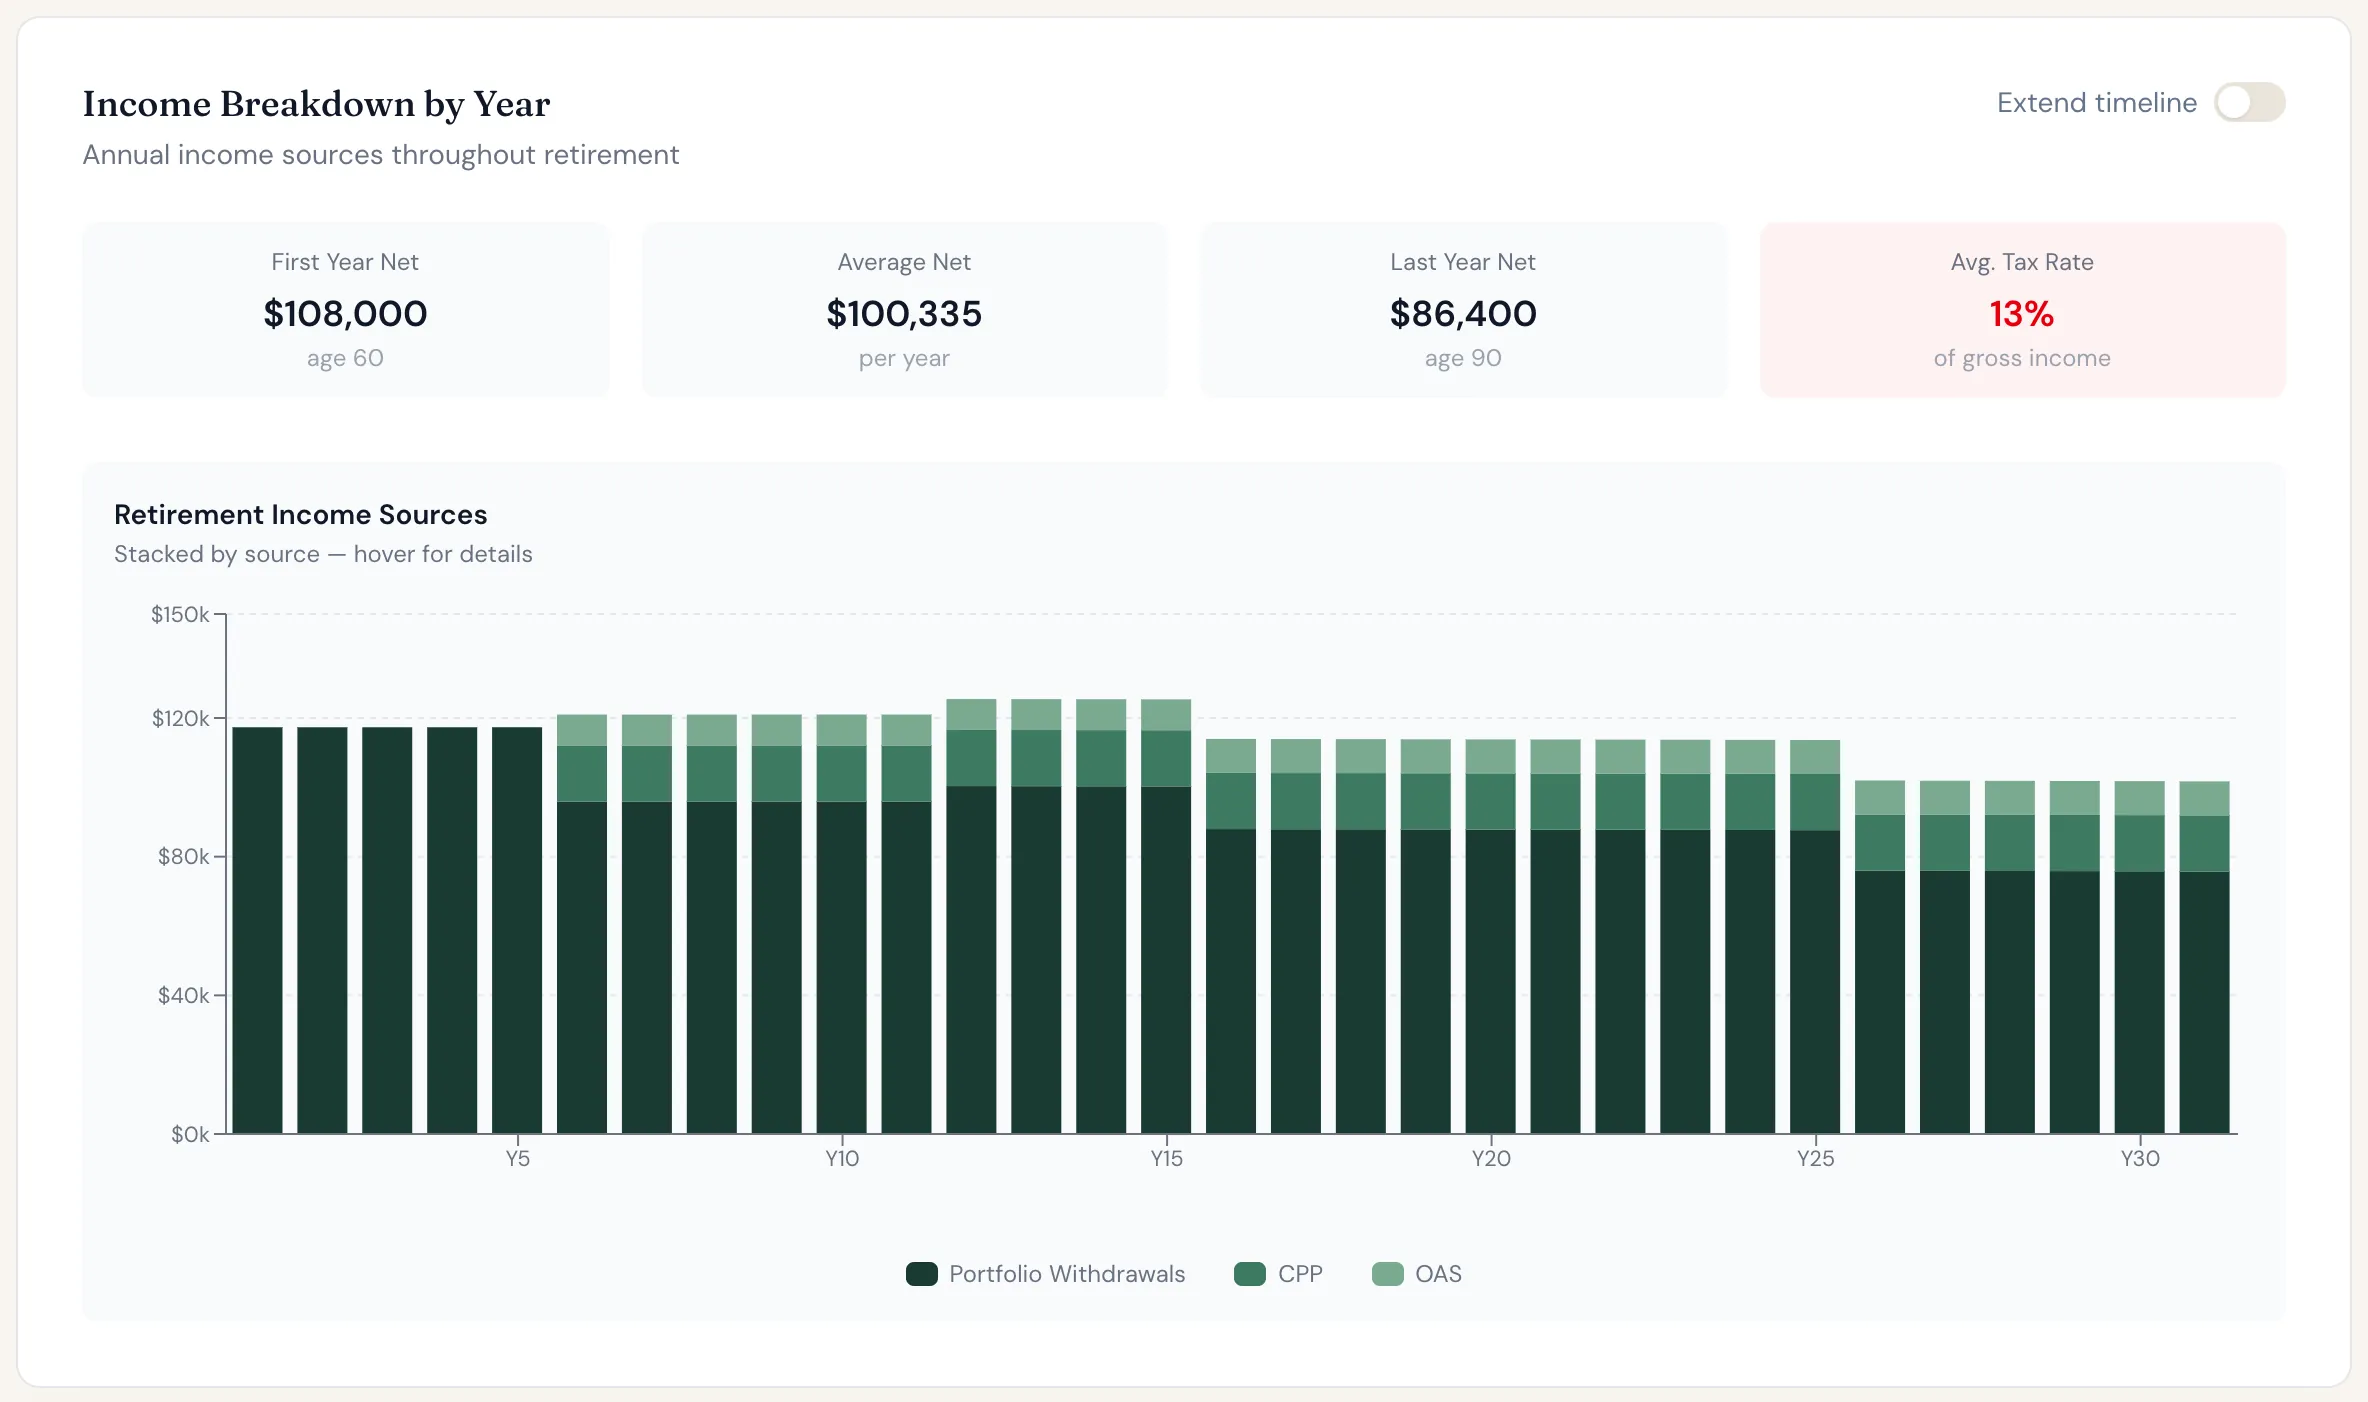 Where Arjun's income comes from each year, by source.
| Source | Age 60 | Age 65 | Taxable? |
|---|---|---|---|
| CPP | $0 | $16,200 | Yes |
| OAS | $0 | $8,908 | Yes |
| RRSP withdrawals | $43,021 | $35,158 | Yes |
| TFSA withdrawals | $7,822 | $6,392 | No |
| Non-registered withdrawals | $66,486 | $54,335 | Only the capital gain |
| Gross income | $117,329 | $120,993 | |
| Income tax | $9,329 | $12,993 | |
| Spending money | $108,000 | $108,000 |
How much could you spend?
Scenario Lab+ finds the most you can spend each month and still make your money last, or still leave the amount you choose.
Try Scenario Lab+How Much Tax Arjun Pays
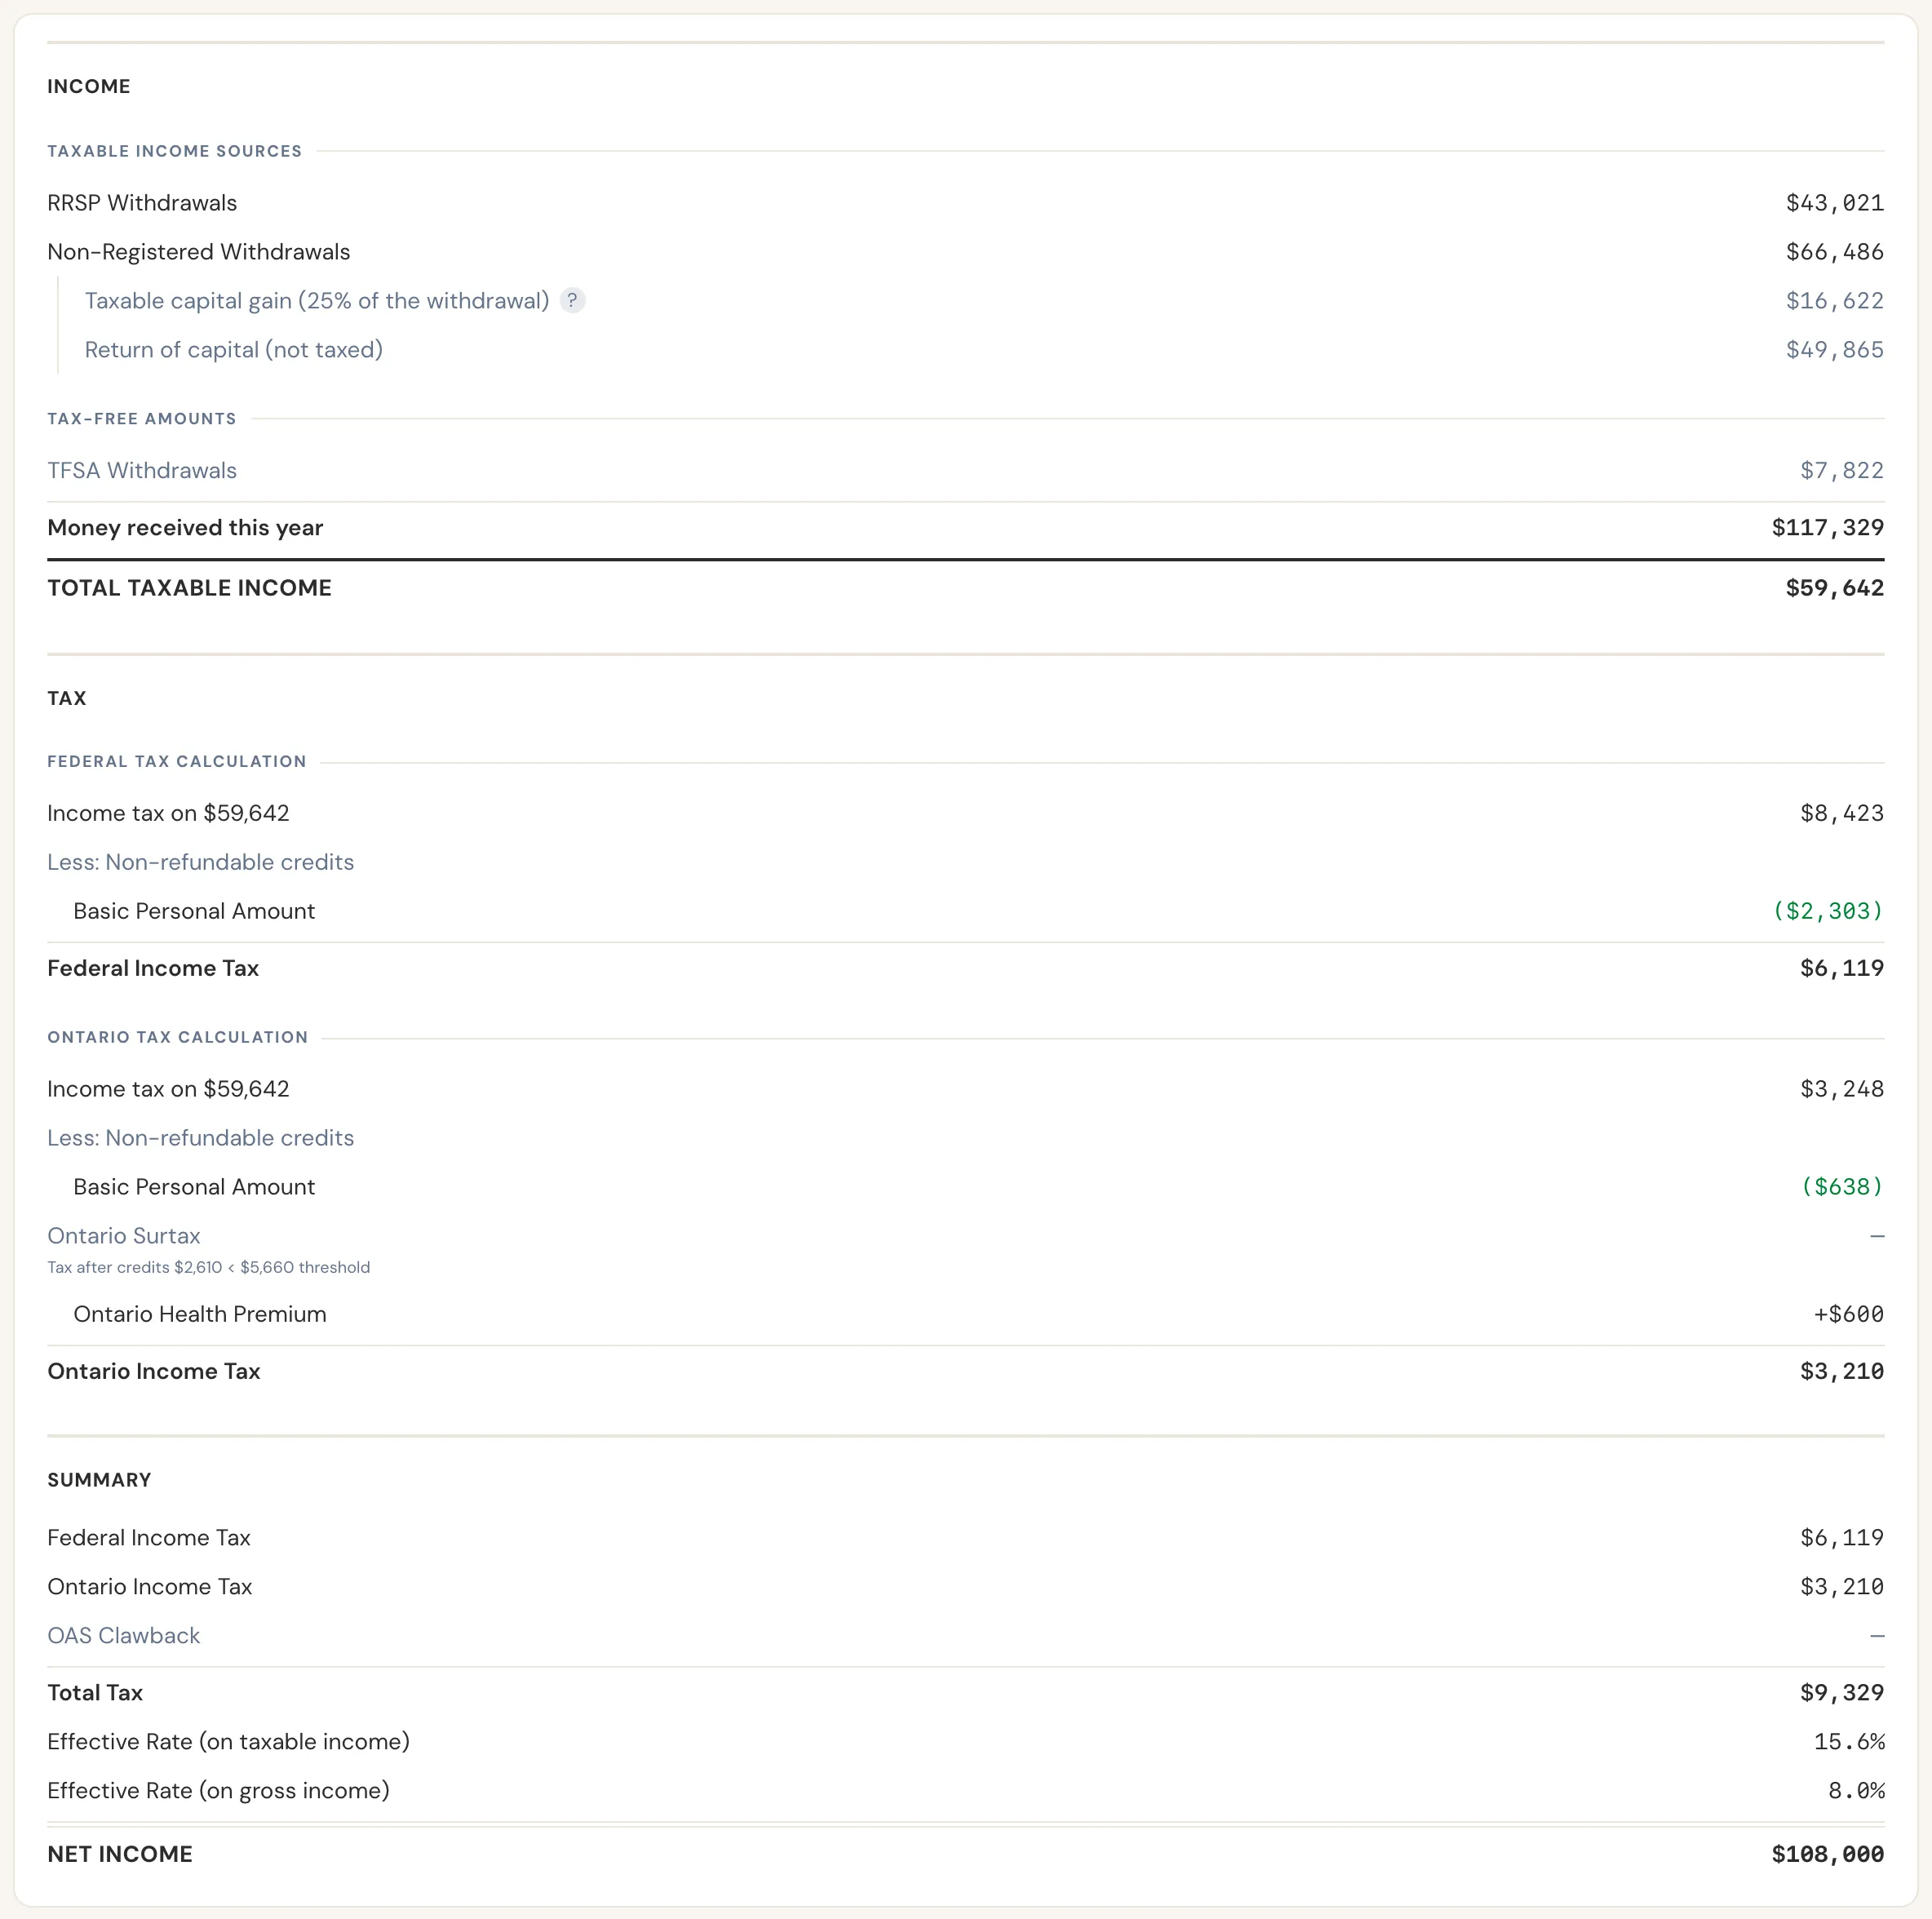 Arjun's tax bill in his first year of retirement, at age 60.
Arjun pays $9,329 in income tax in his first year, about 8% of a six-figure income. More than half of what he draws comes from his non-registered account, where only the capital gain is taxable, and only half of that gain counts as income. His TFSA withdrawals are tax-free.
His taxable income stays under the OAS clawback threshold in every year, so he keeps all of his OAS, though from 71 it comes within a few thousand dollars of it. At 71 his RRSP becomes a RRIF, the minimum withdrawal rises to $53,116, and his tax rises to $17,468. Over his whole retirement he pays $453,095.
How His Plan Changes Over Time
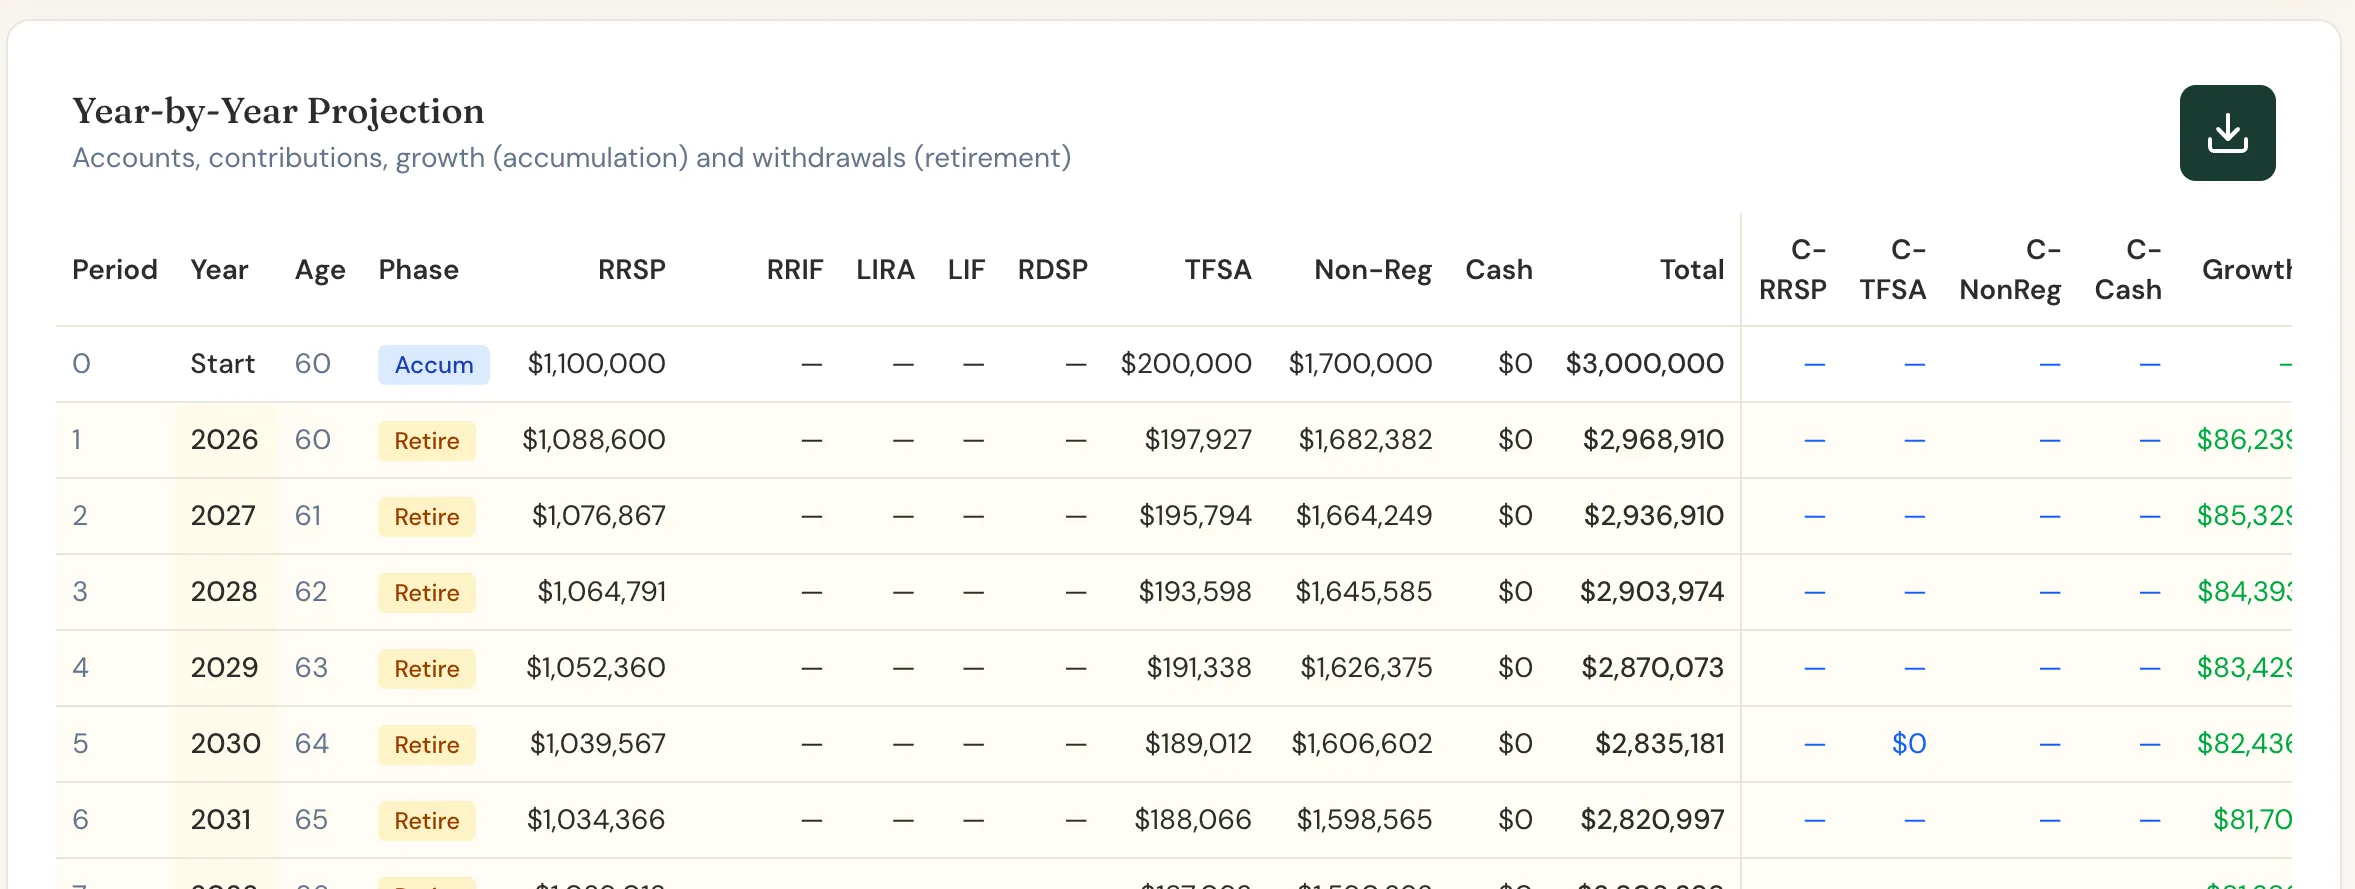 Year-by-year account balances from 60.
At 65, CPP and OAS start. Together they pay $25,108 a year.
At 71, his RRSP becomes a RRIF. The minimum withdrawal takes over from his non-registered account as his main source of income. Our RRIF guide covers the rules.
At 75 and 85, his spending steps down. His OAS also goes up 10% at 75.
At 90, he still has $2,506,109. That is $384,533 in his RRIF, $223,323 in his TFSA, and $1,898,253 in his non-registered account.
Based on his numbers, Scenario Lab+ estimates Arjun could spend about $3,525 more every month and still make it to 90.
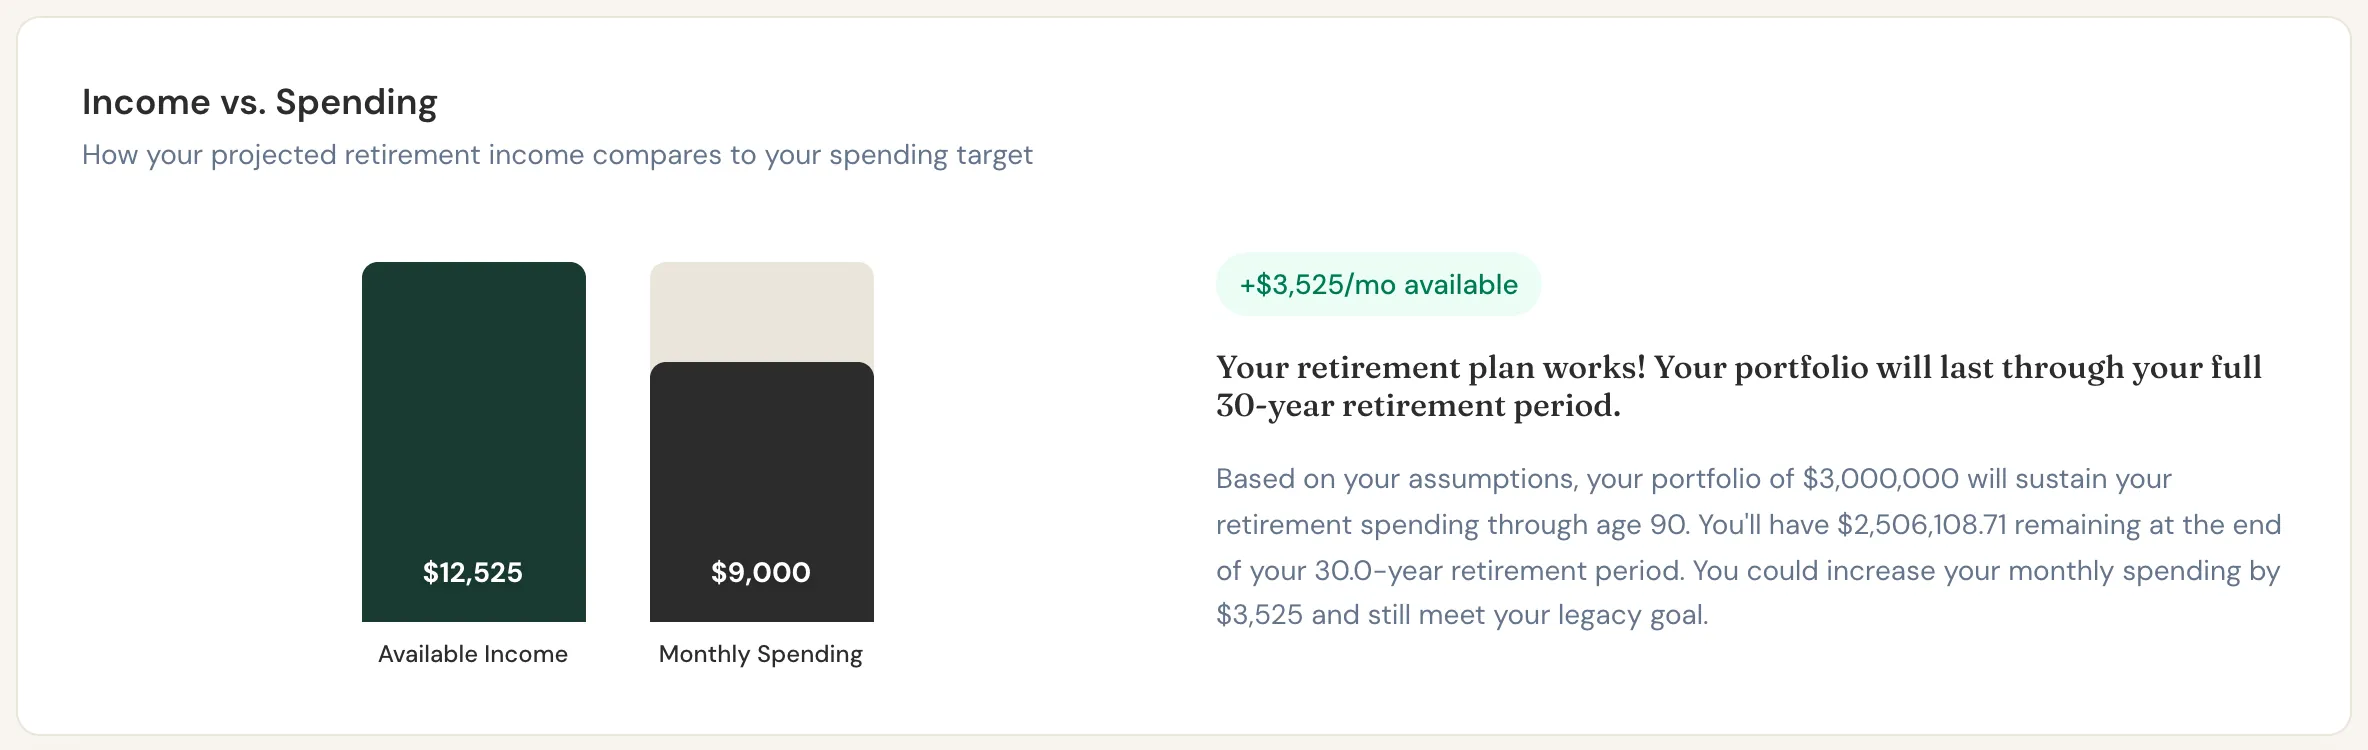 Income available to Arjun compared with what he plans to spend.
But What If We Change the Assumptions?
Arjun's plan has far more than he needs. So we looked at the three ways he could use the surplus, changing one assumption at a time.
4 versions of Arjun's plan
One assumption changed in each. Charts show the portfolio from 60 to 90 in Scenario Lab+.
Arjun's base plan
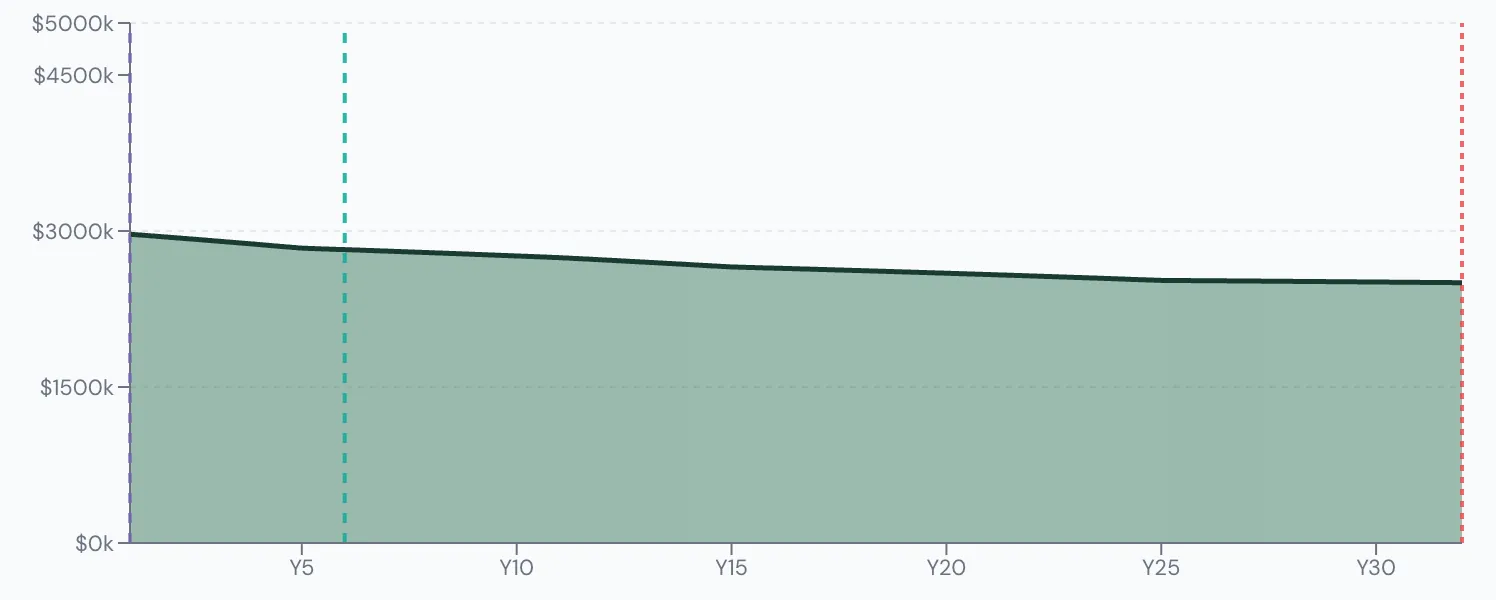
- Spends at 60
- $108,000/yr
- Money lasts
- Past 90
- Left at 90
- $2,506,109
Spends what Scenario Lab+ says he can
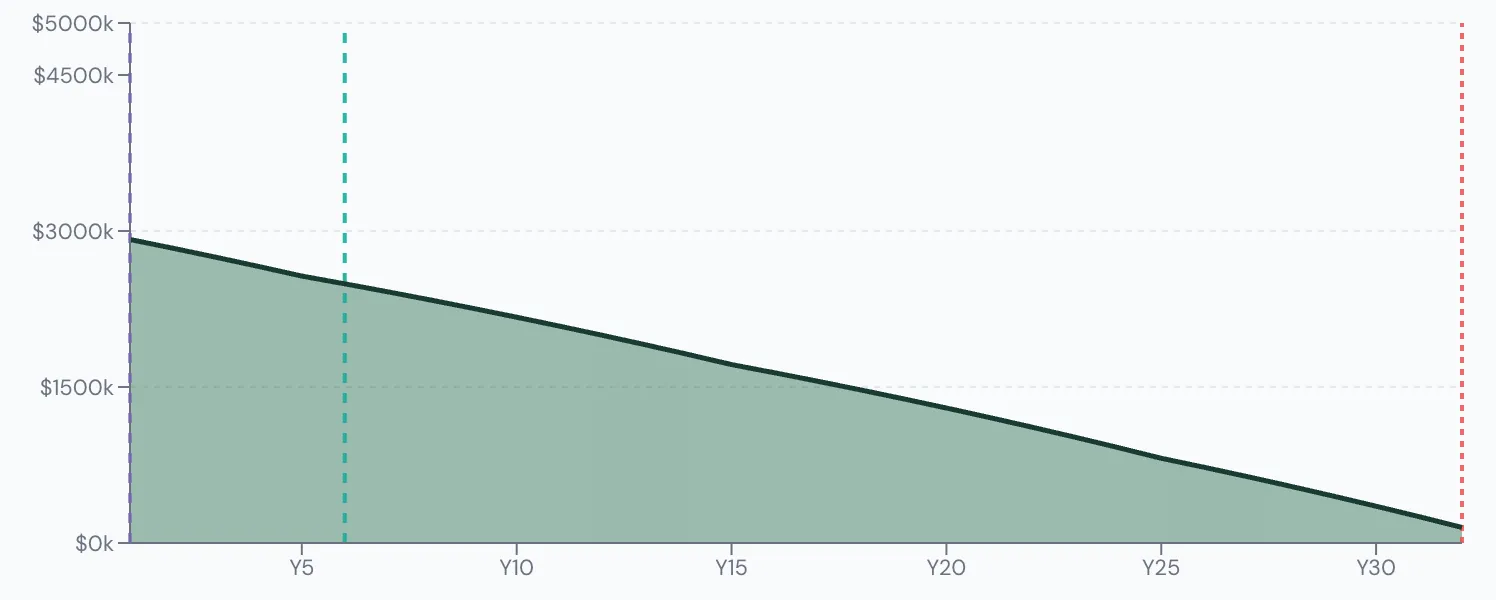
- Spends at 60
- $150,300/yr
- Money lasts
- Past 90
- Left at 90
- $253,198
Gives his kids $40,000 a year until 70
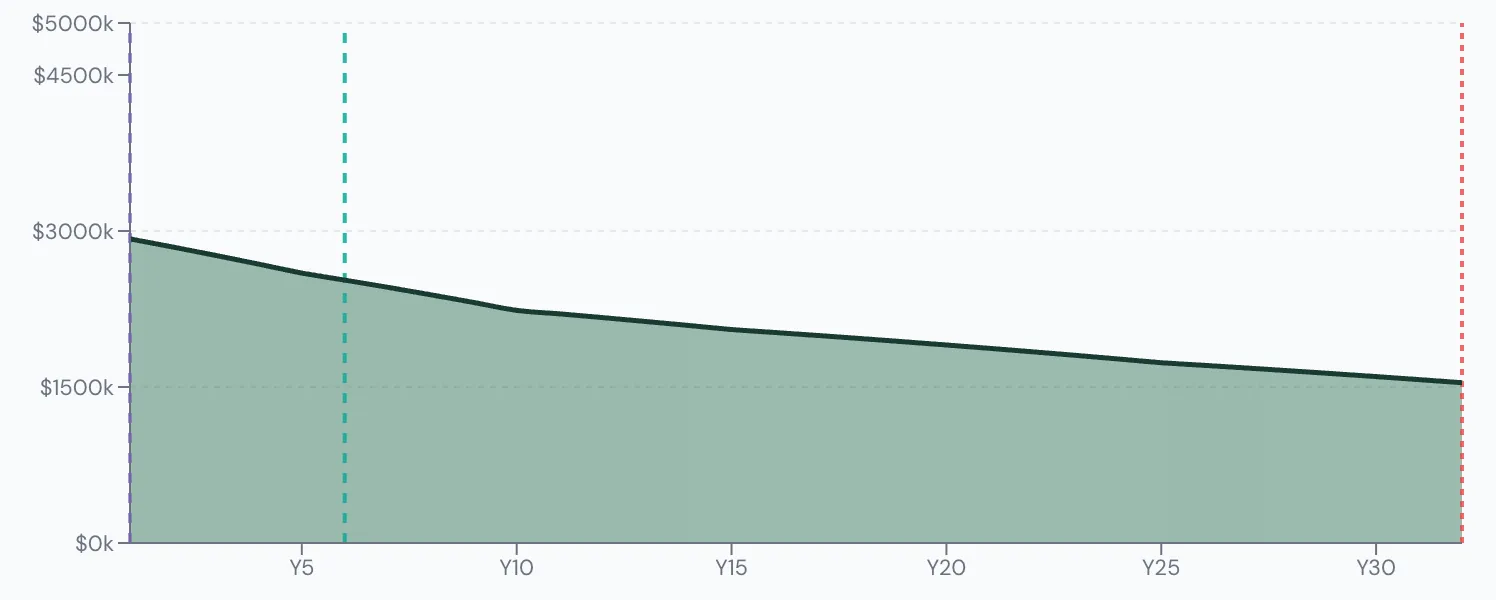
- Spends at 60
- $108,000/yr
- Money lasts
- Past 90
- Left at 90
- $1,571,045
Spends what he can and still leaves $1 million
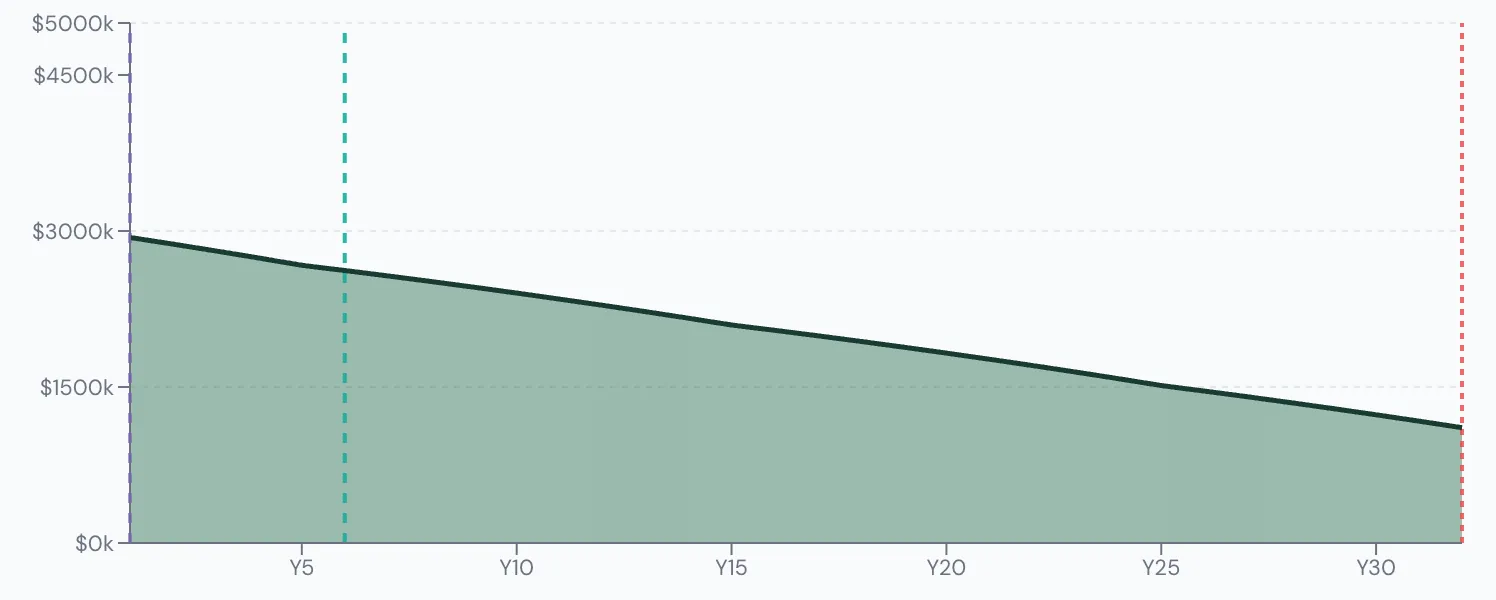
- Spends at 60
- $133,900/yr
- Money lasts
- Past 90
- Left at 90
- $1,171,658
Scenario 1
Spends what Scenario Lab+ says he can
- Spends at 60
- $150,300/yr
- Money lasts
- Past 90
- Left at 90
- $253,198
What if Arjun spends all of the room Scenario Lab+ finds, $12,525 a month instead of $9,000?
His plan still works, and he reaches 90 with $253,198. But spending more means drawing more from his RRSP, and from 65 his taxable income crosses the OAS clawback threshold. He repays $1,018 of OAS a year from 65 to 74, about $10,000 in total.
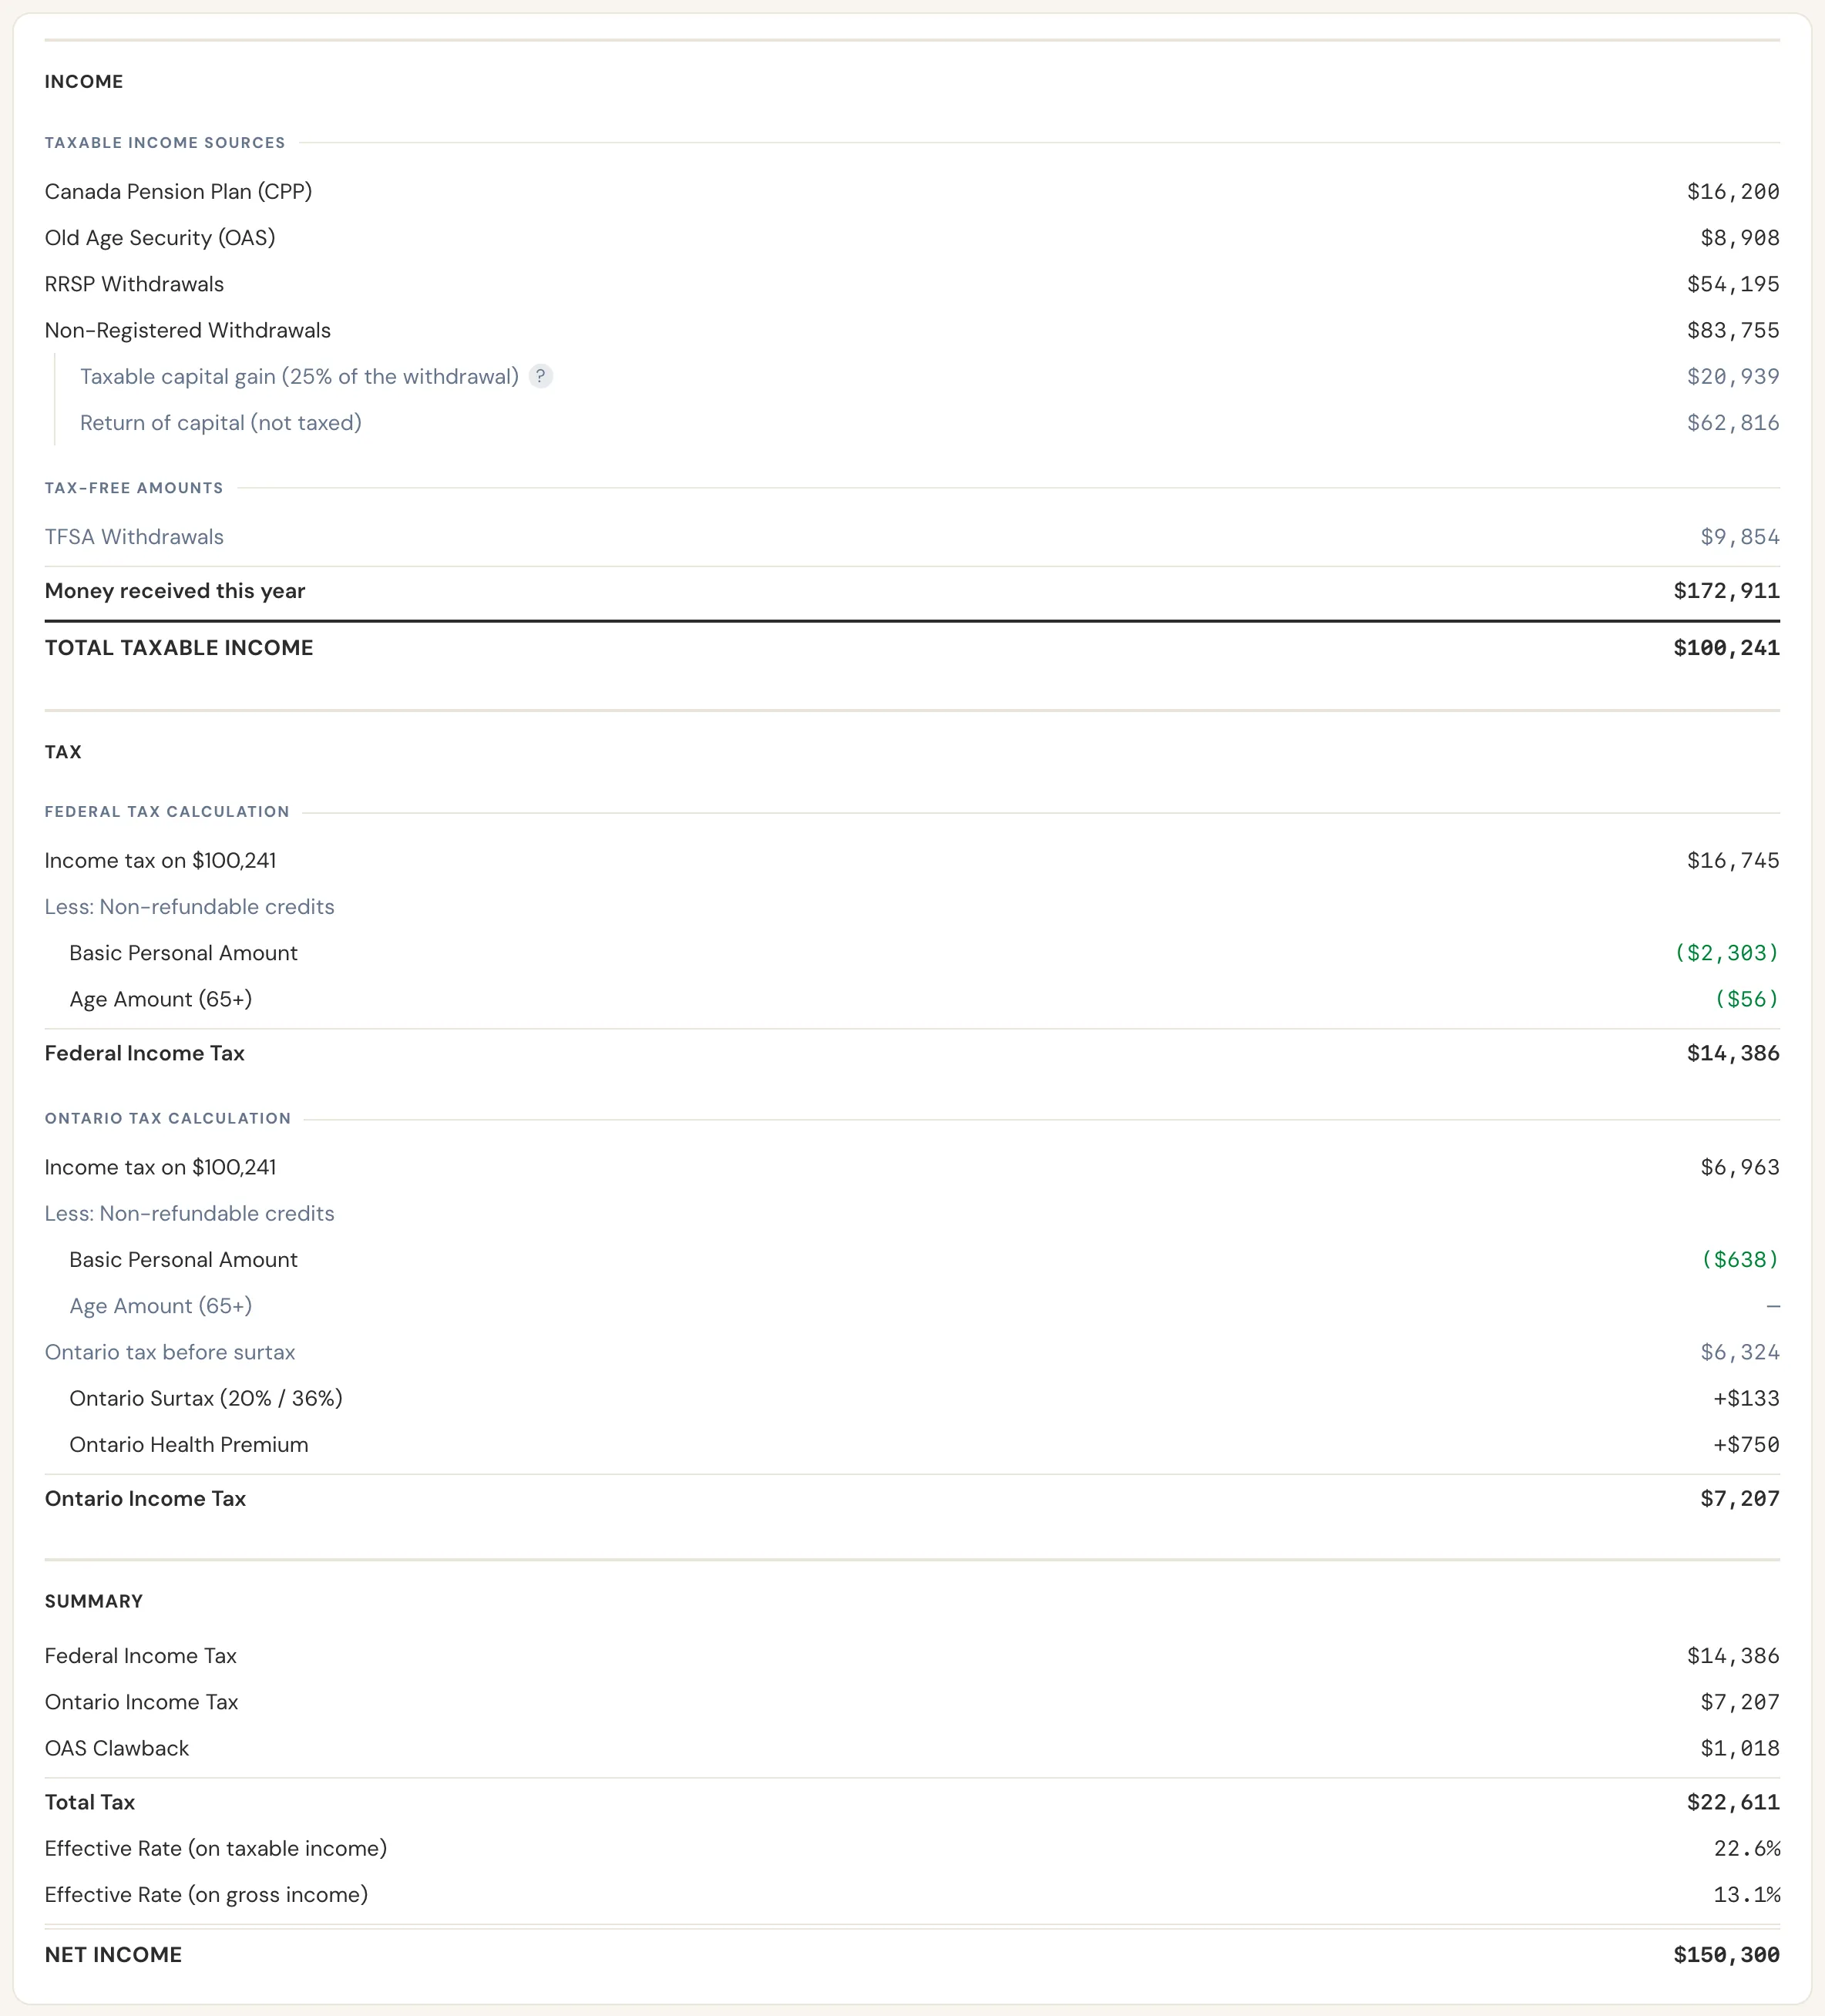 Arjun's tax bill at 65 if he spends all of his room.
Over his retirement he pays $581,033 in tax, about $128,000 more than his original plan. That's the cost of spending an extra $42,300 a year for 30 years, and most of it is ordinary income tax, not the clawback.
Scenario 2
Gives his kids $40,000 a year until 70
- Spends at 60
- $108,000/yr
- Money lasts
- Past 90
- Left at 90
- $1,571,045
What if Arjun helps his kids now, with $40,000 a year from 60 to 69, while they're buying homes and raising families? That's $400,000 in all. We modelled each gift with the One-Time Transactions feature in Scenario Lab+, paid from his non-registered account.
His own spending doesn't change, and his plan still works easily. He finishes at 90 with $1,571,045, and Scenario Lab+ estimates he would still have about $2,008 a month of room.
The gifts cost his estate far more than $400,000, though. He finishes about $935,000 below his original plan, because the money he gives away at 60 would otherwise have grown for 30 years. Selling investments to fund the gifts also realizes capital gains, and he pays about $28,000 more tax over his retirement.
For Arjun, that's a choice about timing, not about whether he can afford it: his kids receive less in total, but they receive it when it helps them most.
Scenario 3
Spends what he can and still leaves $1 million
- Spends at 60
- $133,900/yr
- Money lasts
- Past 90
- Left at 90
- $1,171,658
What if Arjun wants to leave his kids at least $1 million? In Scenario Lab+ that's a legacy goal, and the Recommendations tab then finds the most he can spend while still meeting it.
With a $1 million goal, Scenario Lab+ estimates he can spend $11,158 a month, about $2,158 more than his original plan. He finishes at 90 with $1,171,658, and his taxable income stays under the clawback threshold, so he keeps all of his OAS.
Your $3 Million Is Not Arjun's $3 Million
So can you retire with $3 million? Arjun can, with a lot to spare. But his plan is a starting point, not an answer for anyone else.
Where the money sits matters as much as the total. Arjun's is mostly non-registered, so his taxable income is low for the amount he spends. The same $3 million mostly in an RRSP would put far more of it on his tax return, much like Karen's $2 million at 60. For $2 million at 65, see Daniel's plan.
The bigger risk at $3 million is spending too little, or giving too late, without ever running your own scenario.
That's why we built Scenario Lab+.
It is the software behind every number in this article. Give it your own accounts and spending, and it builds the same year-by-year plan for you, including every what-if above. If you'd like to see it first, Arjun's full plan is open to explore.
Build Your Own Canadian Retirement Plan
Enter your own savings, benefits, and spending in Scenario Lab+ to see whether your number is enough and what happens when your assumptions change.
Start now