

The short answer
- Yes: $2 million at 60 supports $7,500 a month after tax for Karen, with $333K left at 95.
- Because almost all of it sits in her RRSP, she repays about $16,000 of OAS to the clawback between 65 and 74.
- The order she draws her accounts in can cost her $88,000 more in tax over her retirement.
Estimates from Scenario Lab+, in today's dollars.
See the demo planTwo million dollars sounds like the end of the retirement question. For a lot of high earners it isn't, because of where the money sits. Decades of maximum RRSP contributions leave a portfolio that is almost entirely taxable on the way out, and a taxable retirement income above about $95,000 starts to cost you your OAS.
Here at Loonie Nest, our mission is to provide free and affordable personal finance education to Canadians so they can gain confidence in their retirement.
Karen's plan at a glance
$2,000,000
saved at 60
RRSP
$1,750,000
Taxed as income when withdrawn
TFSA
$100,000
Withdrawals are tax-free
Non-registered
$150,000
Only the capital gain is taxed
Spending after tax, in today's dollars
$90,000
$81,000
$72,000
CPP $1,250 a month from 65
OAS $742 a month from 65
Our $2 Million Retirement Scenario
Let's meet Karen. She's 60, single, and living in North Vancouver, BC. She spent her career in sales at a pharmaceutical distributor, ending as a sales director, with no workplace pension. She put the maximum into her RRSP almost every year for 30 years. Now she has $2 million and wants to stop working, and she wants to know what all that RRSP money will cost her in tax.
We'll run Karen's numbers through Scenario Lab+.
Scenario Lab+ is our proprietary retirement planning software. We'll use it to generate and review a tailored retirement plan for her.
To start, here's how Karen's numbers look as she retires at 60:
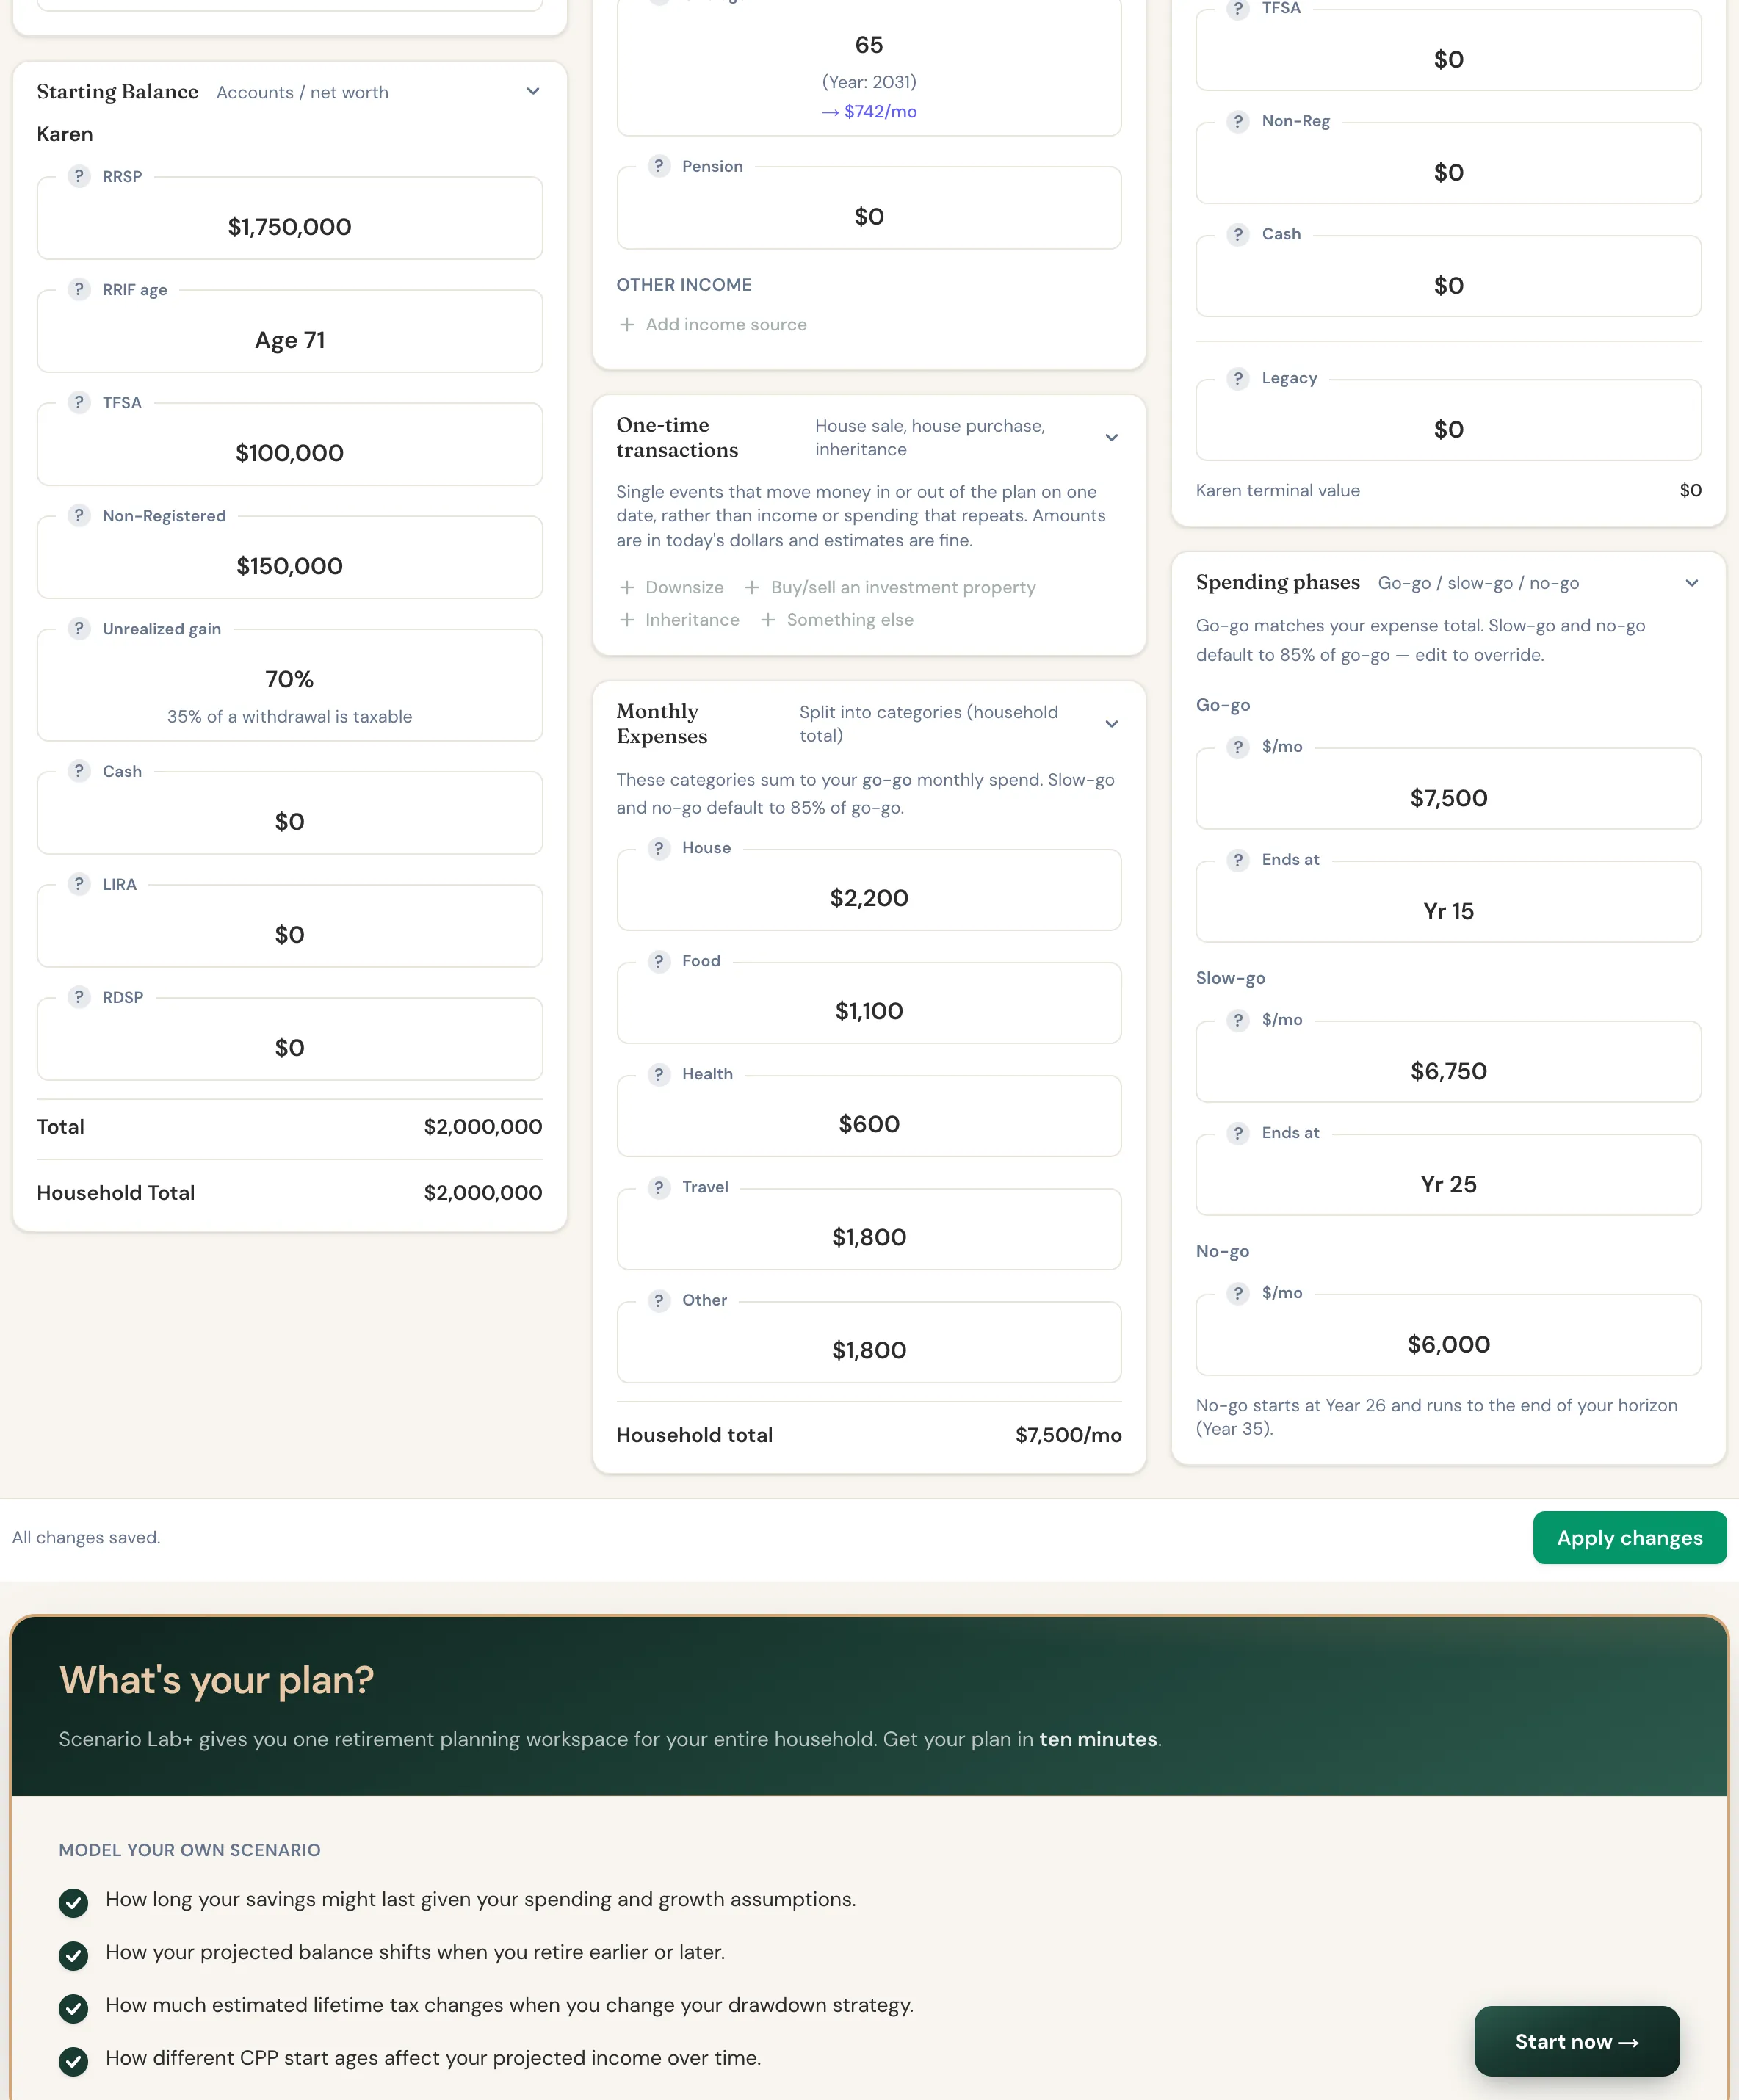 Karen's plan inputs: her profile, account balances, CPP and OAS, and monthly spending.
$1.75 million of her $2 million is in her RRSP. She also has $100,000 in her TFSA and $150,000 in a non-registered account. Every dollar that comes out of an RRSP or RRIF is taxed as income.
Karen's CPP is $1,250 a month at 65. Her Statement of Contributions assumes she stops contributing at 60, and those five empty years pull the amount down from what a full career at her salary would pay. She plans to start CPP and OAS at 65. If you want a refresher on how both programs work, see our guide to CPP and OAS.
Five years before any government income. From 60 to 64 she lives entirely on her savings.
Her spending falls as she ages. Karen's plan starts at $7,500 a month and steps down at 75 and again at 85. In Scenario Lab+, these steps are the plan's Spending Phases.
A few other important assumptions: all figures are in today's dollars, Karen owns her townhouse with no mortgage, she expects her investments to grow 5.5% a year, inflation runs at 2.5% a year, and we plan her retirement to age 95.
Karen's retirement budget
Here is how her $7,500 a month breaks down until she turns 75:
| Category | Monthly | Annual |
|---|---|---|
| Housing (strata fees, property tax, utilities, insurance) | $2,200 | $26,400 |
| Food and dining | $1,100 | $13,200 |
| Health and dental | $600 | $7,200 |
| Travel | $1,800 | $21,600 |
| Everything else (car, gifts, entertainment) | $1,800 | $21,600 |
| Total | $7,500 | $90,000 |
Costs vary a lot across the Lower Mainland and the rest of BC. Our guide to the best places to retire in Canada compares cities and regions.
Is $2 Million Enough to Retire at 60?
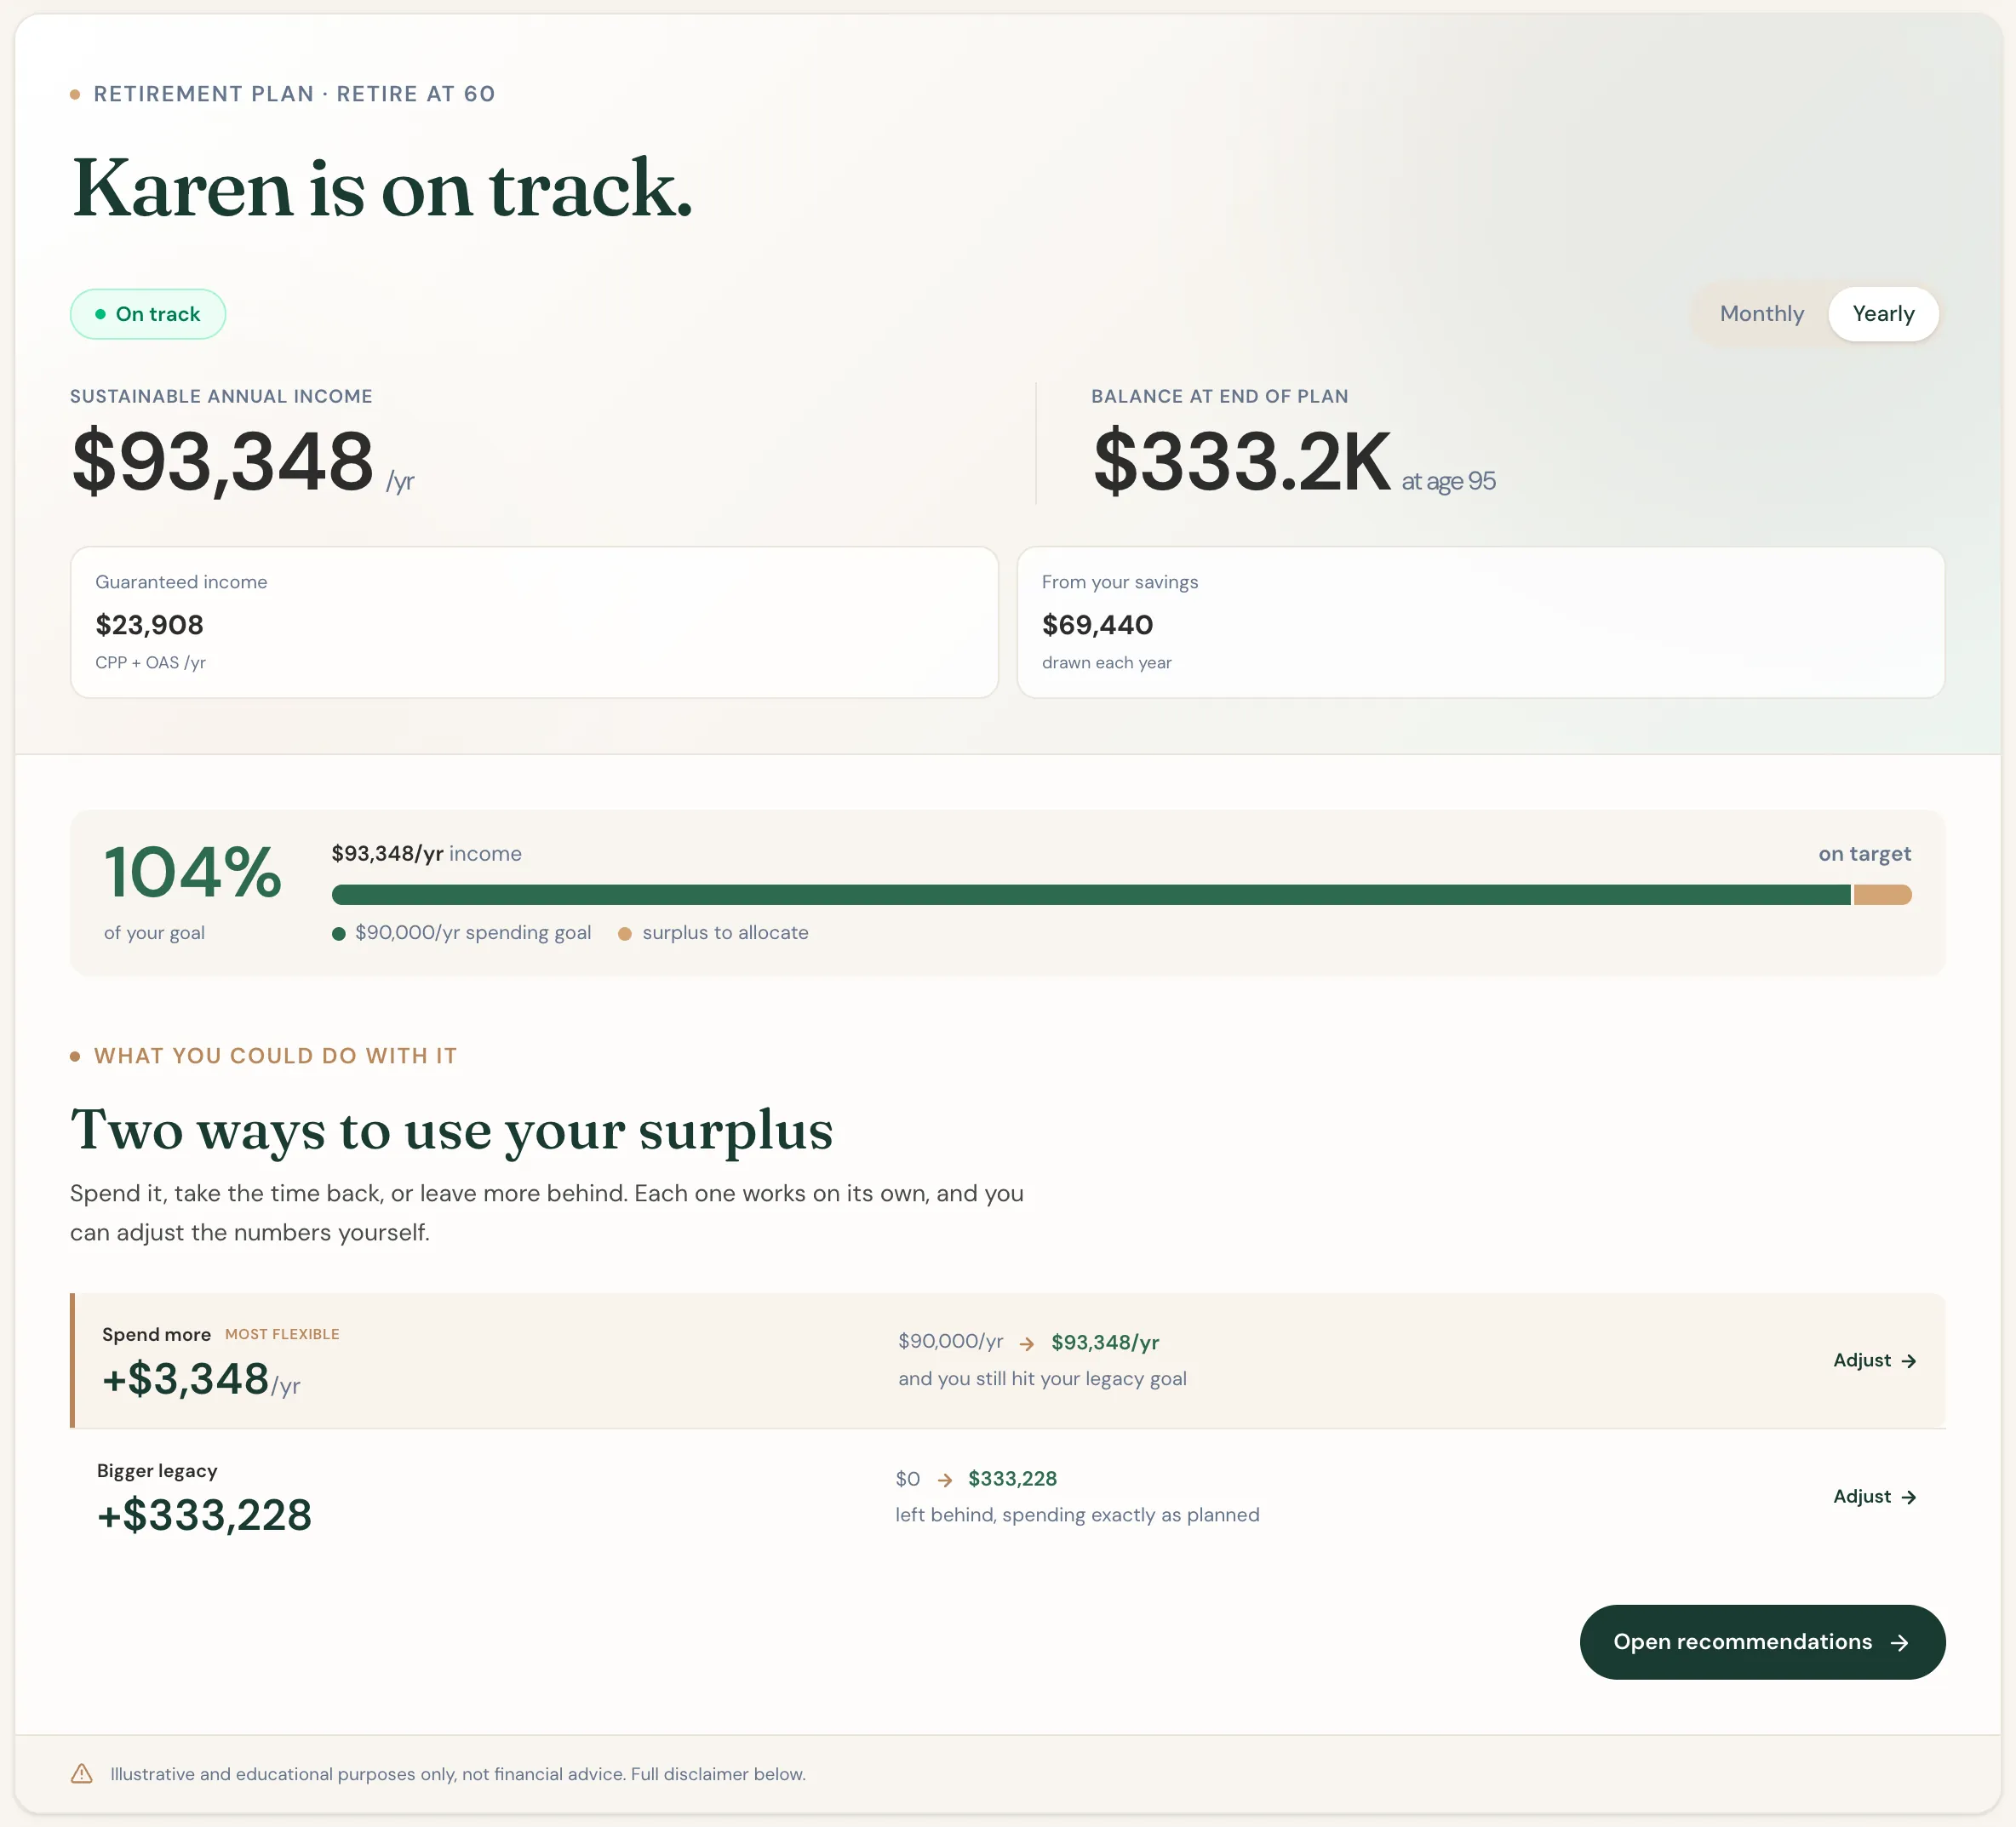 Scenario Lab+'s results for Karen's plan.
For Karen, the results say yes. Her plan covers her spending every year and still has $333,228 left at 95. Scenario Lab+ estimates she could spend about $279 more a month and still make it, which is a thin margin for a $2 million plan.
A generic 4% rule would suggest $2 million supports about $80,000 a year. Karen draws $110,069 from her savings in her first year, about 5.5%, because she has five years to cover before CPP and OAS start. Tax takes a large share of that draw, which is the theme of her whole plan.
How Much Income Does $2 Million Provide?
In her first year of retirement, Karen draws $110,069 of gross income to put $90,000 in her pocket:
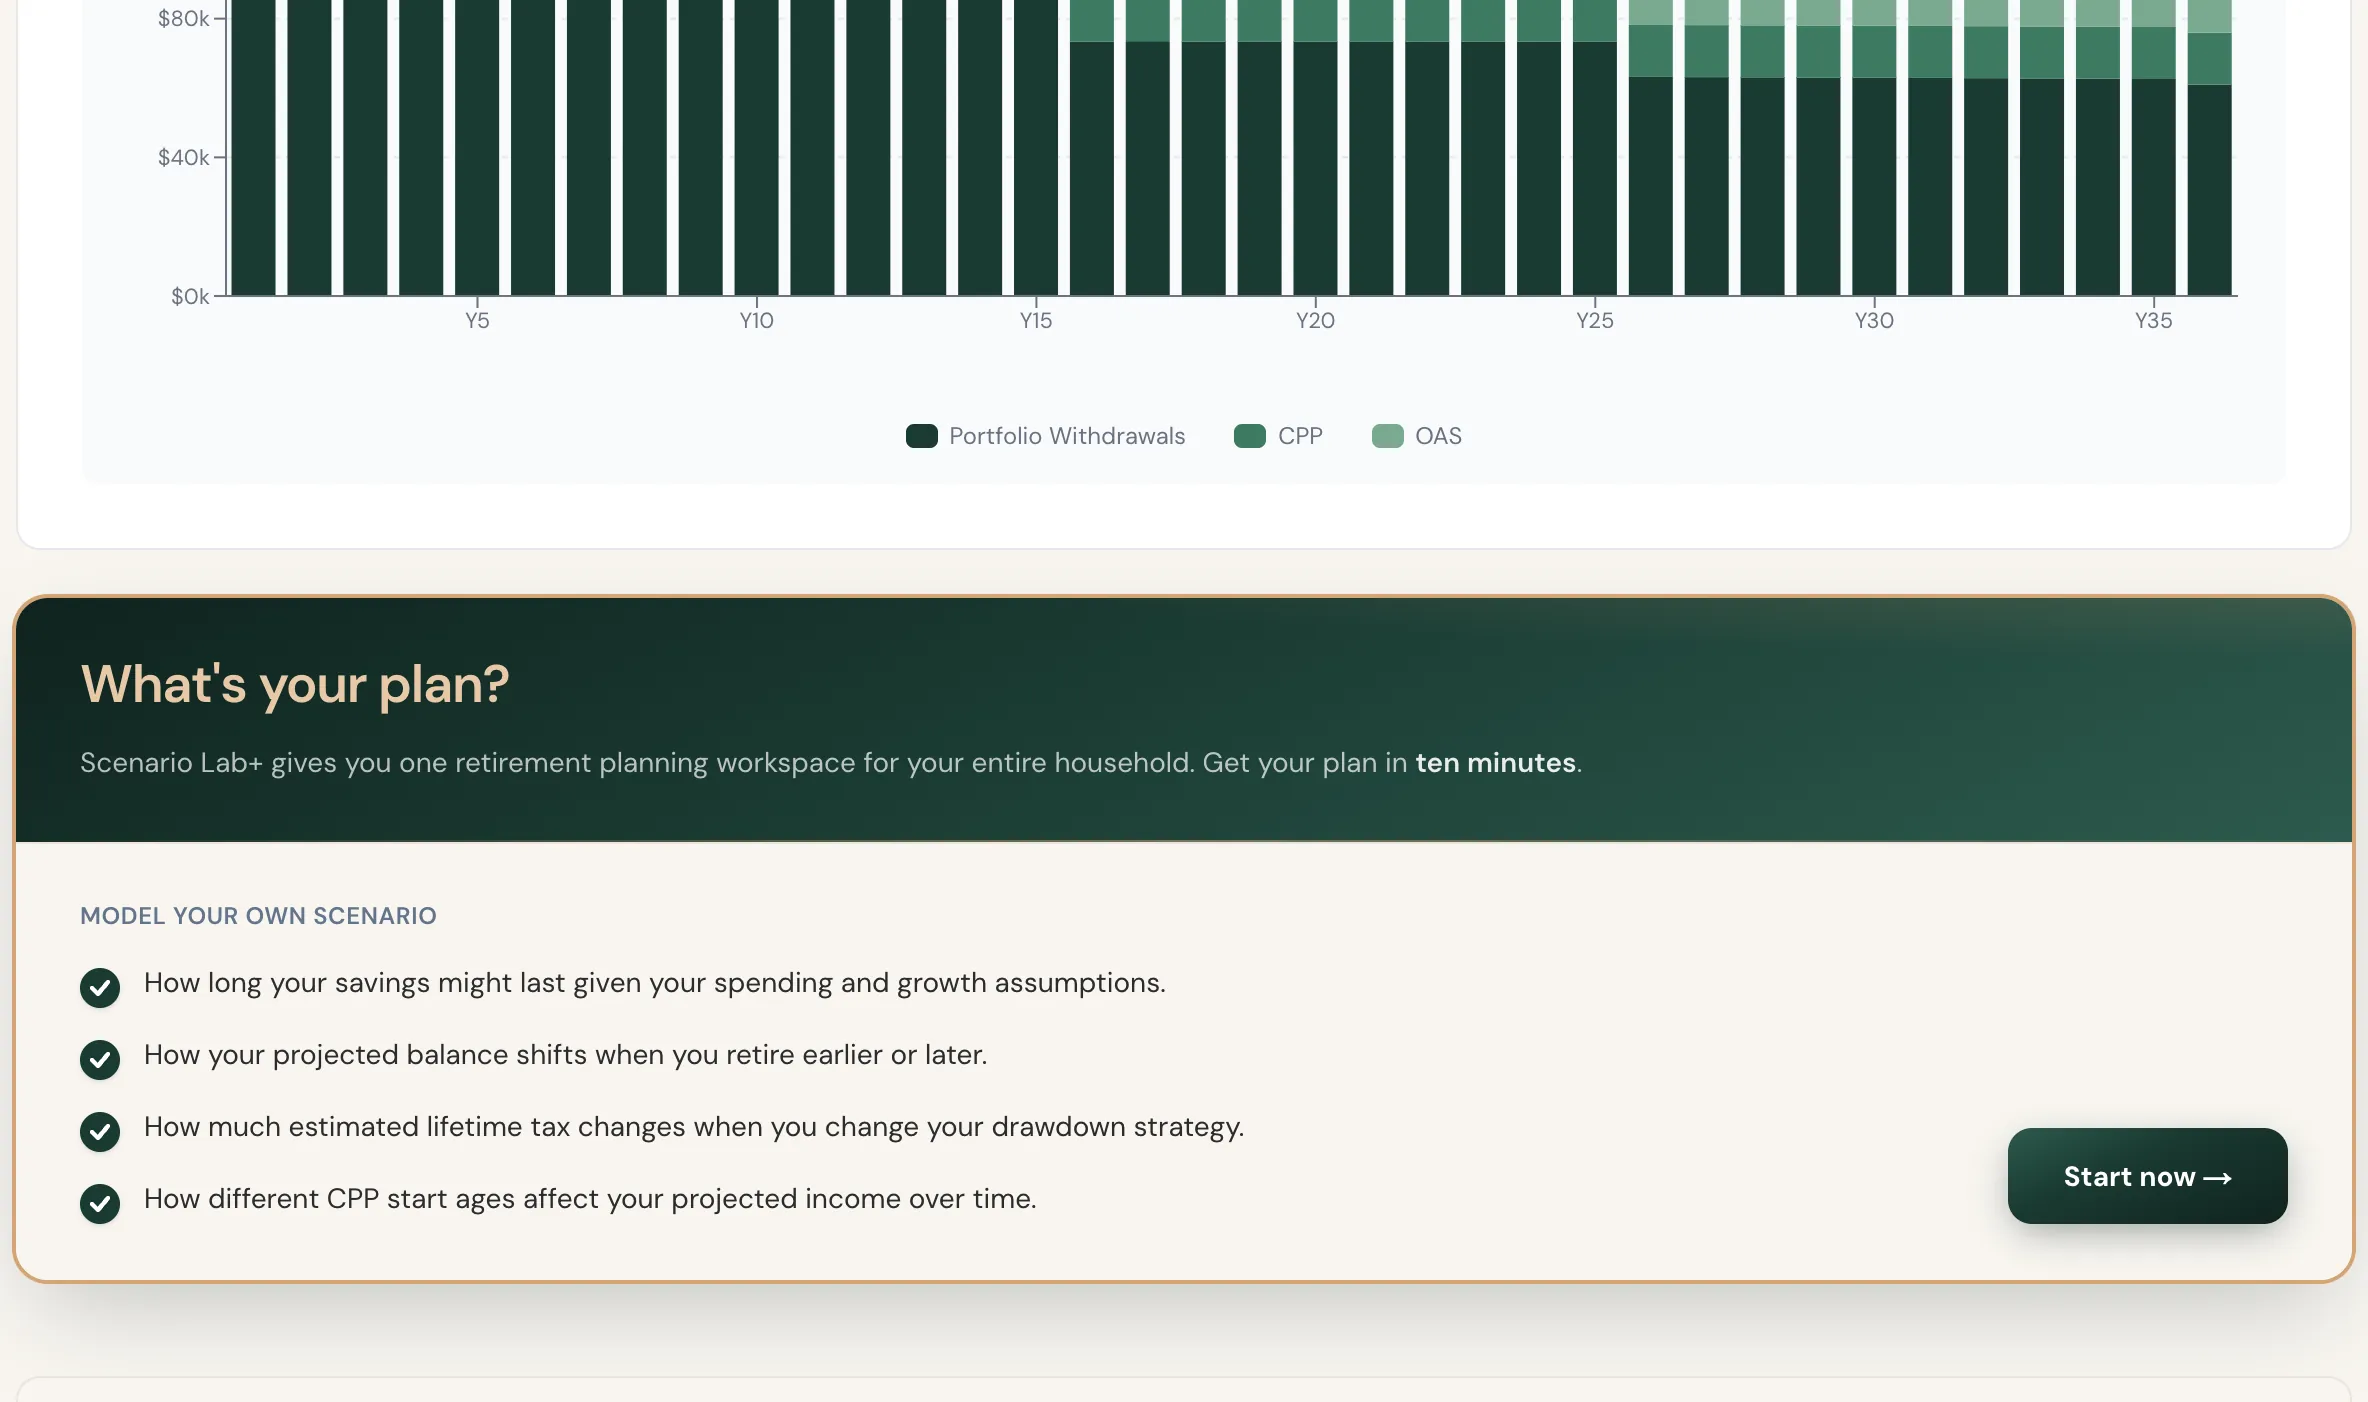 Where Karen's income comes from each year, by source.
| Source | Age 60 | Age 65 | Taxable? |
|---|---|---|---|
| CPP | $0 | $15,000 | Yes |
| OAS | $0 | $8,908 | Yes |
| RRSP withdrawals | $96,311 | $78,239 | Yes |
| TFSA withdrawals | $5,503 | $4,471 | No |
| Non-registered withdrawals | $8,255 | $6,706 | Only the capital gain |
| Gross income | $110,069 | $113,324 | |
| Income tax | $20,069 | $23,324 | |
| Spending money | $90,000 | $90,000 |
Scenario Lab+ uses its Proportional drawdown strategy by default, drawing from every account each year roughly in proportion to its balance. For Karen, that means about seven of every eight dollars come from her RRSP. The Drawdown tab runs the same plan through other withdrawal strategies, and for someone this RRSP-heavy the choice matters, as you'll see below.
Is most of your money in your RRSP?
Scenario Lab+ shows the tax on every withdrawal, year by year, and compares four drawdown strategies for your own accounts.
Try Scenario Lab+How Much Tax Karen Pays
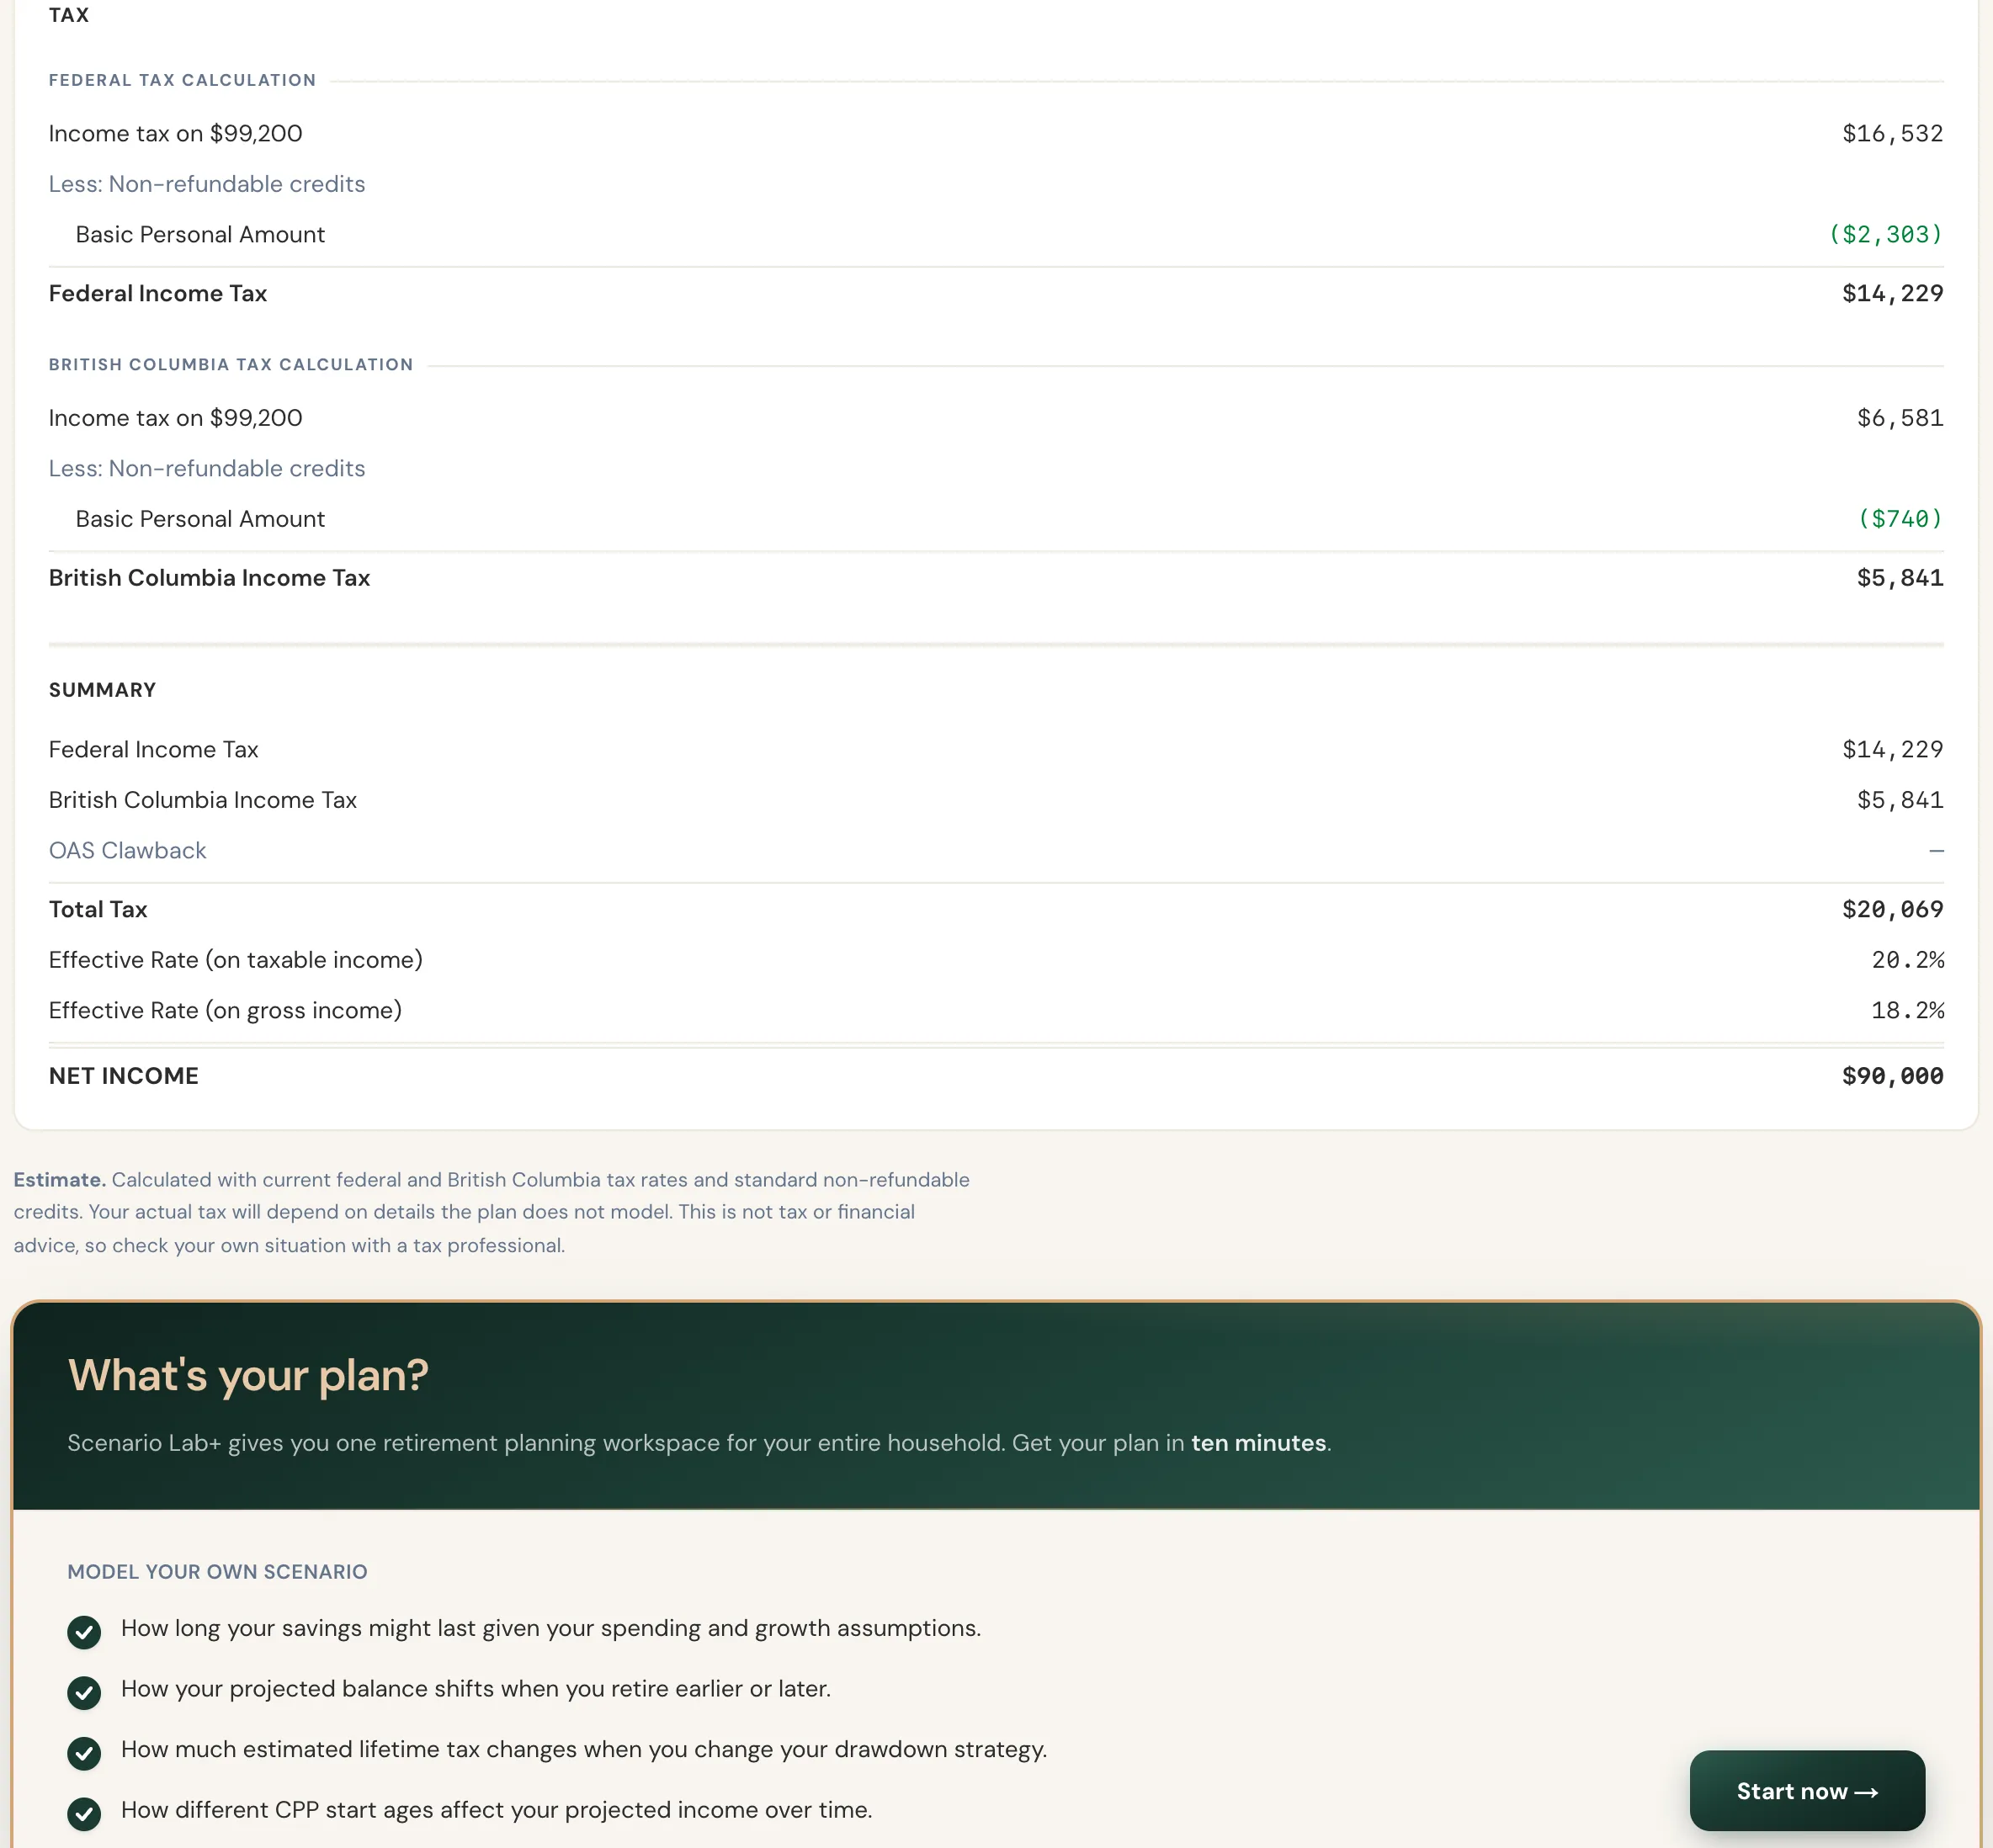 Karen's tax bill in her first year of retirement, at age 60.
Karen pays $20,069 in income tax in her first year, about 18% of her gross income, on $99,200 of taxable income. Almost all of her income is taxable, because almost all of it comes from her RRSP. Over her whole retirement she pays $673,586 in tax.
How Much OAS Karen Loses to the Clawback
At 65 her CPP and OAS start, and they sit on top of her RRSP withdrawals. Her taxable income comes to about $104,500, which is over the OAS clawback threshold. The clawback, formally the OAS recovery tax, takes back 15% of every dollar above the threshold.
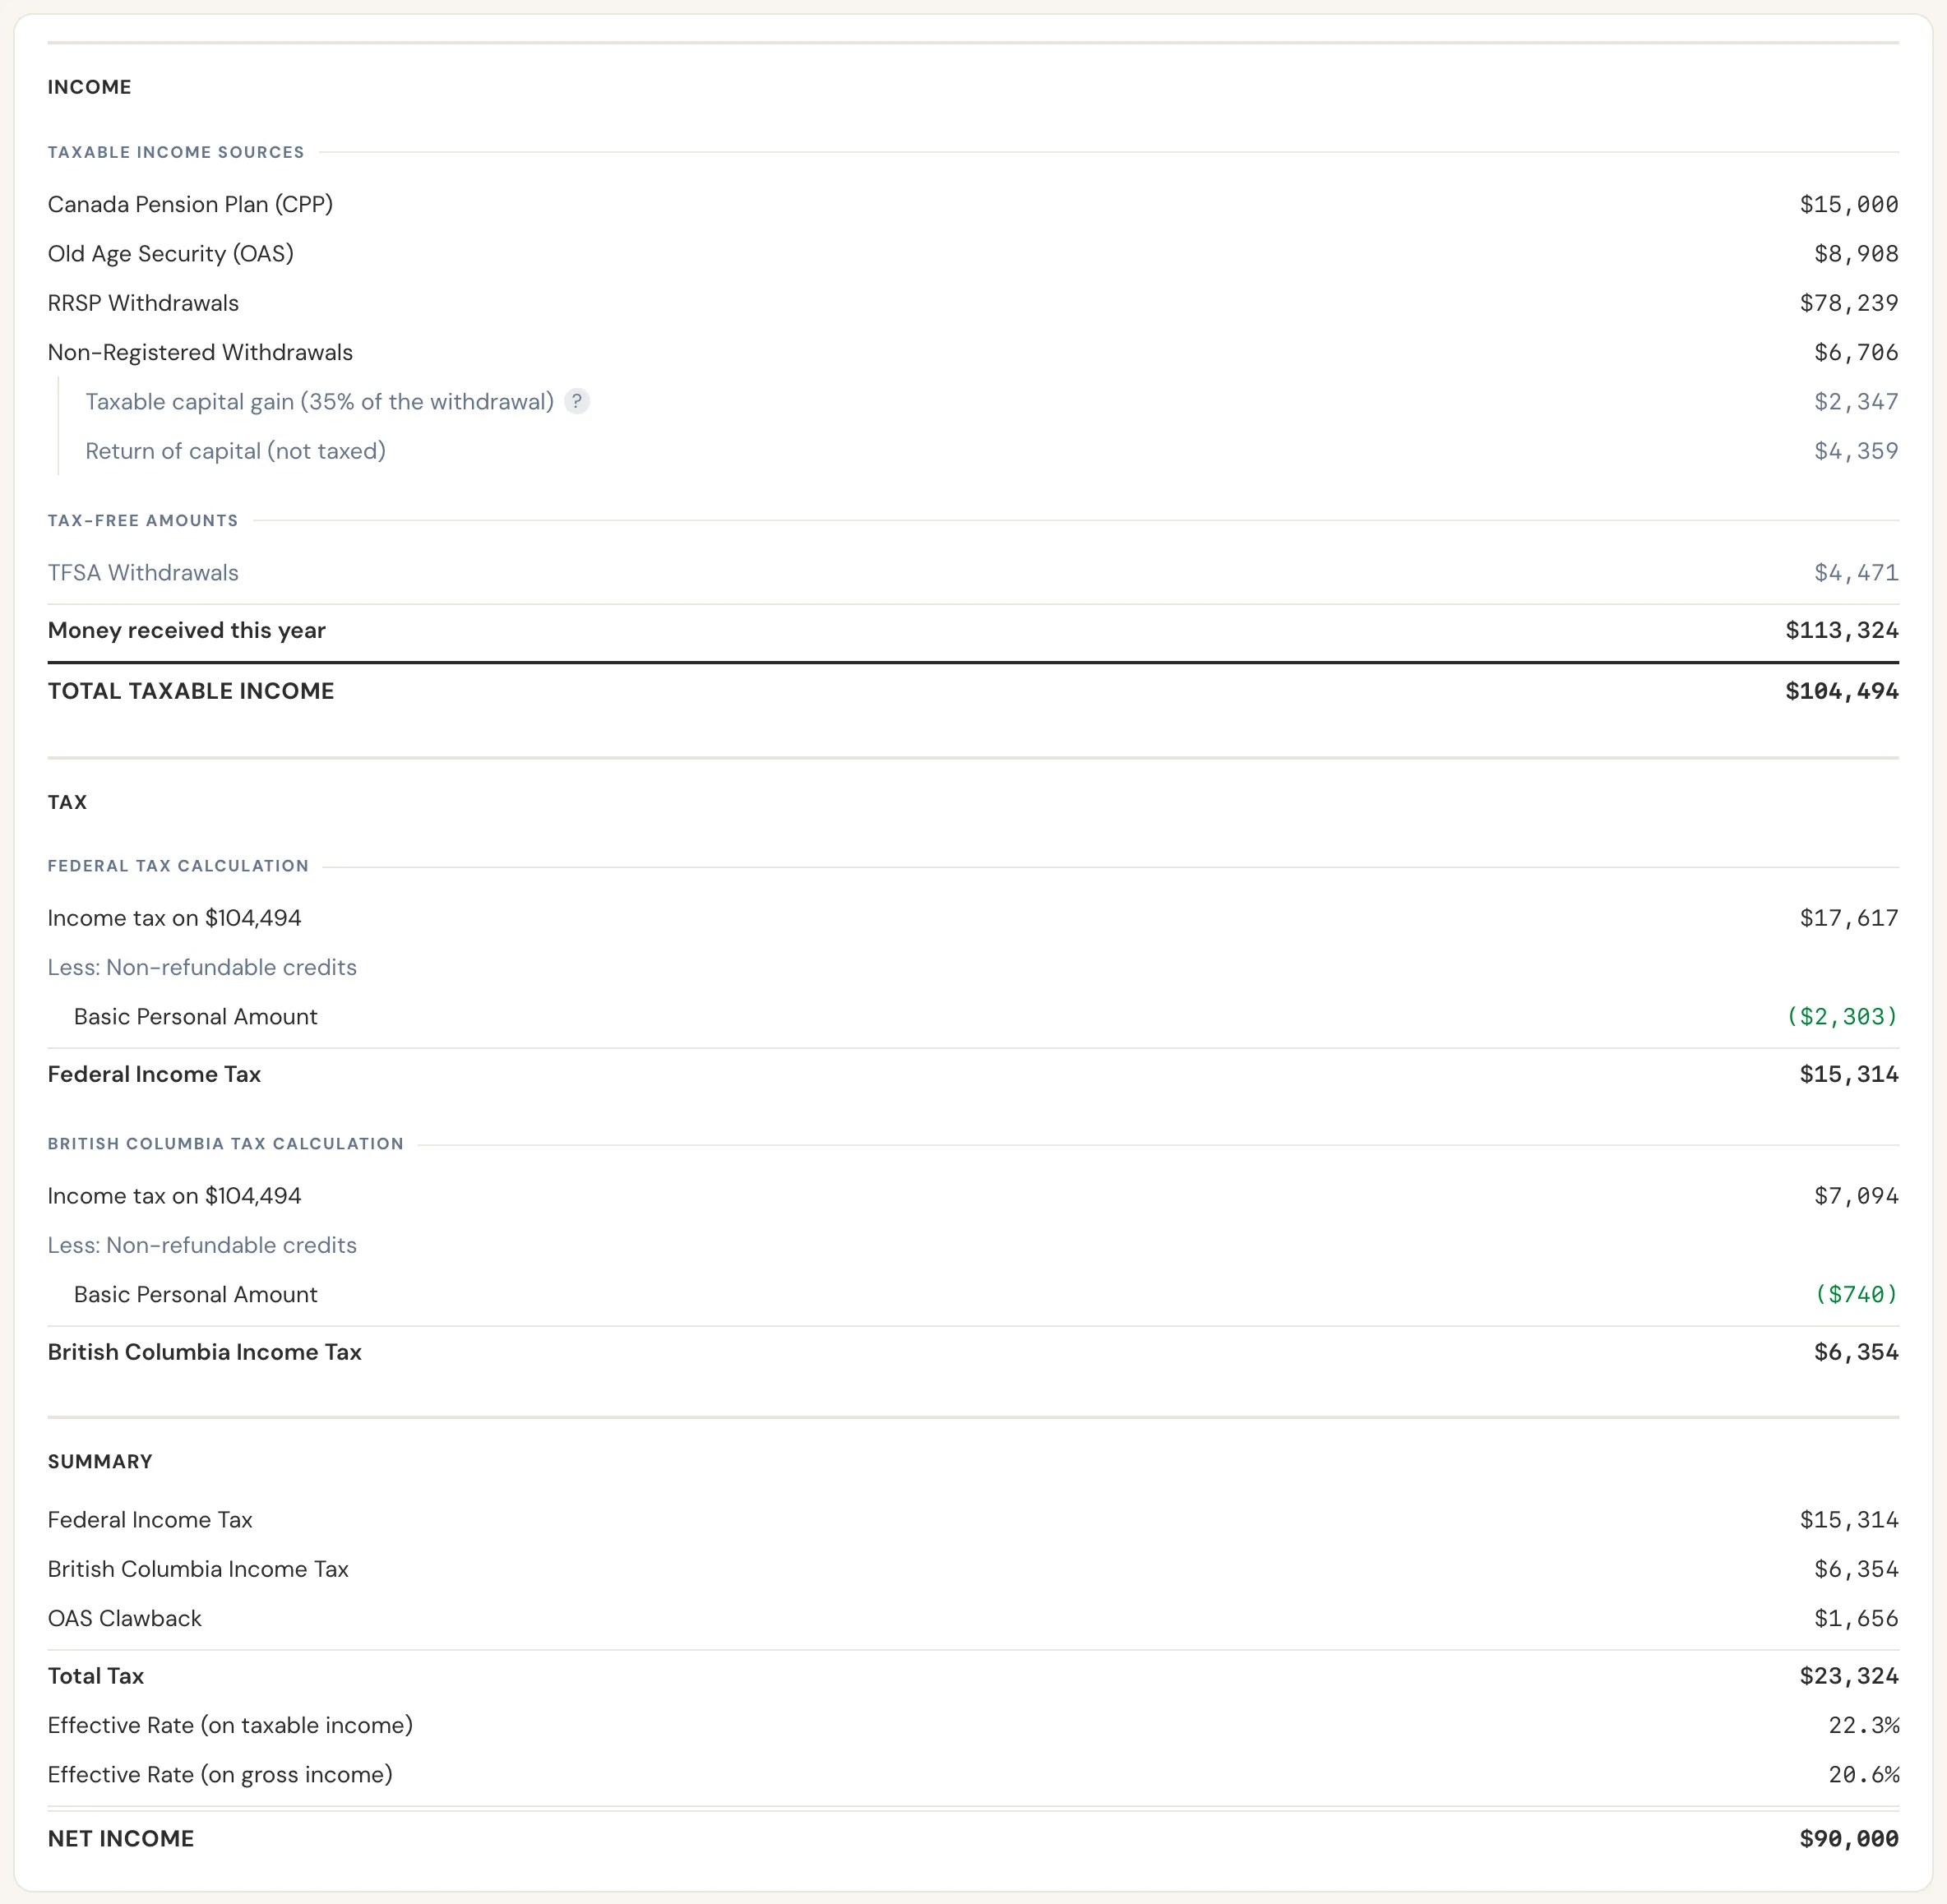 Karen's tax bill at 65, the first year of CPP and OAS.
She repays $1,656 of her $8,908 OAS each year from 65 to 70, and $1,578 a year from 71 to 74. In total, about $16,000 of OAS goes back to the government before her spending steps down at 75 and her income falls below the threshold.
Karen doesn't reach the clawback because of her RRIF minimums. At 71, when her RRSP becomes a RRIF, her withdrawals barely change, from $78,239 to $77,737, because she was already drawing more than the minimum. She reaches it because she spends $7,500 a month from a portfolio that is almost all RRSP. TFSA withdrawals aren't taxable income, and only the capital gain on non-registered withdrawals is, so the same spending from a more evenly split $2 million would show a lower taxable income.
How Her Plan Changes Over Time
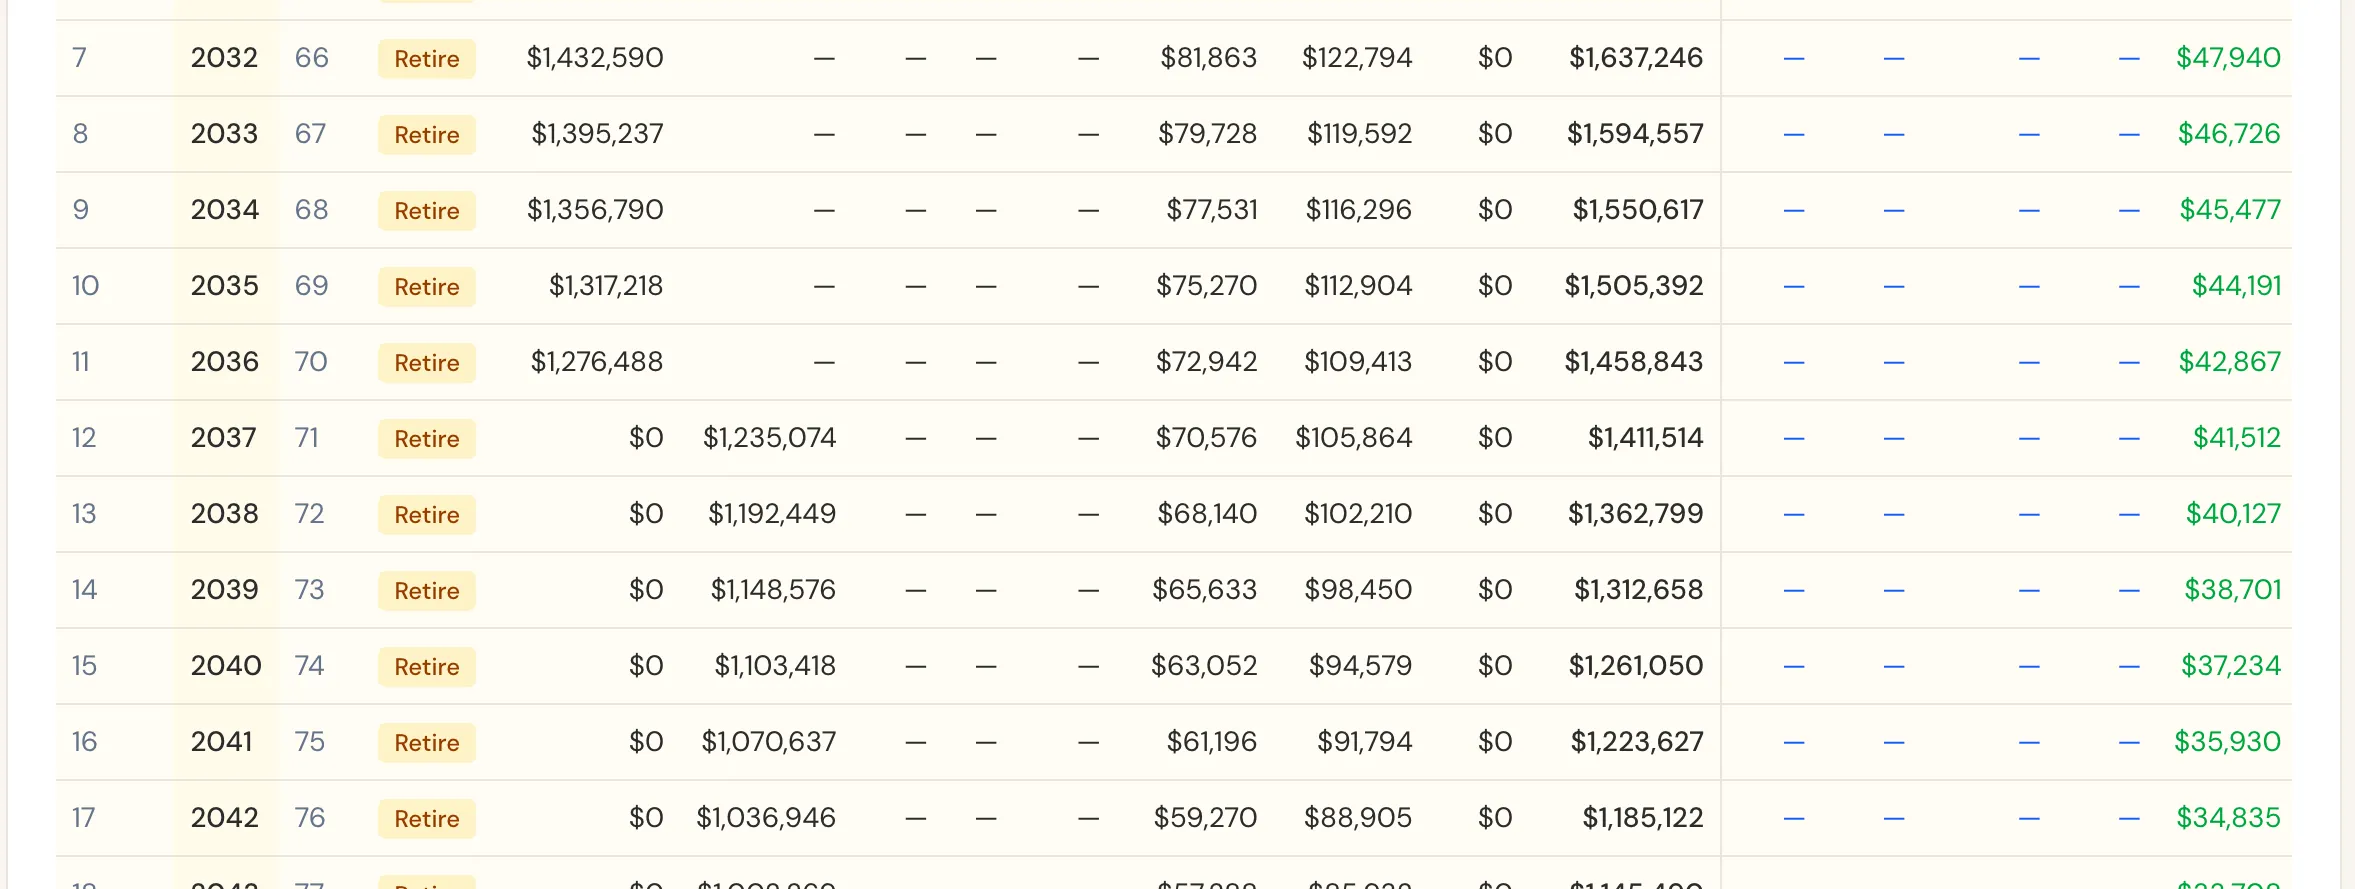 Year-by-year account balances from 60.
In Scenario Lab+, the Table tab shows every account for every year, and the whole table downloads as an Excel file.
At 65, CPP and OAS start, and so does the clawback. Her withdrawals from savings fall, but her taxable income rises.
At 71, her RRSP becomes a RRIF. For Karen, the minimum withdrawal is below what she already takes, so little changes. Our RRIF guide covers the rules.
At 75, her spending steps down and the clawback ends. Her budget drops to $6,750 a month, her OAS rises 10% to $9,798 a year, and her taxable income falls to about $91,000.
At 95, she still has $333,228. That is $220,202 in her RRIF, $45,210 in her TFSA, and $67,816 in her non-registered account. The RRIF portion is before tax: it is taxable when it comes out or when she dies.
Based on her numbers, Scenario Lab+ estimates Karen could spend about $279 more every month and still make it to 95.
 Income available to Karen compared with what she plans to spend.
But What If We Change the Assumptions?
Karen's plan works, so the useful question is how much of her money ends up with the government. We changed one assumption at a time, focusing on the order she draws her accounts in and when she takes her OAS.
4 versions of Karen's plan
One assumption changed in each. Charts show the portfolio from 60 to 95 in Scenario Lab+.
Karen's base plan
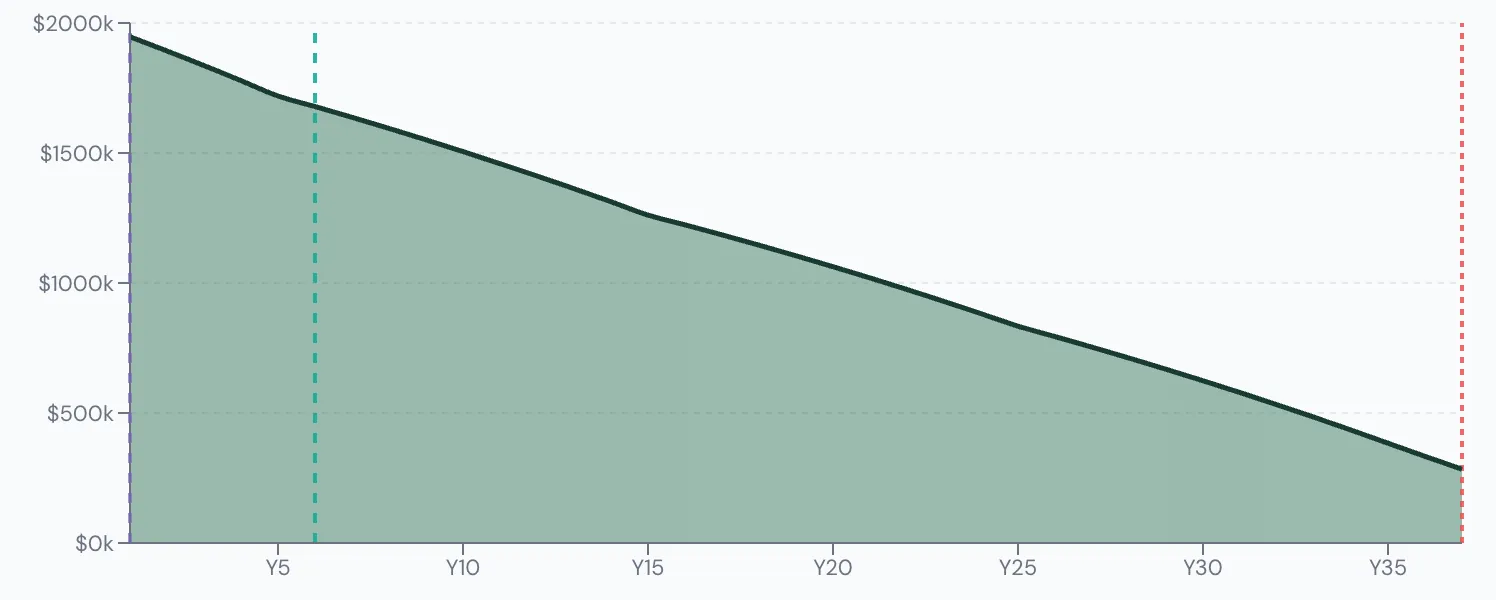
- Spends at 60
- $90,000/yr
- Money lasts
- Past 95
- Left at 95
- $333,228
Draws her RRSP down first
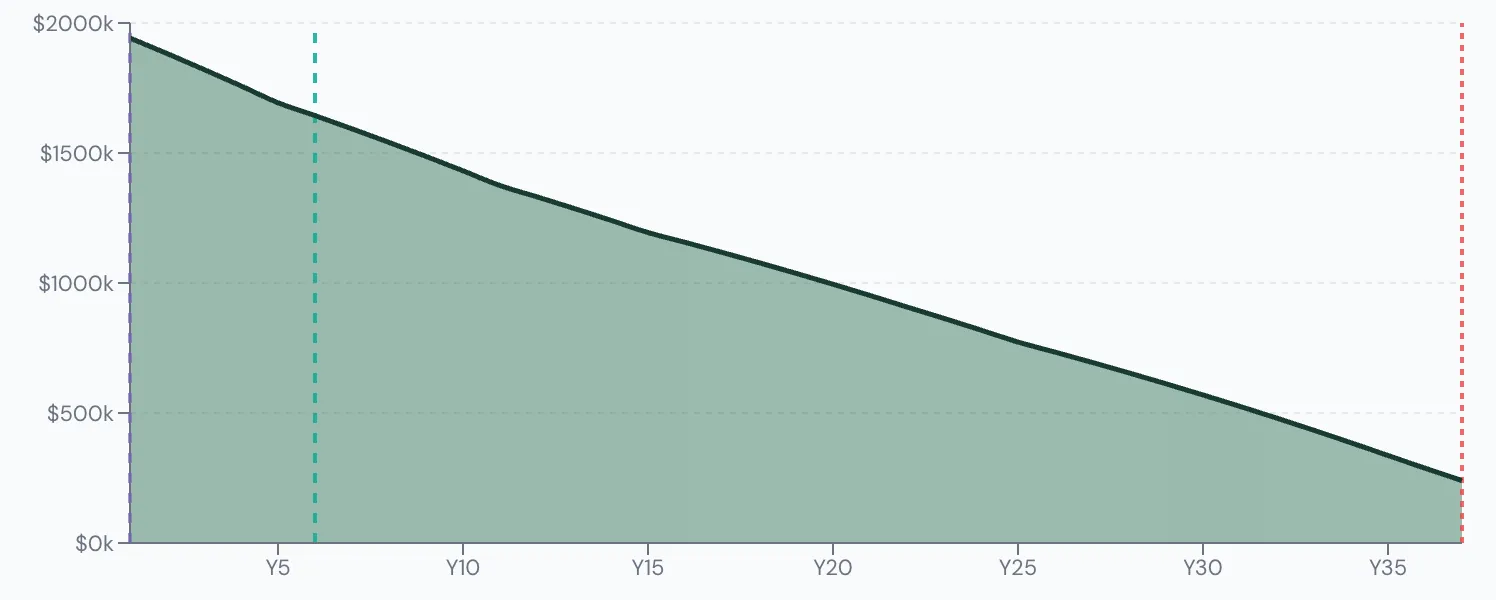
- Spends at 60
- $90,000/yr
- Money lasts
- Past 95
- Left at 95
- $287,668
Delays OAS to 70
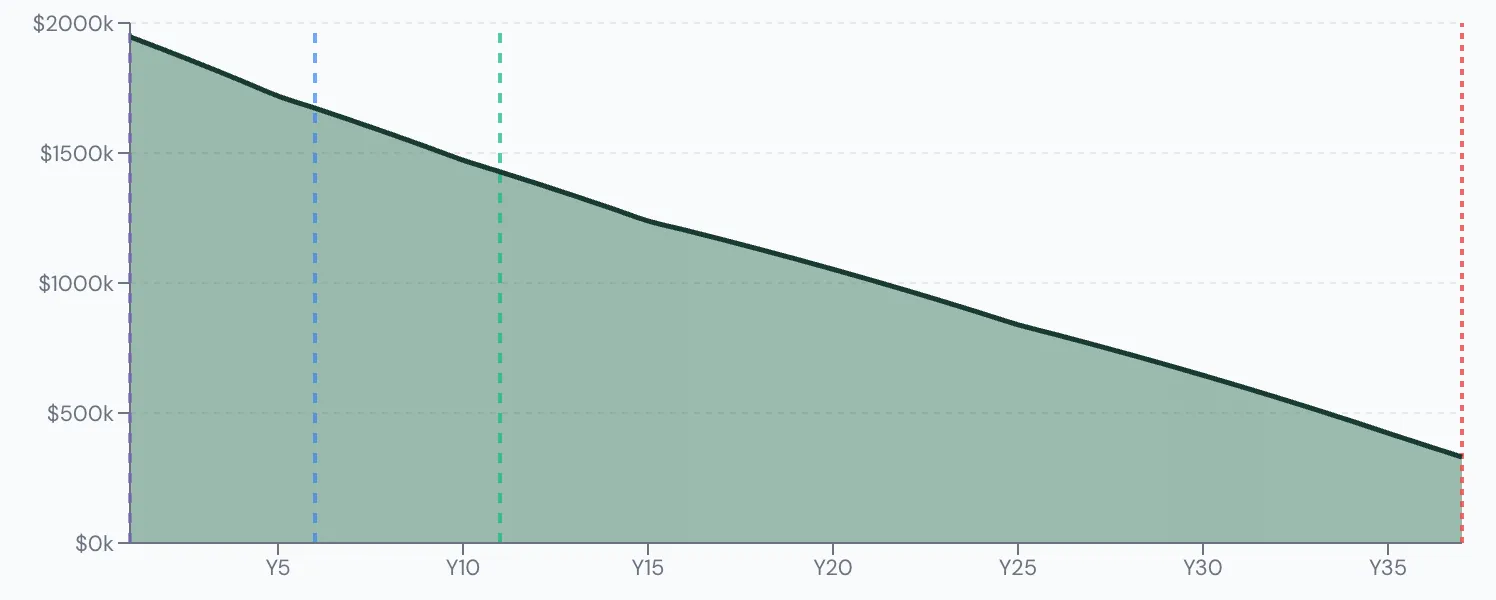
- Spends at 60
- $90,000/yr
- Money lasts
- Past 95
- Left at 95
- $376,159
Saves her TFSA for last
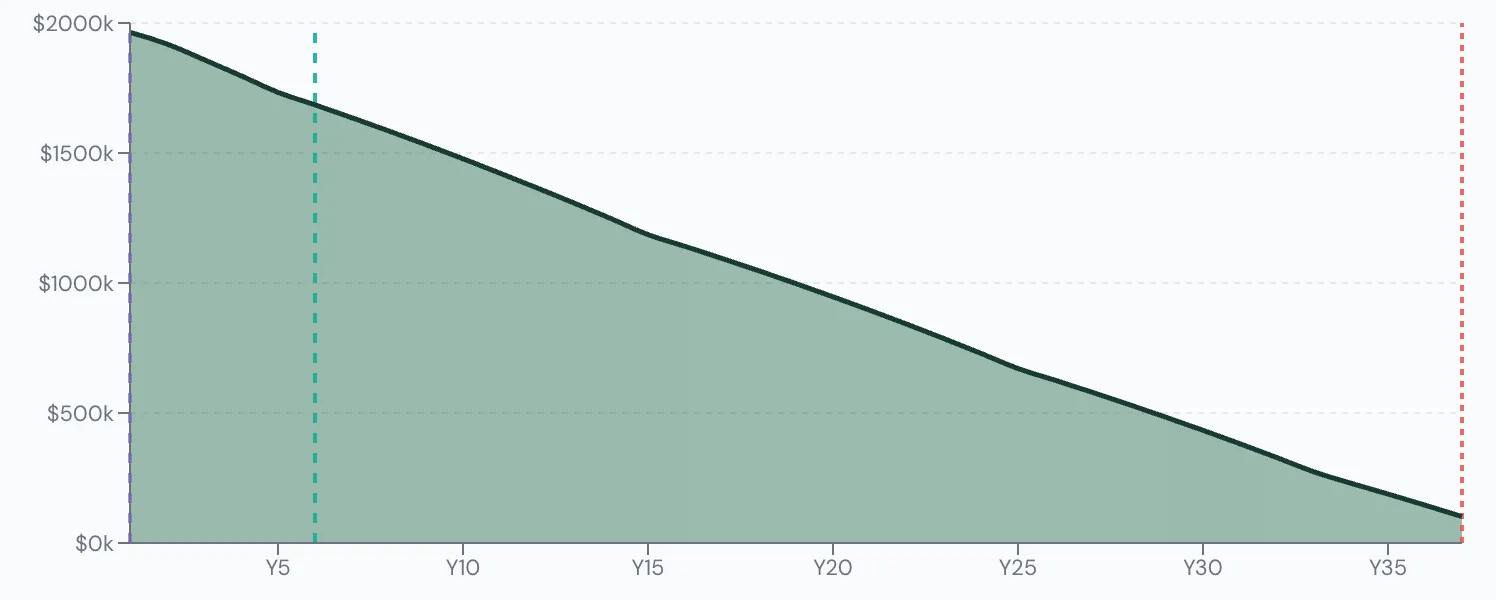
- Spends at 60
- $90,000/yr
- Money lasts
- Past 95
- Left at 95
- $145,602
Scenario 1
Draws her RRSP down first
- Spends at 60
- $90,000/yr
- Money lasts
- Past 95
- Left at 95
- $287,668
The usual advice for a large RRSP is the "RRSP meltdown": draw it down first, while your income is otherwise low. Scenario Lab+ runs this as its RRSP Meltdown drawdown strategy, which funds all of her spending from her RRSP until 71.
It lowers her lifetime tax by about $10,600, to $662,956. But it doesn't help with the clawback. Every dollar she spends from 65 to 70 now comes from her RRSP, so her taxable income rises and she repays $4,206 of OAS a year, about $25,000 in total instead of $16,000.
She also finishes with less: $287,668 at 95, about $45,600 below her original plan. She pays her tax earlier, and money paid in tax at 62 has no chance to grow. More of what is left is in her TFSA, which is tax-free, so the gap after tax is smaller than it looks. It is still a gap.
Scenario 2
Delays OAS to 70
- Spends at 60
- $90,000/yr
- Money lasts
- Past 95
- Left at 95
- $376,159
Karen doesn't need her OAS at 65. What if she delays it to 70? OAS rises 0.6% for every month you wait, 36% in all, so she'd receive $12,114 a year from 70 instead of $8,908 from 65.
Delaying OAS helps on every count. From 65 to 69 she has no OAS to claw back. From 70 to 74 she repays about $1,700 a year, so her total clawback is about $8,400 instead of $16,000. She collects about $45,600 more OAS over her retirement, and she finishes at 95 with $376,159, about $43,000 more than her original plan. Scenario Lab+ estimates her room to spend more rises to about $343 a month.
Delaying OAS is a bet on living past your early eighties. Our CPP and OAS break-even calculator shows where that line falls for you.
Scenario 3
Saves her TFSA for last
- Spends at 60
- $90,000/yr
- Money lasts
- Past 95
- Left at 95
- $145,602
A common instinct is to save the TFSA for last, because its withdrawals are tax-free. Scenario Lab+ runs this as its Sequential strategy: non-registered savings first, then the RRSP, and the TFSA last.
For Karen it's the most expensive choice we tested. Her non-registered account is gone by 61, so from then on all of her spending is taxable RRSP money. She repays OAS every year from 65 to 84, about $56,800 in total. Over her retirement she pays $762,055 in tax, about $88,000 more than her original plan.
She finishes at 95 with $145,602, all of it in her TFSA. That money is tax-free, so it is worth more per dollar than her original plan's RRIF balance, but the total is $188,000 lower.
The Drawdown tab compares four strategies side by side:
 Cumulative tax under each drawdown strategy in the Drawdown tab.
Your $2 Million Is Not Karen's $2 Million
So can you retire at 60 with $2 million? Karen can, with $7,500 a month to spend. But her plan is a starting point, not an answer for anyone else.
Two people with $2 million can pay very different amounts of tax. The biggest difference is often where the money is: $2 million mostly in an RRSP, like Karen's, carries a tax bill that $2 million spread across a TFSA and a non-registered account doesn't. For someone with the same savings retiring five years later, see Daniel's plan at 65. For half as much at 60, see Michael's plan.
The bigger risk with a large RRSP is drawing it down in whatever order feels natural, without seeing what each order costs.
That's why we built Scenario Lab+.
It is the software behind every number in this article. Give it your own accounts and spending, and it builds the same year-by-year plan for you, including every what-if above. If you'd like to see it first, Karen's full plan is open to explore.
Build Your Own Canadian Retirement Plan
Enter your own savings, benefits, and spending in Scenario Lab+ to see whether your number is enough and what happens when your assumptions change.
Start now