

The short answer
- Not on her savings alone: $600,000 at 60 covers Grace's $4,500 a month until she's 75.
- A $400,000 inheritance at 68 makes her plan work, with $111K left at 95.
- The same inheritance at 78 arrives after her savings have already run out.
Estimates from Scenario Lab+, in today's dollars.
See the demo planPlenty of people in their late fifties and sixties have a quiet line in their retirement plan: the inheritance. A parent's house, a share of an estate, money that will probably come one day. It can make a real difference, but nobody knows when it will arrive, or how much will be left by then.
Here at Loonie Nest, our mission is to provide free and affordable personal finance education to Canadians so they can gain confidence in their retirement.
Grace's plan at a glance
$600,000
saved at 60
RRSP
$380,000
Taxed as income when withdrawn
TFSA
$150,000
Withdrawals are tax-free
Non-registered
$70,000
Only the capital gain is taxed
Spending after tax, in today's dollars
$54,000
$48,600
$43,200
CPP $900 a month from 65
OAS $742 a month from 65
Our $600K Retirement Scenario
Let's meet Grace. She's 60, single, and living in Victoria, BC. She spent her career as a graphic designer at a small agency, without a workplace pension. Her mother is 88 and owns her house, and Grace expects to inherit about $400,000 one day. She'd like to stop working now, and she wants to know whether she can, and how much the inheritance matters.
We'll run Grace's numbers through Scenario Lab+.
Scenario Lab+ is our proprietary retirement planning software. We'll use it to generate and review a tailored retirement plan for her.
To start, here's how Grace's numbers look as she retires at 60, without the inheritance:
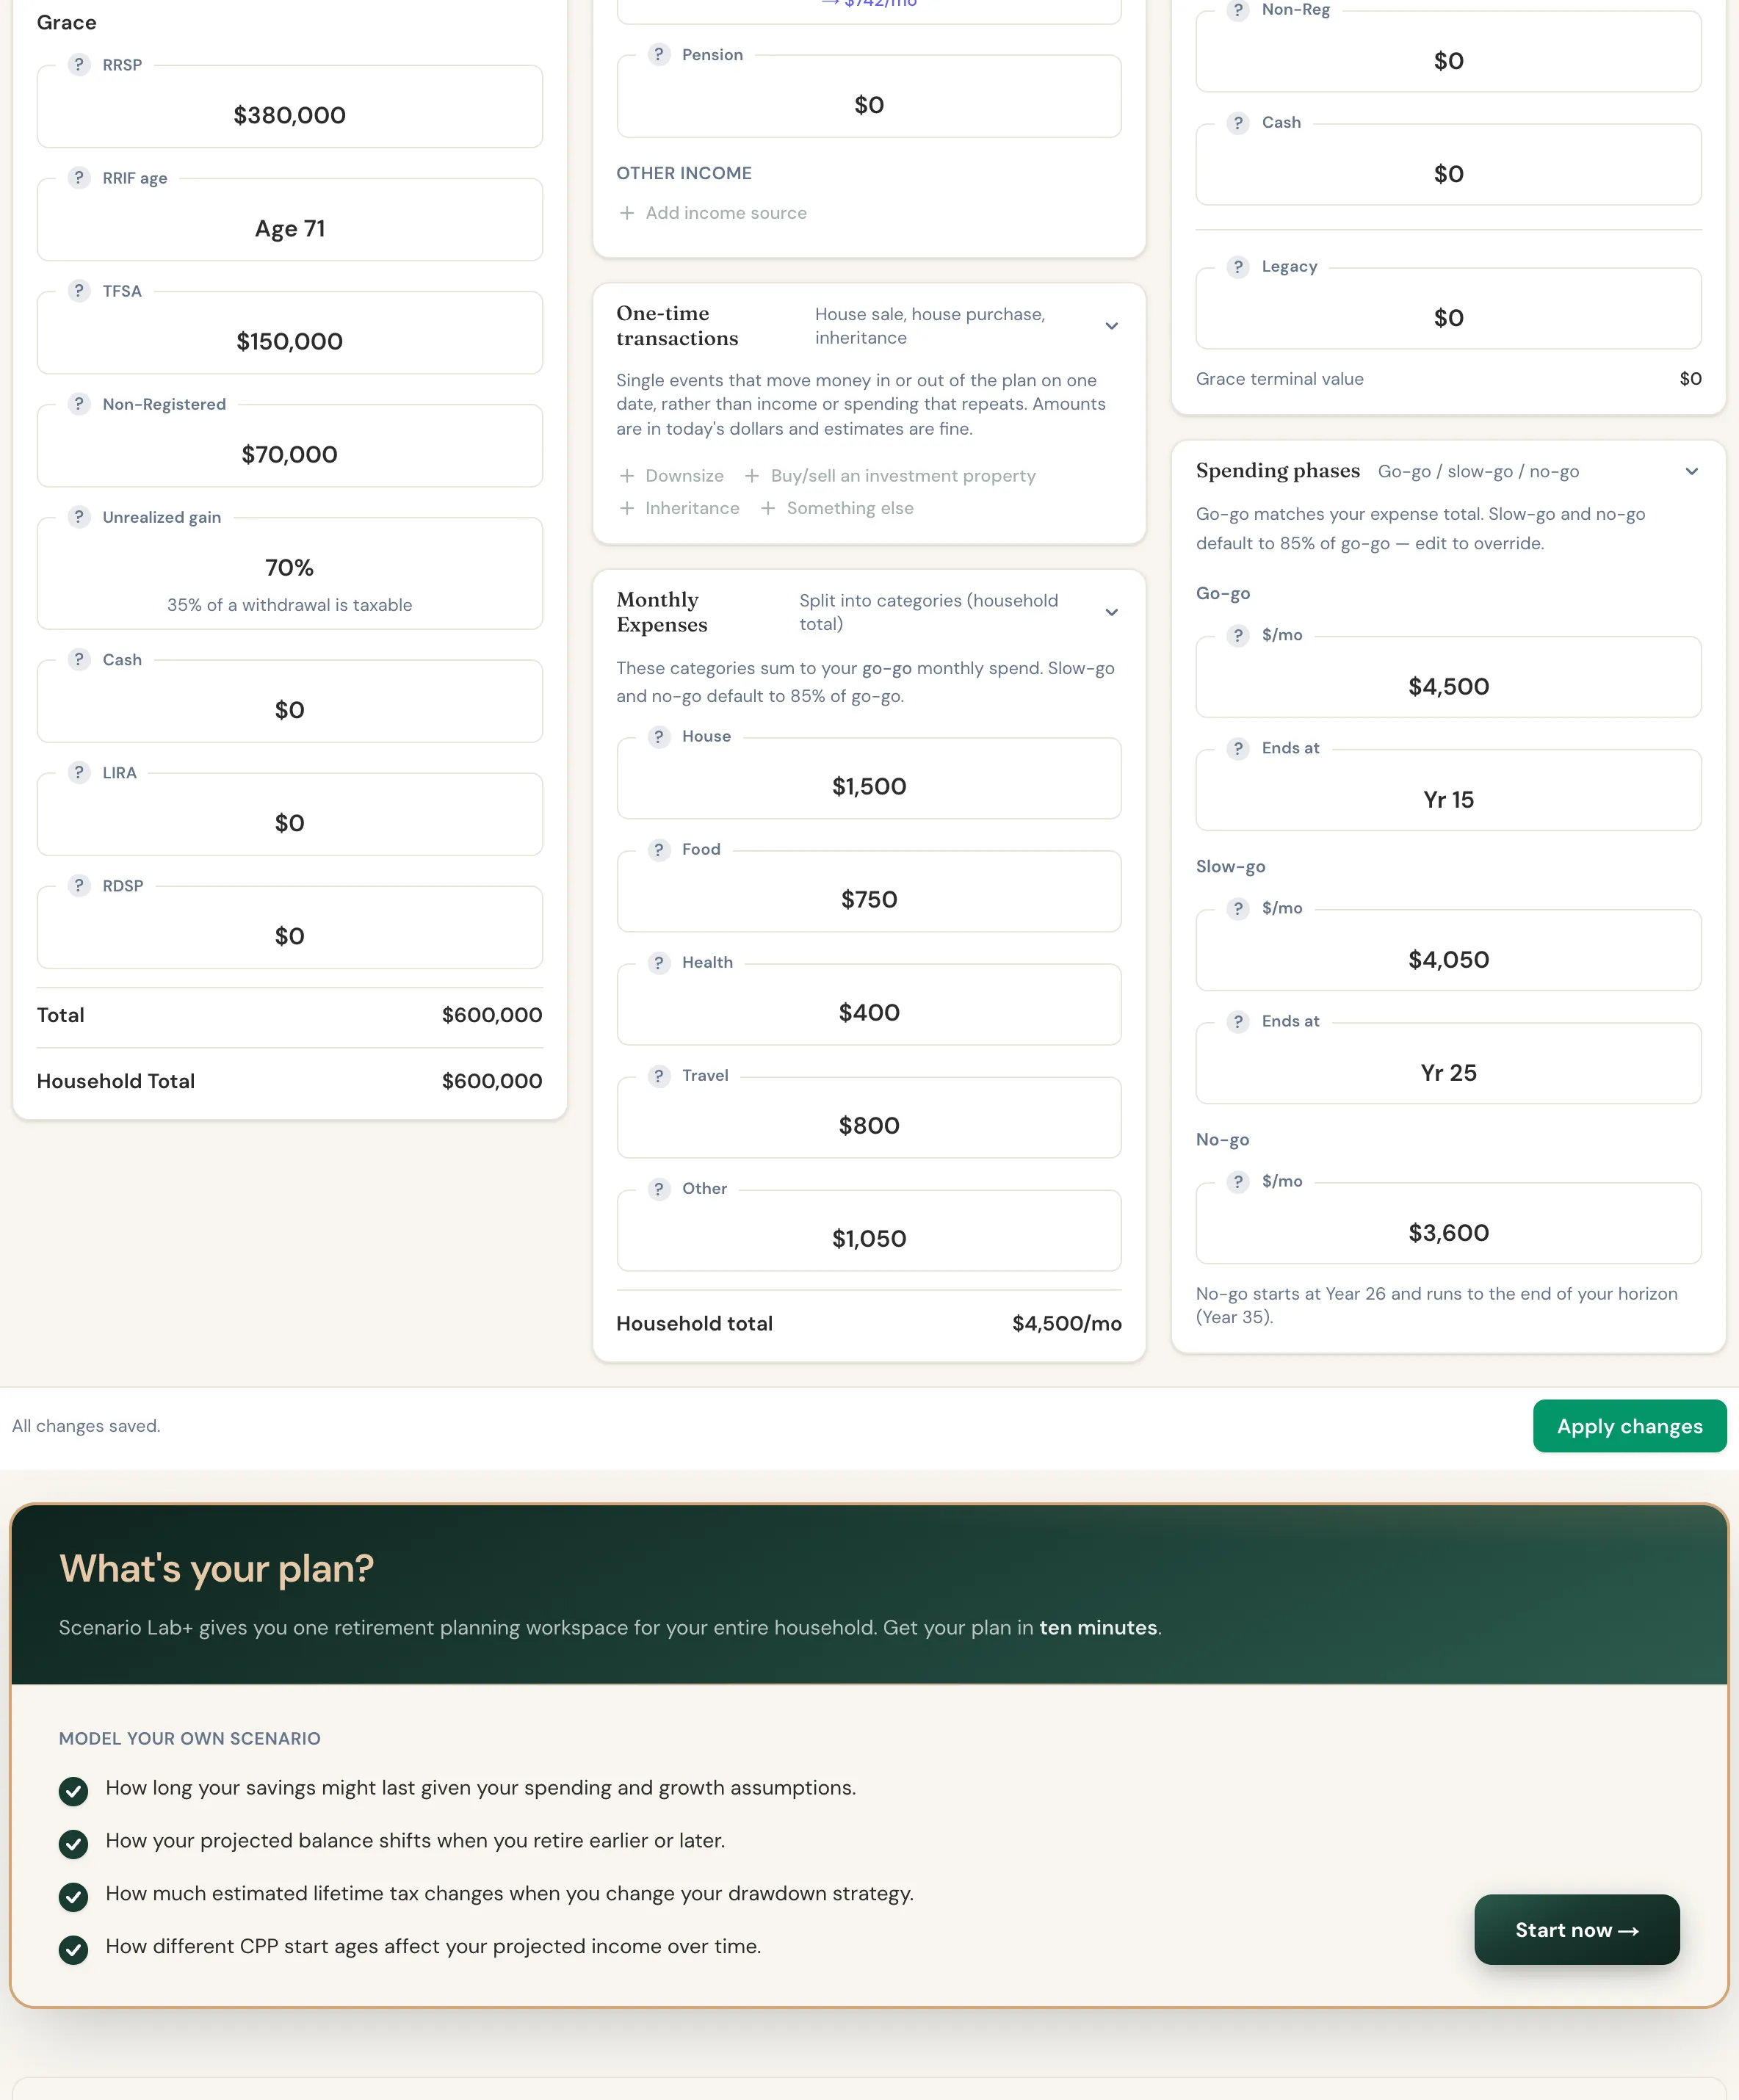 Grace's plan inputs: her profile, account balances, CPP and OAS, and monthly spending.
$600,000 of savings. She has $380,000 in her RRSP, $150,000 in her TFSA, and $70,000 in a non-registered account.
Grace's CPP is $900 a month at 65. Five empty years before 65 bring the amount down a little. She gets the full OAS at 65. If you want a refresher on how both programs work, see our guide to CPP and OAS.
Her spending falls as she ages. Her plan starts at $4,500 a month and steps down at 75 and again at 85. In Scenario Lab+, these steps are the plan's Spending Phases.
A few other important assumptions: all figures are in today's dollars, Grace owns her condo with no mortgage, she expects her investments to grow 5% a year, inflation runs at 2.5% a year, and we plan her retirement to age 95.
Grace's retirement budget
| Category | Monthly | Annual |
|---|---|---|
| Housing (strata fees, property tax, utilities, insurance) | $1,500 | $18,000 |
| Food and dining | $750 | $9,000 |
| Health and dental | $400 | $4,800 |
| Travel | $800 | $9,600 |
| Everything else (car, gifts, entertainment) | $1,050 | $12,600 |
| Total | $4,500 | $54,000 |
Is $600K Enough to Retire at 60?
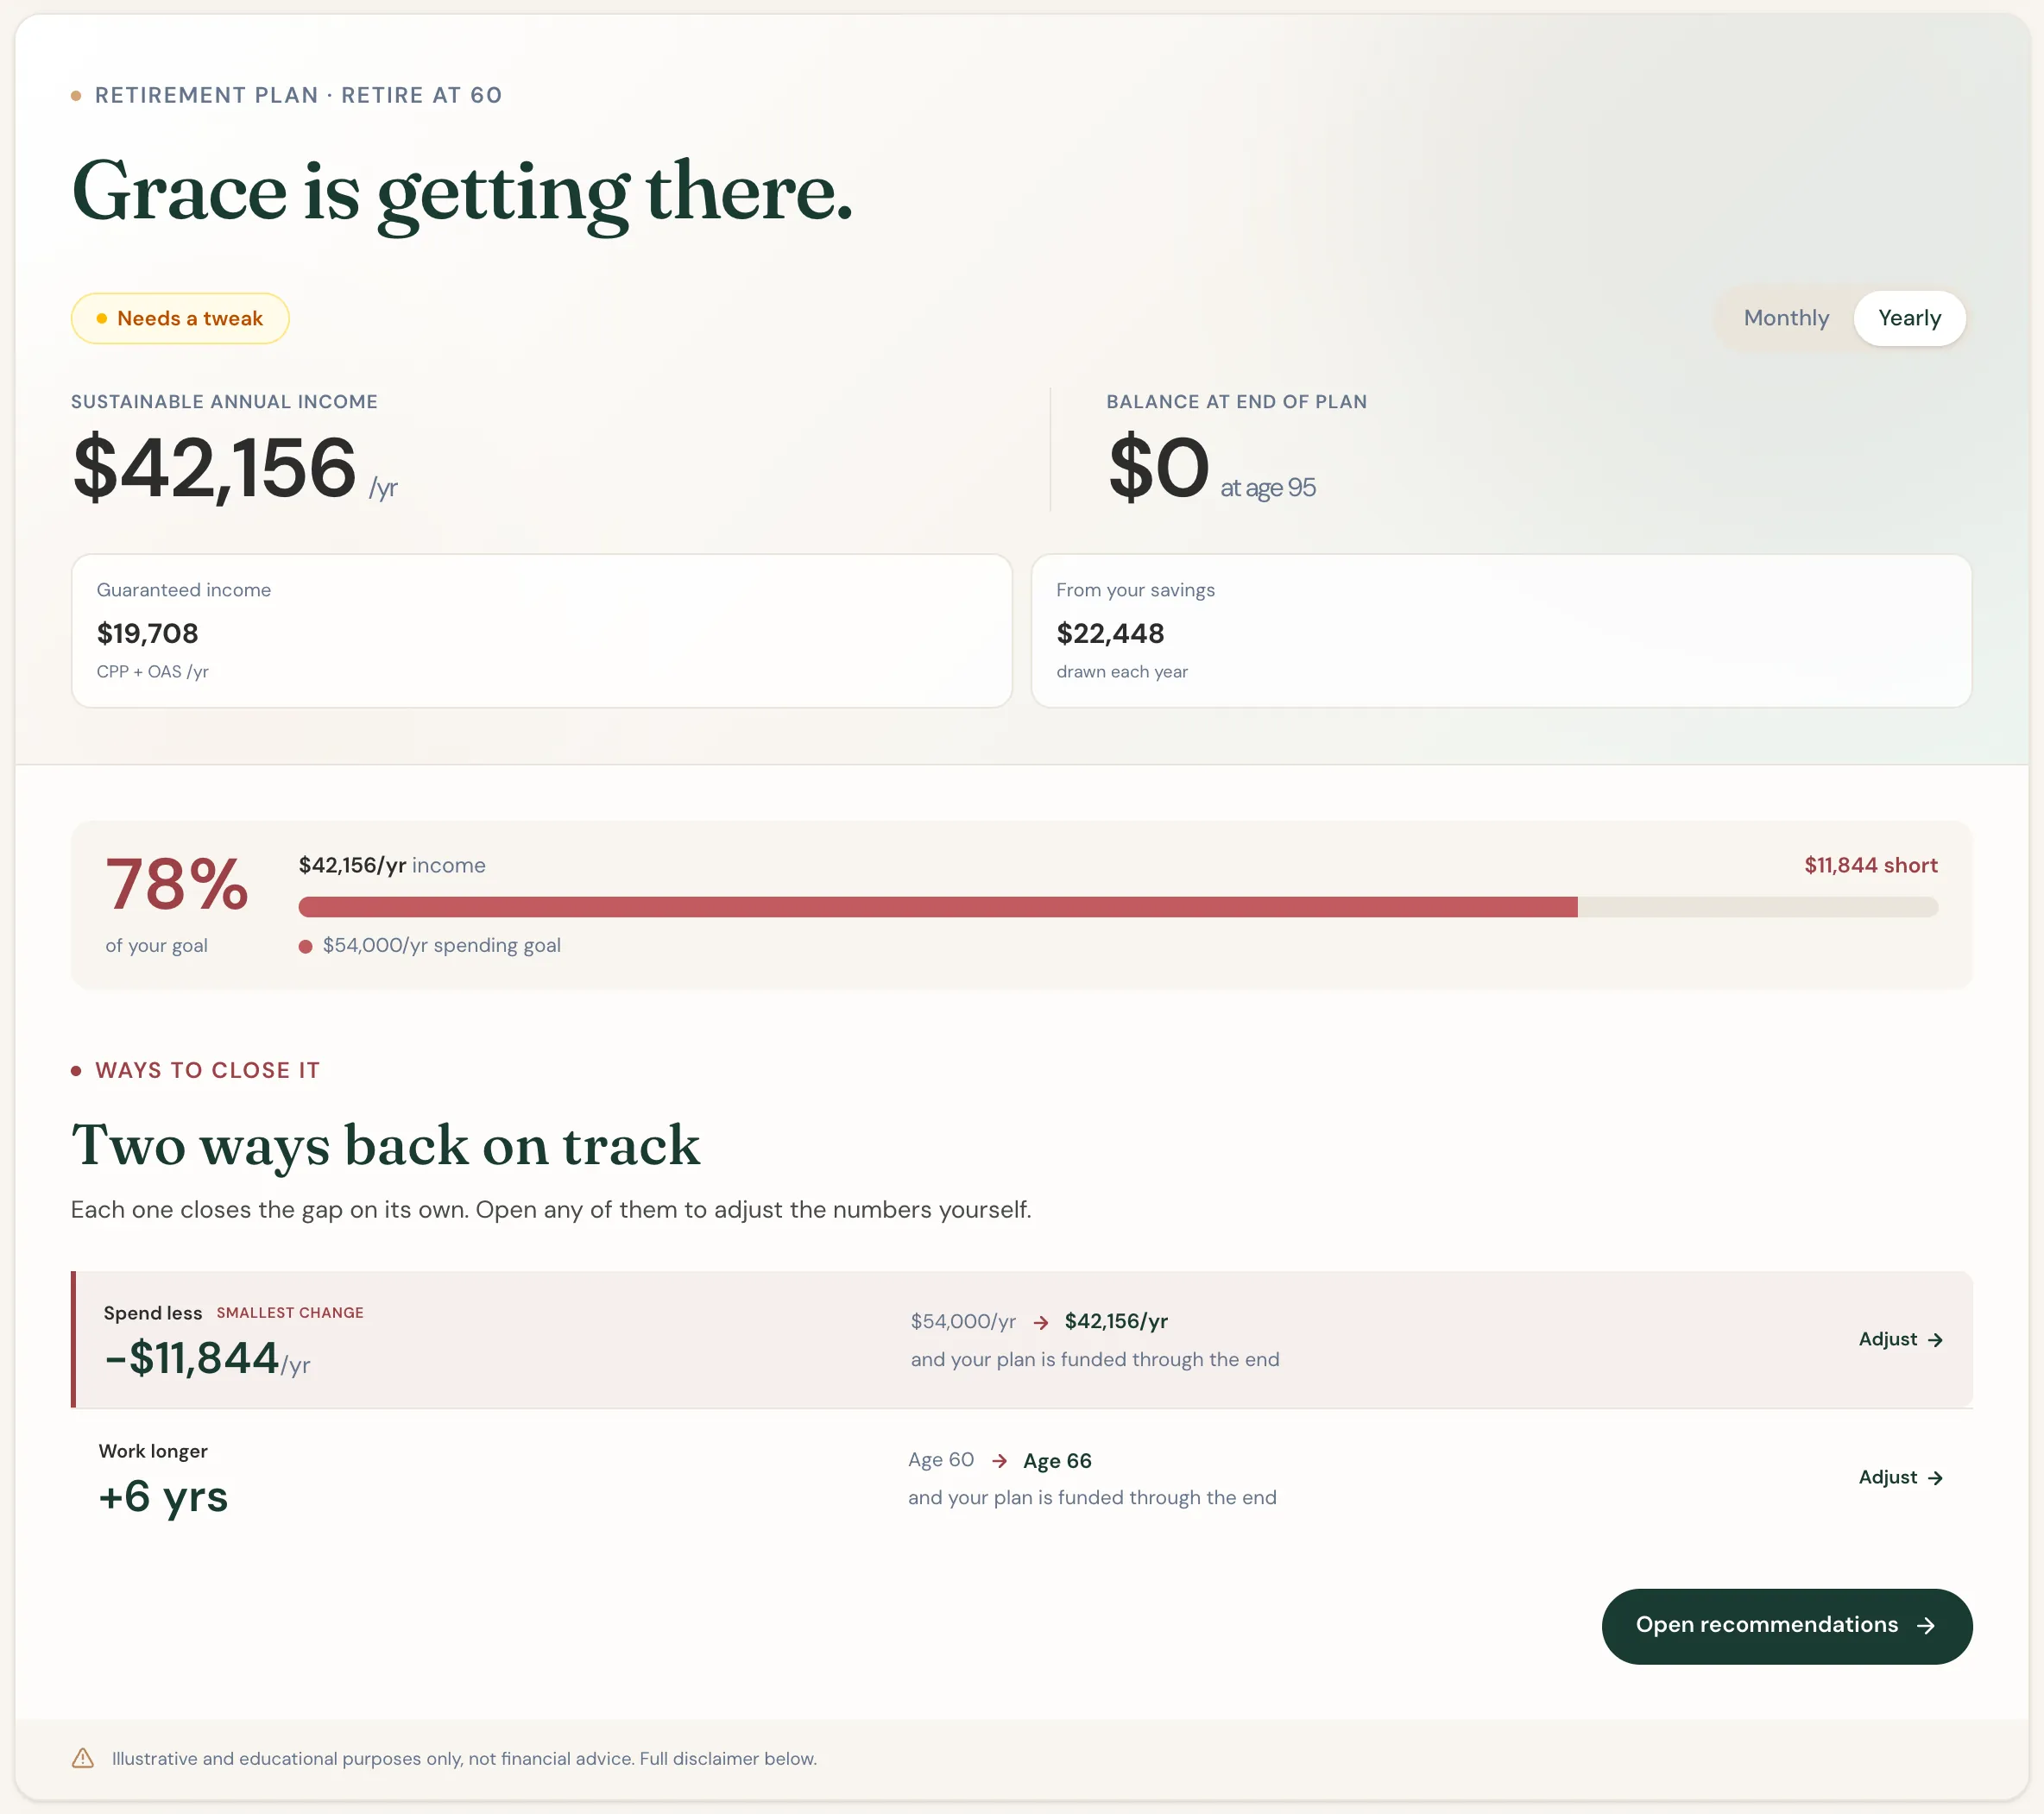 Scenario Lab+'s results for Grace's plan, without the inheritance.
Not on its own. Without the inheritance, Scenario Lab+ estimates Grace's savings run out at 75. After that she'd have only her CPP and OAS, about $20,600 a year, against a budget of $48,600.
She draws $58,715 from her savings in her first year, nearly 10% of her portfolio, because she has five years before CPP and OAS start. That's a pace $600,000 can't keep up for long.
Scenario Lab+'s Recommendations tab offers two fixes without the inheritance: spend $987 a month less, or keep working until 66. The question for Grace is whether the inheritance can stand in for either.
How Much Income Does $600K Provide?
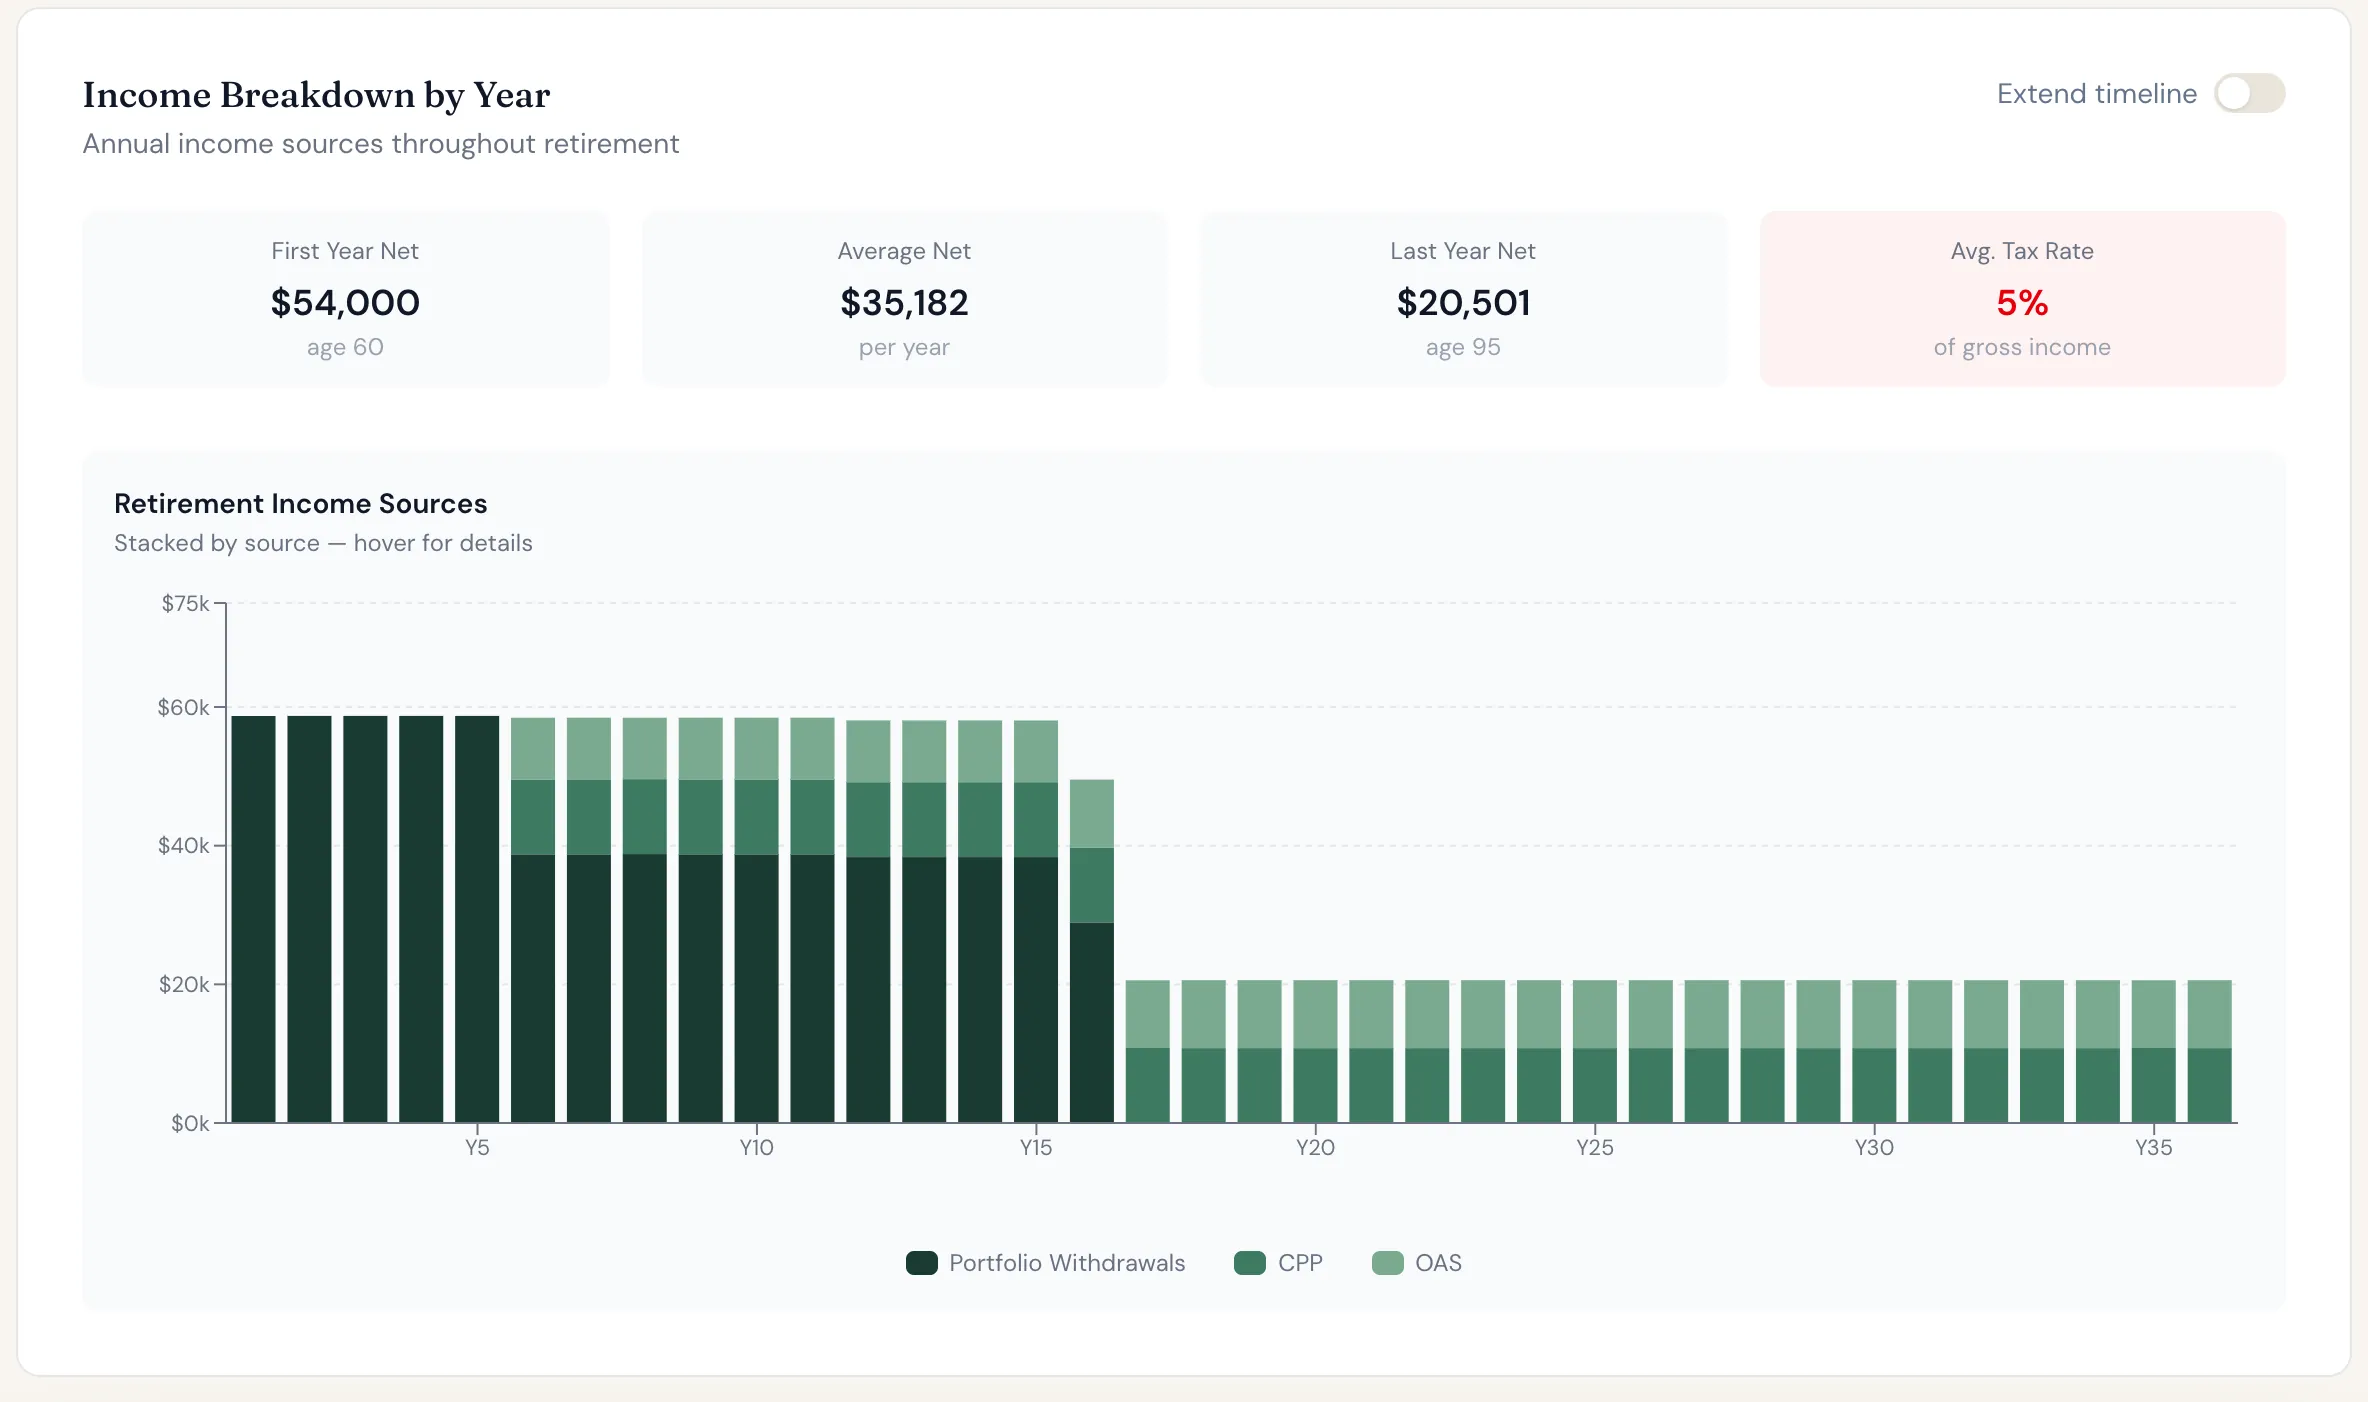 Where Grace's income comes from each year, by source.
| Source | Age 60 | Age 65 | Taxable? |
|---|---|---|---|
| CPP | $0 | $10,800 | Yes |
| OAS | $0 | $8,908 | Yes |
| RRSP withdrawals | $37,186 | $24,541 | Yes |
| TFSA withdrawals | $14,679 | $9,687 | No |
| Non-registered withdrawals | $6,850 | $4,521 | Only the capital gain |
| Gross income | $58,715 | $58,457 | |
| Income tax | $4,715 | $4,457 | |
| Spending money | $54,000 | $54,000 |
Is an inheritance part of your plan?
Scenario Lab+ lets you add a one-time amount at any age and see your plan with it and without it, side by side.
Try Scenario Lab+How Much Tax Grace Pays
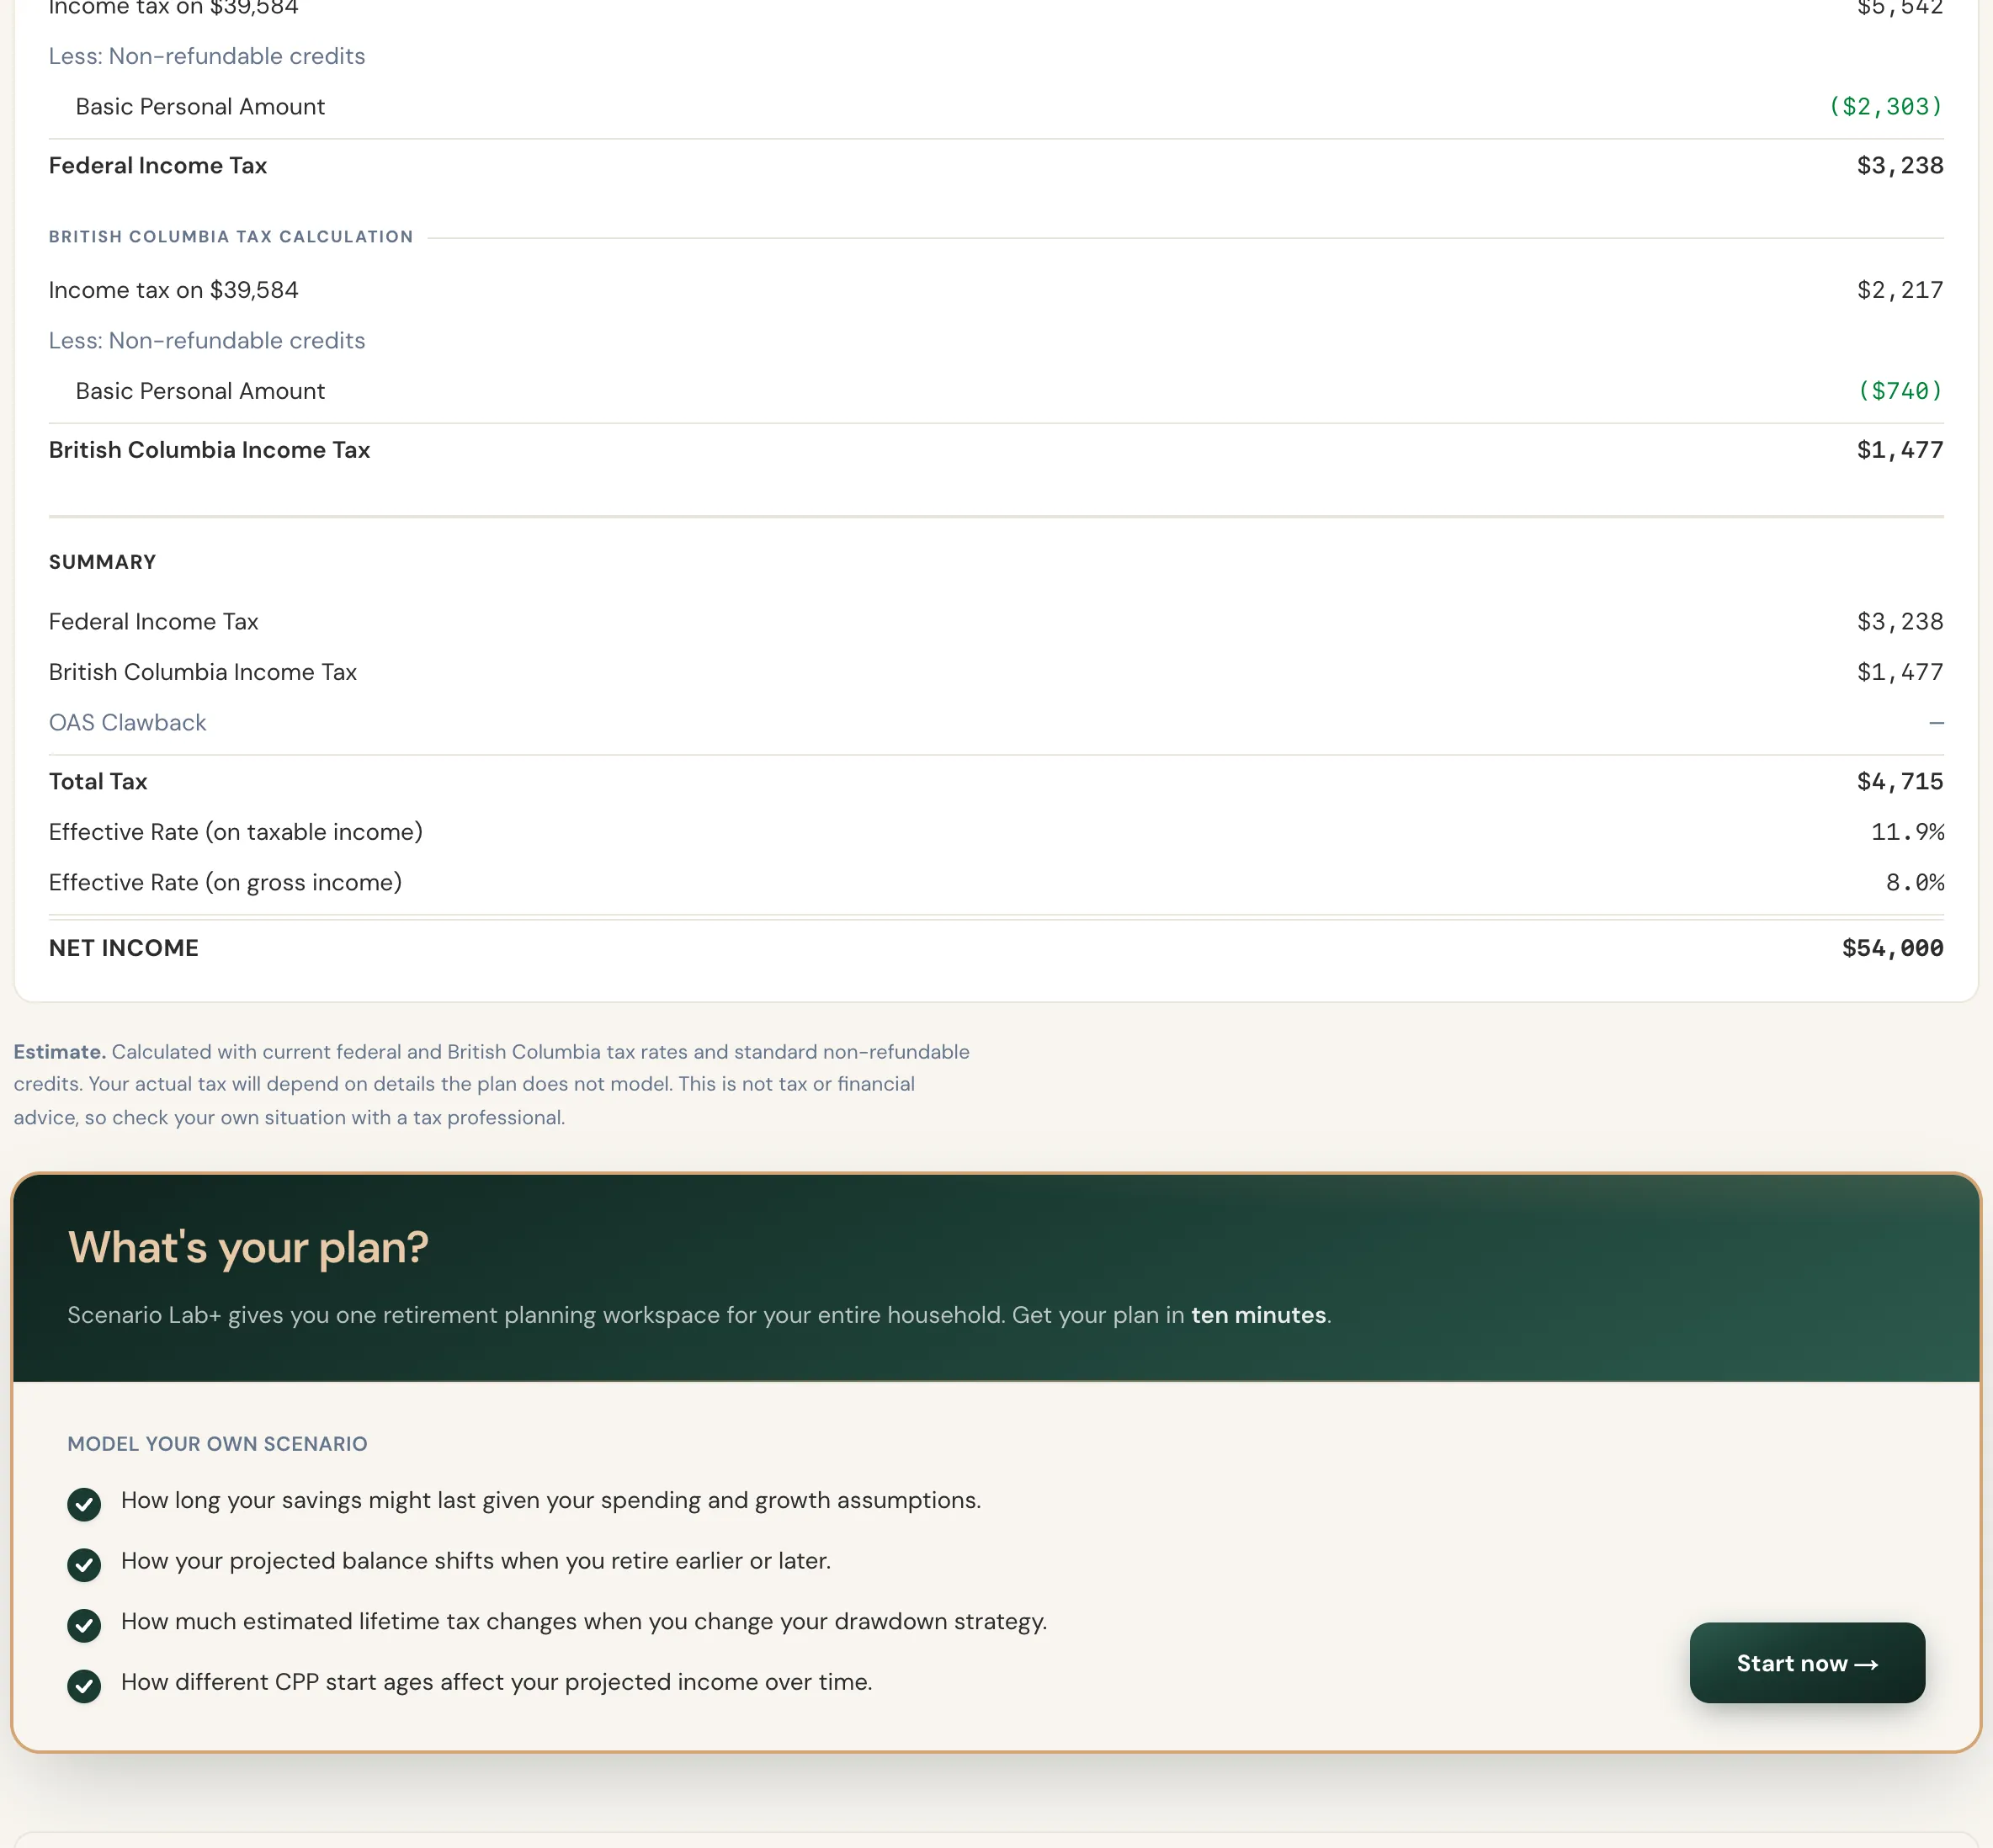 Grace's tax bill in her first year of retirement, at age 60.
Grace pays $4,715 in income tax in her first year, about 8% of her income. Her TFSA withdrawals aren't taxable, and only the capital gain on her non-registered withdrawals is.
An inheritance itself wouldn't add to her tax bill. In Canada, tax on an estate is settled on the deceased person's final return, including tax on gains from property treated as sold at death, before the money is passed on (CRA). Once it's invested, the income it earns is taxable to her as usual.
How Her Plan Changes Over Time
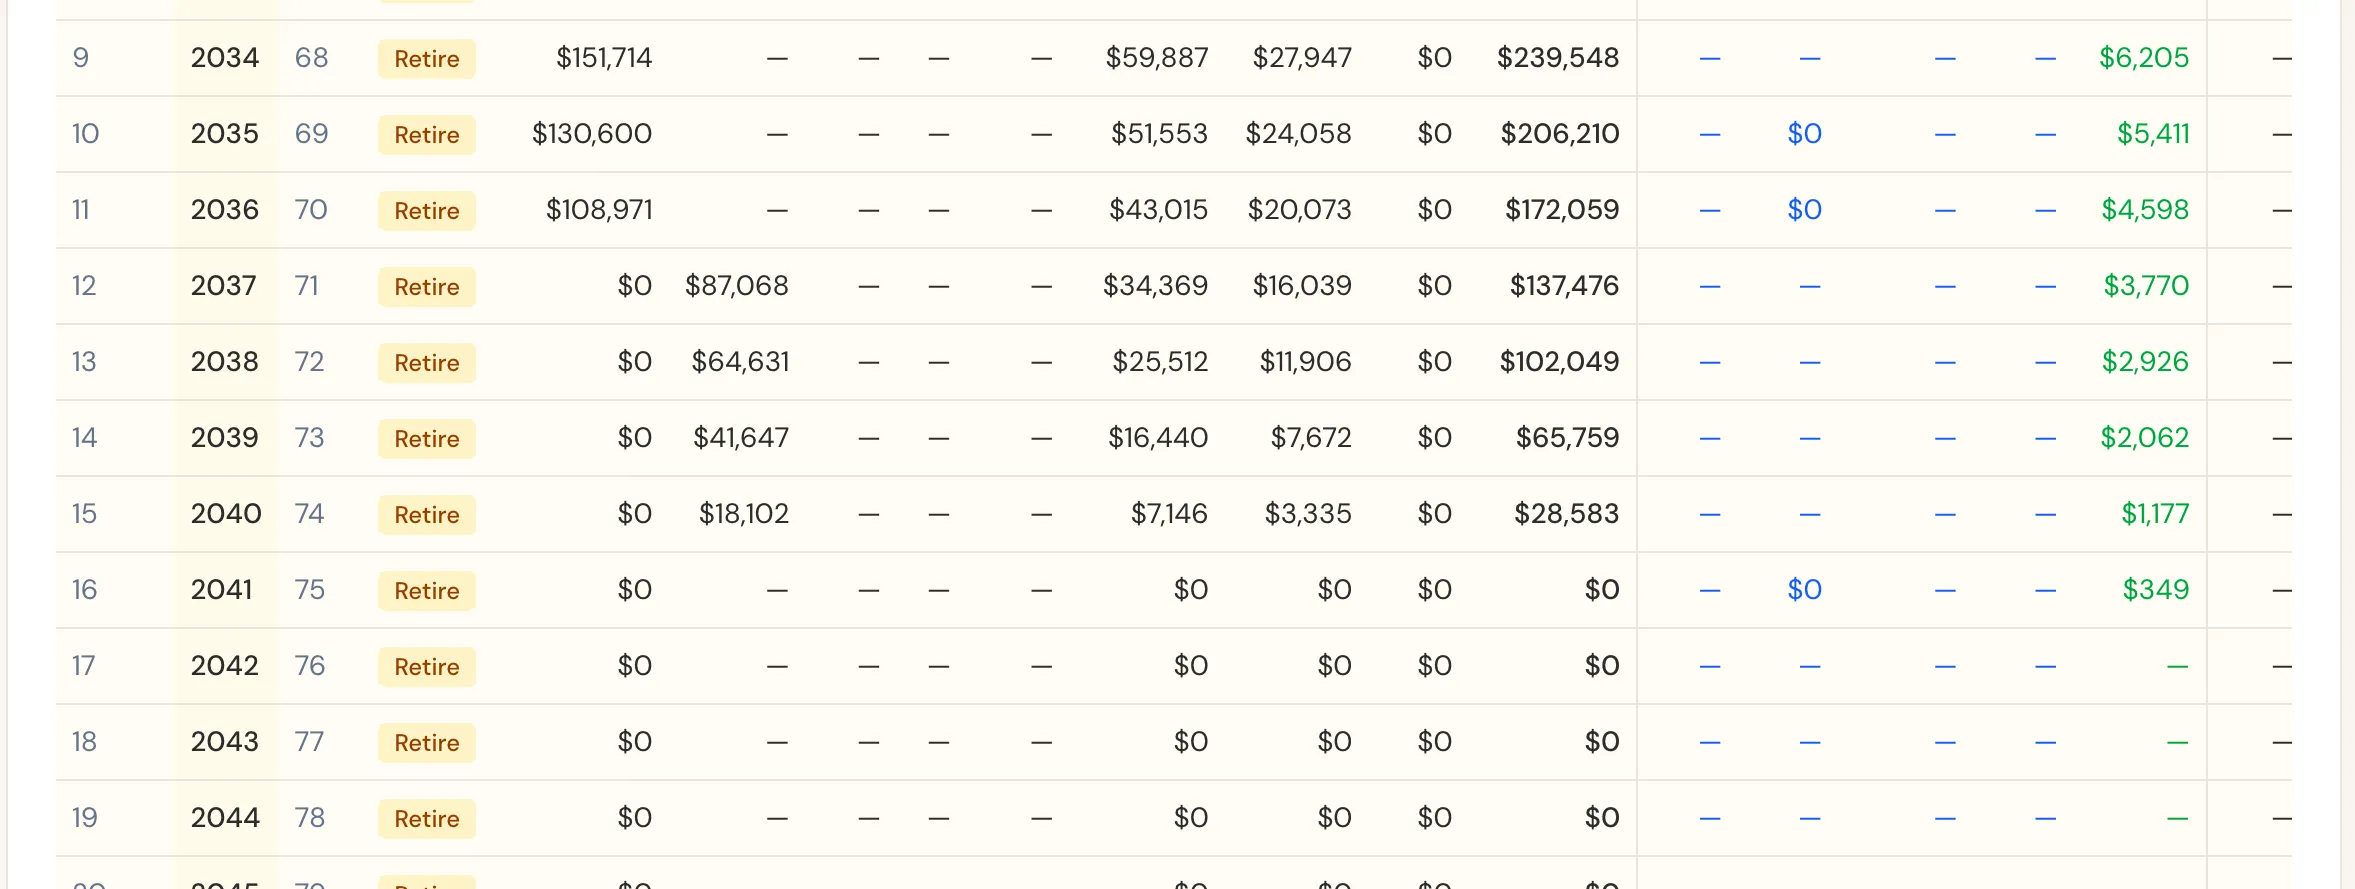 Year-by-year account balances from 60, without the inheritance.
From 60 to 64, everything comes from her savings. Her portfolio falls from $600,000 to about $365,000.
At 65, CPP and OAS start. They pay $19,708 a year, and her withdrawals fall by a third.
At 75, her savings run out. Her spending steps down that year, but not enough.
But What If We Change the Assumptions?
We added the inheritance to Grace's plan with the One-Time Transactions feature in Scenario Lab+: a one-off amount at an age she chooses, paid into the account she chooses. We changed its timing and size, one at a time.
4 versions of Grace's plan
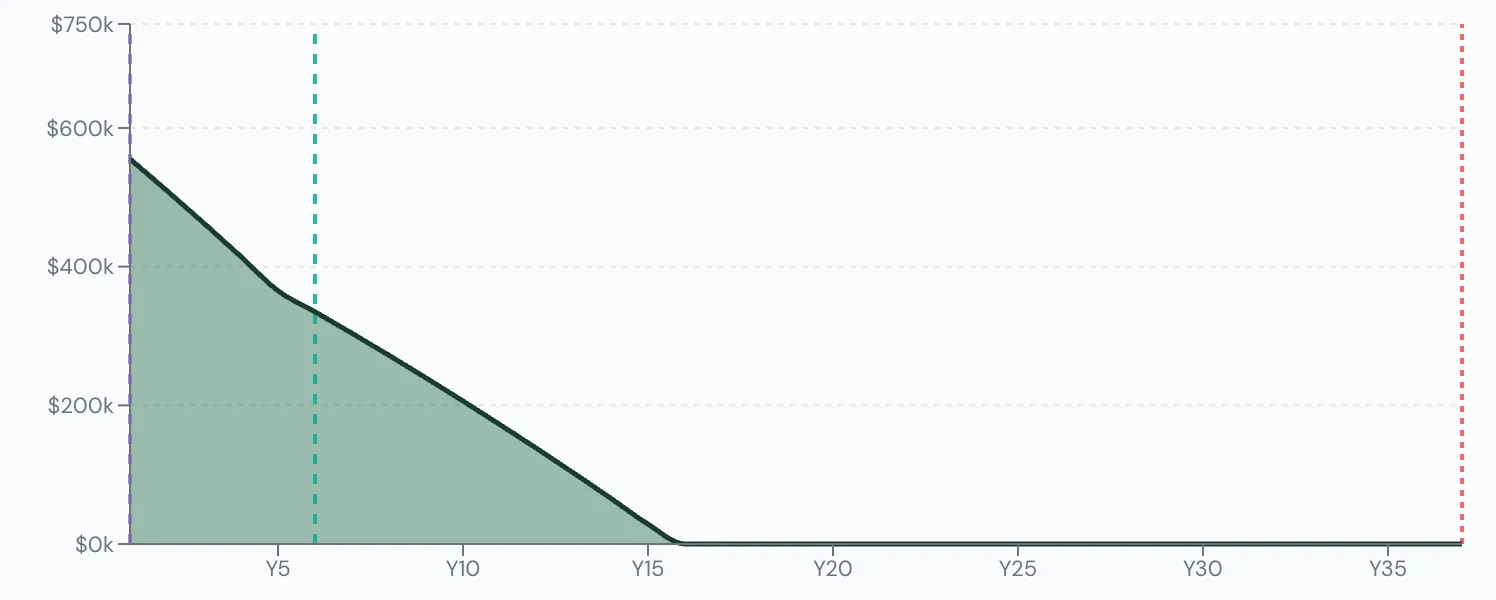
One assumption changed in each. Charts show the portfolio from 60 to 95 in Scenario Lab+.
Grace's base plan
- Spends at 60
- $54,000/yr
- Money lasts
- To age 75
- Left at 95
- $0
Inherits $400,000 at 68
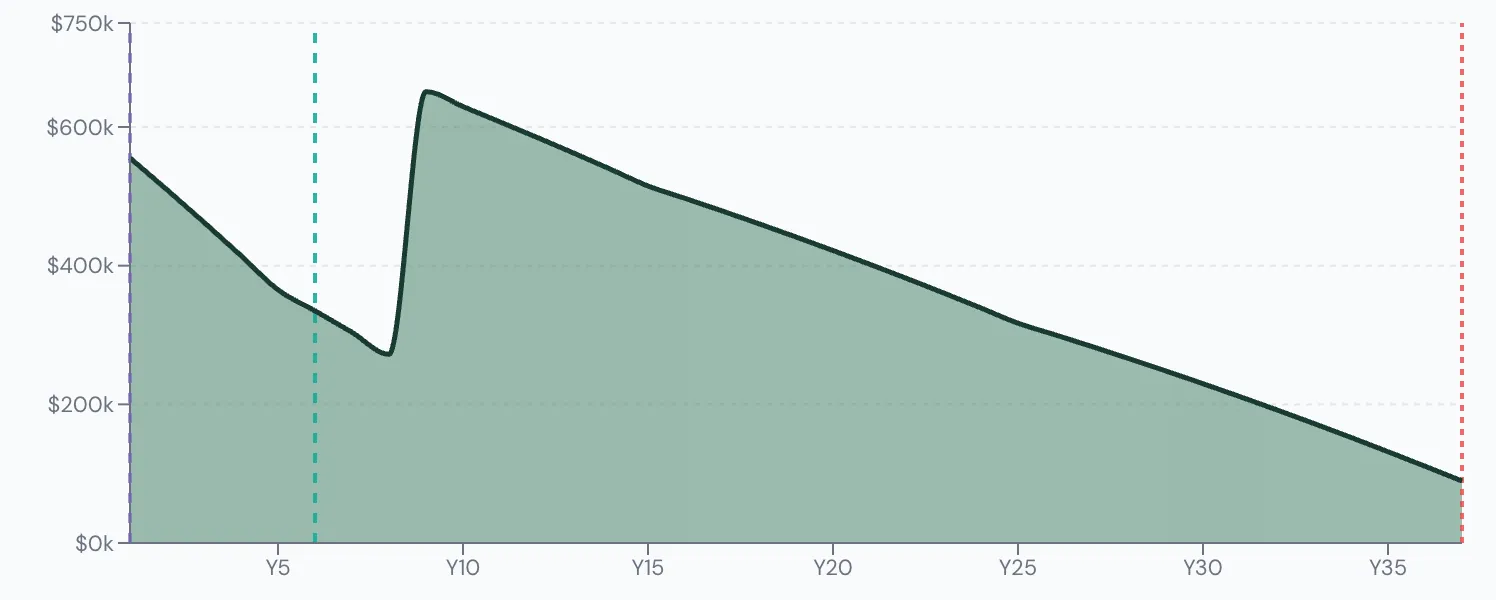
- Spends at 60
- $54,000/yr
- Money lasts
- Past 95
- Left at 95
- $110,695
Inherits $400,000 at 78
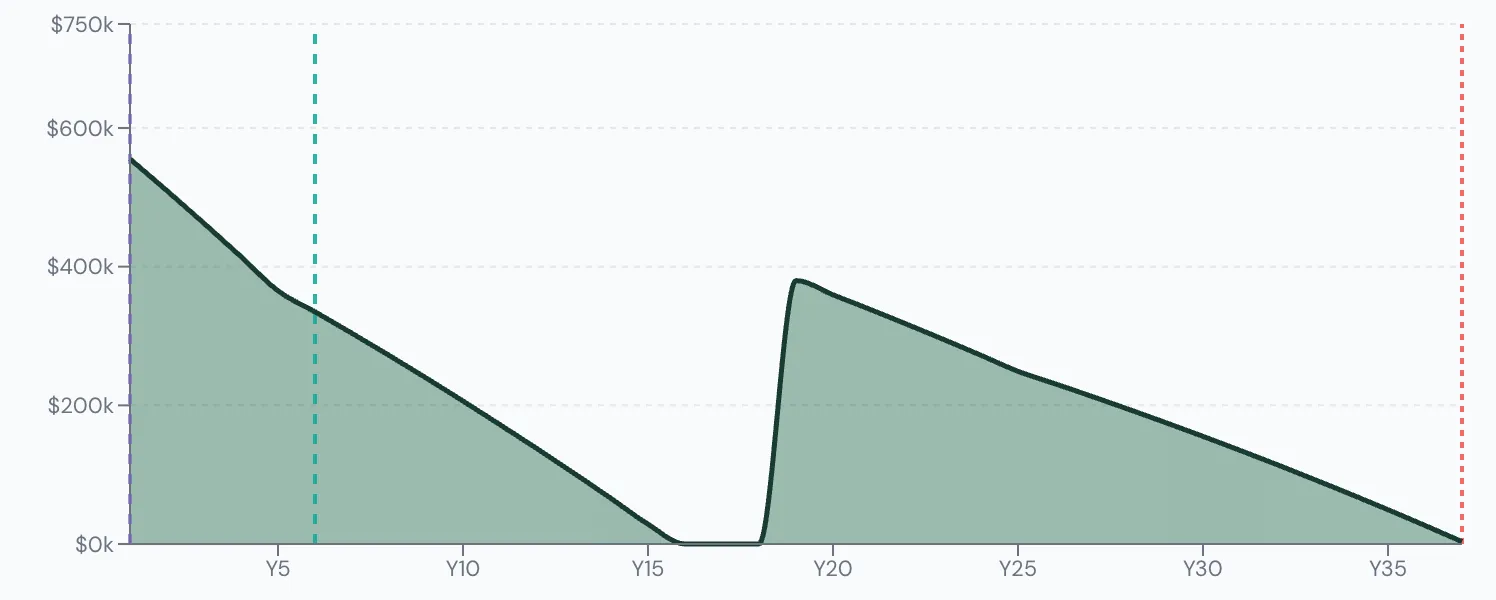
- Spends at 60
- $54,000/yr
- Money lasts
- To age 75
- Left at 95
- $26,712
Inherits $200,000 at 68
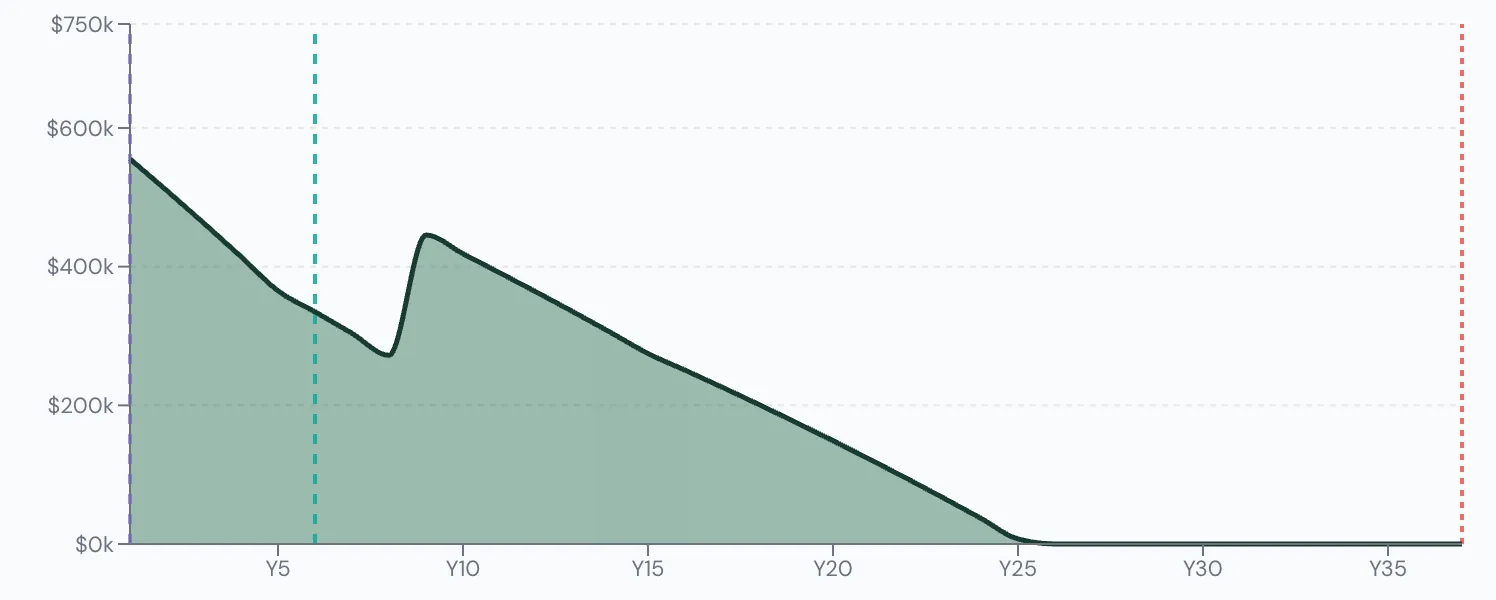
- Spends at 60
- $54,000/yr
- Money lasts
- To age 85
- Left at 95
- $0
Scenario 1
Inherits $400,000 at 68
- Spends at 60
- $54,000/yr
- Money lasts
- Past 95
- Left at 95
- $110,695
What if Grace inherits $400,000 at 68, invested in her non-registered account?
It arrives when her own savings are down to about $240,000, and it more than doubles them. Her plan now lasts to 95 with $110,695 left, and Scenario Lab+ estimates she'd have about $107 a month of room to spend more. Her taxes fall too, because more of her income now comes from non-registered savings, where only the capital gain is taxed.
Scenario 2
Inherits $400,000 at 78
- Spends at 60
- $54,000/yr
- Money lasts
- To age 75
- Left at 95
- $26,712
What if the same $400,000 arrives ten years later, at 78? Her mother would be 106, but delays happen for other reasons too, such as an estate that takes years to settle, or a parent who needs the house's value to pay for care.
Her savings run out at 75, before the money arrives. For two years she lives on CPP and OAS alone, about $20,500 a year after tax, against a budget of $48,600. Then the inheritance lands and carries her the rest of the way, with $26,712 left at 95.
Scenario Lab+ marks the plan as falling short, because of those lean years. An inheritance that arrives after you've run out doesn't help with the years before it.
Scenario 3
Inherits $200,000 at 68
- Spends at 60
- $54,000/yr
- Money lasts
- To age 85
- Left at 95
- $0
What if Grace inherits $200,000 at 68, half what she expects? Years of long-term care, or a falling property market, can shrink an estate a lot.
Her plan lasts ten years longer than with nothing, but her savings still run out at 85. To make it work, Scenario Lab+ estimates she would also need to spend $414 a month less.
Your Inheritance Is Not Grace's Inheritance
So can you retire at 60 counting on an inheritance? Grace can, if it comes when she expects and in full. If it comes late or smaller, her plan has gaps that only spending less or working longer can close. Her plan is a starting point, not an answer for anyone else.
The safest way to count on an inheritance is to build a plan that works without it, and treat the inheritance as the margin. For someone with less saved who rents, see Linda's plan at 65. For a retiree with $500,000 at 60, see Gary's plan.
The bigger risk is building your whole retirement around money that isn't yours yet.
That's why we built Scenario Lab+.
It is the software behind every number in this article. Give it your own accounts, spending, and any amount you expect to receive, and it builds the same year-by-year plan for you, including every what-if above. If you'd like to see it first, Grace's full plan is open to explore.
Build Your Own Canadian Retirement Plan
Enter your own savings, benefits, and spending in Scenario Lab+ to see whether your number is enough and what happens when your assumptions change.
Start now